Digital Payment Services

A digital payment may take only seconds, but its success depends on a coordinated flow of authentication, authorisation, processing, settlement and reconciliation. For businesses, digital payment services are no longer just a way to collect money. They influence conversion, cash flow, customer trust, operational efficiency and the ability to enter new markets.

Key Takeaways

The right strategy connects customer experience with the processes behind every transaction.

  • Digital payment services connect customers, merchants, banks, payment networks and business systems so funds and transaction data move together.
  • Payment performance depends on the full lifecycle, including routing, fraud controls, retries, refunds, settlement and reconciliation.
  • APIs and payment orchestration can reduce provider dependency and create one operational view across channels.
  • Custom digital payment software is valuable when standard products cannot support complex workflows, regional requirements or differentiated customer journeys.

What are Digital Payment Services?
Digital Payment Services

Understanding digital payments begins with seeing them as an end-to-end business capability rather than a checkout feature.

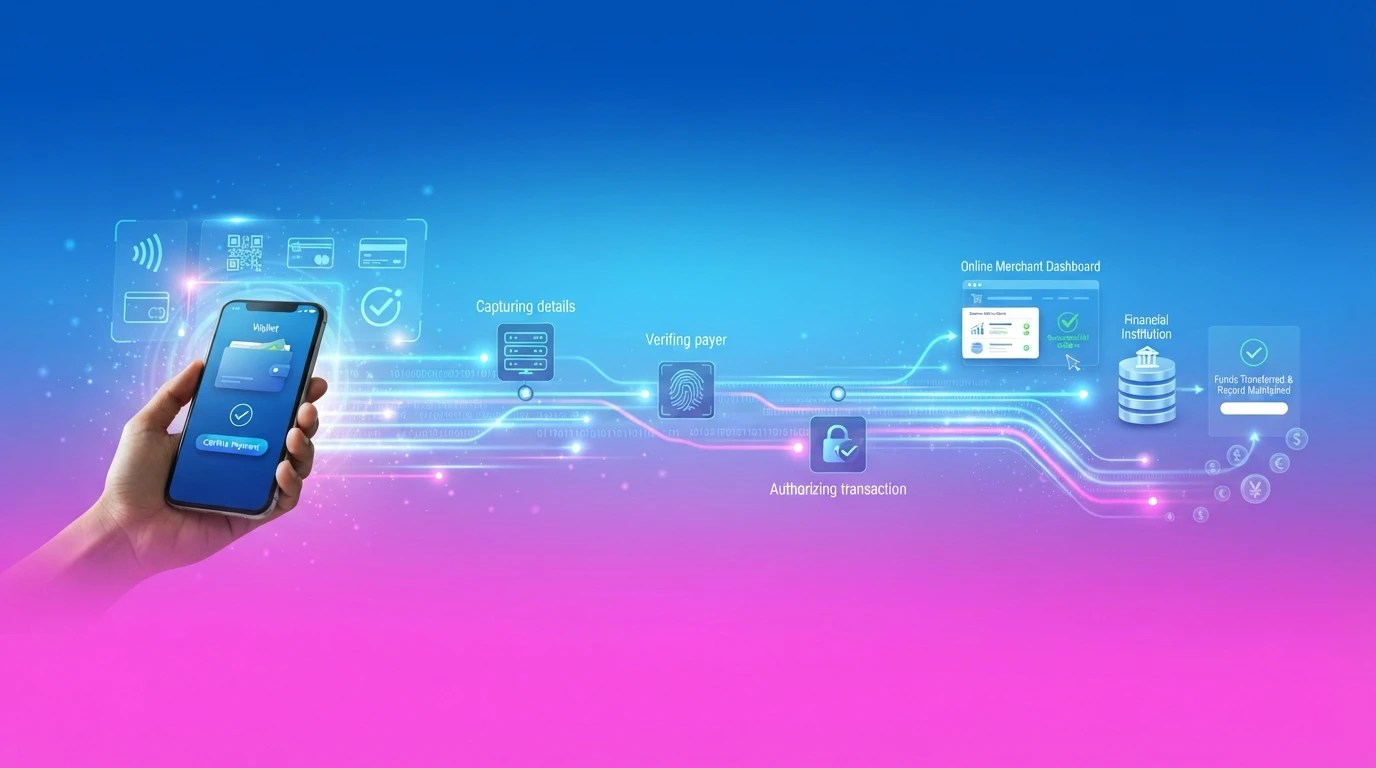
A digital payment services provide the technology and connections needed to transfer money electronically. They link the customer’s chosen payment method with the merchant, bank or financial institution receiving the funds. They support the technology and operational steps required to capture payment details, verify the payer, authorise the transaction, transfer funds, confirm status and maintain an accurate financial record.

Customers expect to pay quickly through familiar methods. Businesses need each transaction to be secure, traceable and connected to orders, invoices, accounts and customer service. A well-designed digital payments solution brings these needs together.

Why do Businesses Need Digital Payment Services and Solutions?

Digital payment solutions help businesses collect revenue across channels, offer customers more choice and reduce the manual effort involved in processing and tracking transactions. They can also support faster fulfilment, clearer financial visibility and expansion into new markets.

How Digital Payments Differ From Traditional Payment Methods?

Cash and paper-based payments usually require physical handling and delayed record updates. Digital payments create machine-readable events that can trigger fulfilment, update balances, send notifications, support fraud checks and feed reconciliation workflows.

Digital Payment Services vs. Traditional Payment Processing

Traditional payment processing mainly focuses on authorisation and settlement. Modern digital payments services extend across checkout, stored credentials, recurring billing, intelligent routing, refunds, analytics, fraud management and integration with the wider business.

Digital Payment Service vs. Digital Payment Software vs. Payment Gateway vs Payment Processor

These terms describe different parts of the payment ecosystem.

Term Primary role
Digital payment service Provides an end-to-end capability for accepting, managing and tracking electronic payments.
Digital payment software Manages payment methods, workflows, status, refunds, reporting and integrations.
Payment gateway Securely passes payment information between the customer-facing channel and processing systems.
Payment processor Routes transaction messages among merchants, banks and networks and supports authorisation and settlement.
Payment service provider May combine gateway access, processing connections, payment methods, risk services, reporting and settlement support.

Digital Payment Service Provider (PSP) vs Payment Gateway

A payment gateway primarily transfers payment information securely between the customer-facing channel and the processor. A payment service provider usually offers a broader set of capabilities, which may include gateway access, payment processing, merchant services, reporting and settlement support.

Who Uses Digital Payment Services?

Digital payment services are used by any organisation that needs to collect, send or manage payments electronically. Businesses and merchants use them to accept payments and manage refunds, while banks and financial institutions rely on them to facilitate secure money movement. E-commerce companies, retailers and D2C brands use digital payments to create smoother checkout experiences across channels.

SaaS and subscription businesses depend on them for recurring billing, while marketplaces and digital platforms use them to manage payments and payouts between multiple parties. Government agencies, educational institutions, healthcare providers, and travel and hospitality businesses also use these services to simplify collections, improve payment visibility and connect transactions with their wider operational systems.


How Does a Digital Payment Work?

A digital payment securely transfers transaction information between the customer, merchant, payment provider and financial institutions. Within seconds, these systems verify the payer, check the availability of funds, assess risk and return an approved or declined response. The transaction is then settled and matched with the relevant order, invoice and financial records.

The Complete Digital Payment Flow

The following flow shows how a digital payment moves from customer initiation to final reconciliation:

Payment initiated → Details encrypted or tokenised → Customer authenticated → Transaction sent to the payment gateway or PSP → Issuing bank authorises or declines the payment → Confirmation returned to the customer and merchant → Funds cleared and settled → Payment matched with the order, invoice and bank records

What Happens After a Customer Clicks “Pay”?

The checkout encrypts or tokenises the relevant data and sends a request to the gateway or payment service provider. The request is validated, assessed for risk and routed through the processor, payment network or bank. The issuer or account provider then returns an approved, declined or pending result.

Payment Authorisation, Authentication and Settlement

Authentication checks whether the payer is legitimate. Authorisation confirms whether the transaction can proceed. Clearing calculates what participating institutions owe, while settlement transfers the funds.

Where Banks, Payment Networks, PSPs and Merchants Fit Into the Process

The merchant initiates the request. The gateway or PSP connects it to the relevant payment rail. Payment networks exchange the transaction messages, while the issuing and acquiring institutions authorise and settle the funds.

What Happens When a Payment is Declined?

The platform should interpret the response, show the customer a clear next step and determine whether to retry, request another method or stop. Soft declines may be recoverable through additional authentication or a well-timed retry. Hard declines generally require customer action or a different method.

What Happens When a Payment is Successful but the Order Fails?

Payment and order systems can fall out of sync because of timeouts, delayed events or application errors. Idempotency controls, webhooks, status verification and compensating actions such as an automatic void or refund help prevent duplicate charges and unresolved cases.

Payment Reconciliation After the Transaction

The business must match the payment with the order or invoice, processor settlement, fees, refunds and bank receipt. This final control confirms that a successful customer payment became correctly recorded revenue.

What Types of Digital Payments Can Businesses Accept?
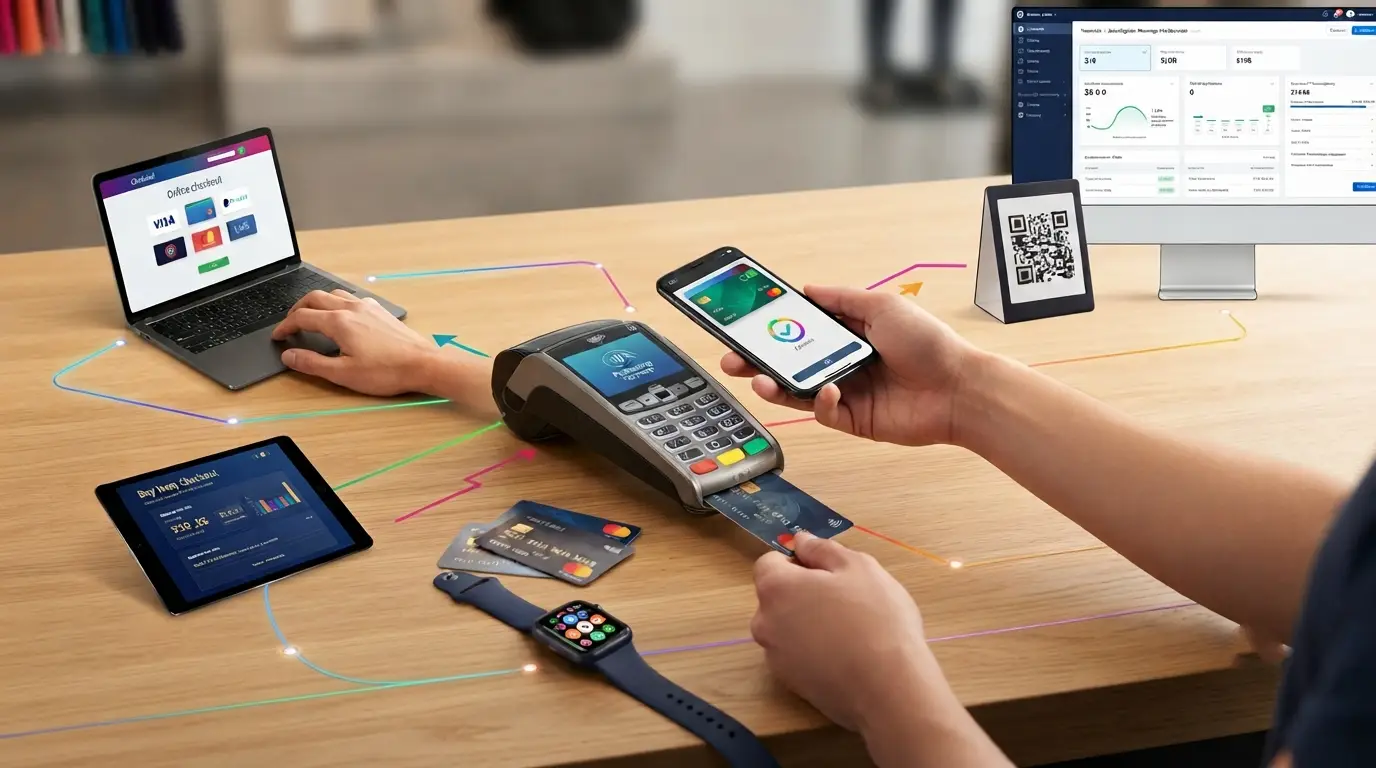
Digital Payments

The right mix depends on customer preference, transaction value, geography, speed, cost and the level of payment certainty required.

Payment type Where it adds value
Credit and debit card payments Familiar payments across online, mobile and in-person channels.
Bank transfers Direct account-based transfers, often suited to invoices and higher-value transactions.
Account-to-account payments Bank-connected payments that move funds directly between accounts.
Real-time payments Rapid funds movement and status confirmation through supported domestic rails.
Digital wallets Faster checkout using stored credentials and device-based authentication.
QR code payments Convenient payments initiated by scanning merchant- or customer-presented codes.
Mobile payments and NFC Contactless payments through phones, cards and wearable devices.
Buy now, pay later Instalment options for eligible customers under provider terms.
Direct debit and ACH payments Account-based collections, recurring bills and domestic transfers.
Recurring and subscription payments Scheduled or usage-based collections for ongoing services.
Payment links Remote collection without a complete checkout integration.
Virtual account payments Identifiable account details that simplify matching funds to customers or invoices.
Cross-border payments Collections and payouts across currencies, banks and jurisdictions.
Cashless point-of-sale payments In-store acceptance connected to sales, inventory, loyalty and accounting.

Online, Mobile and In-Person Digital Payments Services

Payment channels should feel consistent to customers while sharing security, data and operational visibility behind the scenes.

  • Online payment services for websites: Support secure checkout, stored methods and localised payment options for browser-based commerce.
  • Mobile payment services for apps: Bring payment capabilities into mobile journeys, often using biometrics and digital wallets.
  • In-store and point-of-sale payments: Manage card-present, contactless and QR payments in physical locations.
  • Omnichannel payment services: Connect payment methods, customer records, receipts and refunds across digital and physical channels.
  • Embedded payments within business applications: Place payment, payout or financing capabilities directly inside a non-financial product journey.
  • Payment services for marketplaces: Support seller onboarding, split payments, commissions, reserves and payouts.
  • B2B digital payment services: Connect account-based payments with invoices, approvals, remittance data and reconciliation.
  • B2C digital payment services: Create fast and familiar payment journeys that reduce customer effort.


What Does Digital Payment Software Include?

A complete platform combines customer-facing payment journeys with the controls needed to operate them reliably.

Capability What it enables
Payment processing engine Validates transactions and routes them to the appropriate provider or rail.
Payment gateway integration Connects customer channels with external payment acceptance systems.
Merchant account and acquiring integration Supports merchant acceptance, acquiring relationships and settlement.
Payment method management Configures methods by customer, currency, channel, region or transaction type.
Customer and payment data management Maintains permitted customer, consent, token and payment-reference data.
Transaction management Provides a controlled record of payments and related actions.
Payment status tracking Shows whether payments are approved, declined, pending, reversed, refunded or settled.
Refund and cancellation management Supports controlled full, partial and rules-based refunds or voids.
Settlement management Tracks expected funds, fees, timing and settlement outcomes.
Reconciliation module Matches payment, order, settlement and bank records.
Reporting and analytics Measures approval, failure, cost, fraud and settlement performance.
Notification and alert management Informs customers and teams when an event requires attention.
User and role management Restricts sensitive functions according to job responsibility.
API and webhook management Connects business systems and distributes payment events in near real time.

What are the Essential Features to Look for in Digital Payment Services?

A digital payment service should support the payment methods, currencies and regions relevant to the business. It should also provide real-time transaction status, recurring payment management, secure refunds, payment recovery, settlement tracking, customer payment history and reliable reporting.

For growing enterprises, automated reconciliation, multi-merchant support, role-based access, audit trails, APIs and webhooks are equally important. Together, these capabilities reduce manual effort, strengthen operational control and make it easier to introduce new providers, channels and payment experiences as the business evolves.

How do Recurring and Subscription Payments Work?

Recurring payments replace repeated checkout with permission-based collections, but they require careful handling of consent, credentials, failures and cancellations.

Element How it works
One-time vs. recurring payments A one-time payment is individually initiated, while recurring payments follow an agreed schedule or usage rule.
Subscription billing The billing platform calculates the amount due and automatically triggers collection.
Card-on-file payments A reusable token supports future transactions under agreed customer terms.
Mandates and e-mandates Recorded authorisation permits account-based or recurring collections.
Tokenisation Tokens reduce exposure of the underlying payment credentials.
Expired or replaced cards Account-updater or network-token services can help legitimate subscriptions continue.
Failed payment recovery Notifications, self-service updates and targeted retries help recover revenue.
Retry strategies Response codes, timing and customer context determine whether and when to retry.
Cancellations and refunds Clear proration, cancellation and refund rules help prevent disputes.

Payment Security: How Are Digital Payments Protected?

Payment security requires overlapping controls across data, identity, software, infrastructure, transactions and operations.

  • Encryption protects sensitive information while it moves between systems and while it is stored.
  • Tokenisation replaces valuable credentials with limited-use tokens, reducing exposure during mobile and e-commerce transactions.
  • PCI DSS provides baseline technical and operational requirements for protecting payment-account data.
  • 3-D Secure authentication shares transaction and device data with issuers to authenticate cardholders and reduce card-not-present fraud.
  • Multi-factor authentication strengthens access and transaction approval for sensitive activity.
  • Fraud detection and transaction monitoring combine rules, risk models, network intelligence and human review.
  • Device and behavioural risk signals add context such as device history, location and unusual interaction patterns.
  • Address and identity verification compares supplied details with trusted records where appropriate.
  • Velocity and transaction limits restrict unusual payment frequency, value or patterns.
  • Chargeback prevention combines clear billing information, evidence and responsive customer service.
  • Secure API authentication protects system-to-system access through strong credentials and controlled permissions.
  • Data protection in transit and at rest requires encryption, access management, monitoring and sound key management.

Why Businesses Should Avoid Storing Sensitive Card Data Directly?

Direct storage expands the systems, people and processes exposed to payment data, increasing risk and compliance scope. Tokenisation and provider-hosted capture can reduce that exposure, although organisations must still validate their PCI DSS responsibilities.


Experion can help enterprises engineer security and compliance into payment architecture, integrations, workflows and observability from the beginning rather than adding controls after the platform is built.

What are the Benefits of Digital Payment Services for Consumers?

Customers experience the value of digital payments through convenience, choice, clearer records and stronger protections.

  1. Convenience and speed: Customers can pay through familiar devices and methods without handling cash.
  2. Cashback, rewards and discounts: Eligible payment methods can connect purchases with loyalty benefits and offers.
  3. Better expense tracking: Digital records help customers review purchases, subscriptions, refunds and account activity.
  4. Enhanced security compared with cash: Authentication, tokenisation, alerts and dispute processes provide protections that physical cash cannot offer.


Digital Payment Fraud and Common Security Risks

Fraud controls must protect customers and revenue without making legitimate payments unnecessarily difficult.

Risk What it involves
Payment fraud Unauthorised or deceptive activity intended to obtain funds, goods or services.
Card-not-present fraud Misuse of card credentials when the physical card is not inspected.
Account takeover An attacker gains control of a customer or merchant account.
Credential theft Card, bank, wallet or authentication details are captured and misused.
Phishing and fake requests Customers or employees are directed towards fraudulent payment journeys.
Duplicate transactions Retries or integration errors process the same intended payment more than once.
Friendly fraud and chargebacks A legitimate cardholder disputes a purchase through confusion, dissatisfaction or deliberate misuse.
Payment API abuse Attackers exploit weak authentication, exposed endpoints or automated credential testing.

How Businesses Can Reduce Payment Fraud?

Businesses should combine secure development, tokenisation, strong authentication, transaction monitoring, device and behavioural signals, velocity rules and human review for high-risk cases. Fraud losses should be measured alongside approval rates and false declines so stronger controls do not drive away genuine customers.

Common Reasons for Payment Failure

A failed payment is both a technical event and a customer moment, so recovery must be clear and proportionate.

Common causes include insufficient funds, bank or network declines, authentication failure, expired credentials, API errors, timeouts and connectivity issues. Soft declines may be recoverable, while hard declines usually require customer action.

Smart retries use response codes, timing and transaction context rather than repeatedly submitting every failure. Alternative routing or another payment method may help when a provider is unavailable. Clear notifications also help customers and service teams understand what to do next.

What Happens When a Digital Payment Fails?

The platform should preserve a definitive transaction state, prevent duplicate fulfilment, record the failure and offer an appropriate recovery option. If the outcome is uncertain, the system should verify the status before asking the customer to pay again.

Payment Reconciliation: Connecting Payments With Business Records

Payment reconciliation is the process of matching customer payments with orders, invoices, provider settlements and bank records. It helps businesses confirm that every transaction has been received and recorded correctly while identifying missing, duplicated or mismatched payments. Reconciliation verifies that what customers paid, what providers processed, what banks settled and what the business recorded all agree.

Why Manual Reconciliation Becomes Difficult at Scale

Different identifiers, settlement cycles, currencies and fee structures make matching increasingly difficult. Refunds, chargebacks, partial payments, reversals and timing differences create further exceptions.

A well-designed reconciliation workflow must support:

  1. Matching payments with orders and invoices
  2. Matching settlements with bank statements
  3. Handling partial payments
  4. Handling refunds and reversals
  5. Identifying unmatched transactions
  6. Automating matching and exception workflows

Experion proof in practice: Experion has applied AI-based reconciliation and financial process automation to an environment processing more than 170,000 transactions a day, improving payment accuracy, reducing discrepancies and helping teams focus on exceptions that require human judgement. Read more

How do Digital Payment Services Integrate with Business Systems?

Integration turns payment status into coordinated action across the organisation.

Integration Business value
Payment APIs Embed initiation, status and refund functions into business workflows.
Payment gateways Connect customer-facing channels with payment providers.
REST APIs Provide standardised access to payment-processing capabilities.
Webhooks Distribute real-time status, settlement, refund and dispute updates.
E-commerce platforms Connect payments with carts, orders, inventory, fulfilment and returns.
ERP systems Link receivables, fees, settlements and ledger processes.
CRM systems Give authorised service teams relevant payment context.
Accounting software Update invoices, fees, deposits and reconciliation records.
Billing platforms Coordinate plans, invoices, collections, retries and entitlements.
POS systems Connect in-store payments with receipts, loyalty and inventory.
Banking systems Support account validation, transfers, statements and settlement.
Customer portals and apps Enable self-service payments, receipts, refunds and status tracking.

REST APIs embed payment functions into these systems, while webhooks distribute asynchronous events such as settlement, refund, or dispute updates. Reliable integrations also need consistent transaction identifiers, idempotency, authentication, monitoring, and retry controls.

Experion’s payment engineering experience includes a global hub integrating 40+ banks, 10+ PSPs and acquirers across 80 countries, creating centralised visibility across a highly distributed payment landscape.

Payment Architecture for Modern Businesses

Payment architecture provides the technical foundation connecting customer channels, payment services and internal business systems.

A modern payment architecture connects websites, mobile applications and point-of-sale systems with gateways, processors, banks and payment networks. Behind the transaction, it must also exchange accurate information with order management, billing, finance, ERP and customer service systems.

As payment needs grow, reusable services for tokenisation, payment status, refunds, reconciliation and reporting can reduce duplicated integrations across channels. APIs and event-driven communication help these services exchange information without tightly coupling every business system to a specific payment provider.

A well-designed architecture should make it easier to:

  • Add payment methods, channels and markets.
  • Protect sensitive payment data.
  • Maintain consistent transaction records.
  • Scale during periods of high demand.
  • Isolate failures before they affect the wider payment journey.
  • Connect payments with orders, invoices and financial records.

Cloud and microservices can support scalability and faster change, but they do not guarantee resilience on their own. Security, observability, data consistency, recovery and clear ownership must be designed across the complete payment lifecycle.

Payment Orchestration for Businesses Using Multiple Payment Providers

While architecture defines how the payment ecosystem is built, orchestration determines how each transaction moves through it.

Payment orchestration provides a common layer between customer channels and multiple gateways, processors, acquirers or payment methods. It allows a business to manage routing rules, provider availability and transaction outcomes without embedding provider-specific logic into every channel.

Why Businesses Use Multiple Payment Providers?

Businesses may use several providers to expand geographic coverage, support local payment methods, meet regulatory requirements, negotiate costs and reduce dependence on a single provider. The operational challenge is managing these connections without creating fragmented reporting, inconsistent payment states or duplicated workflows.

Intelligent Payment Routing

Intelligent routing selects an appropriate provider or payment route based on factors such as location, currency, payment method, transaction value, provider availability and past performance. Routing decisions must remain transparent, auditable and aligned with regulatory and commercial requirements.

  • Provider failover: Redirects eligible transactions to a backup provider when the primary service is unavailable.
  • Local payment method routing: Connects customers with locally preferred payment methods and providers.
  • Cross-border payment routing: Selects suitable routes based on currency, geography and regulatory requirements.
  • Transaction optimisation: Uses payment context and provider performance to improve approval rates and control costs.
  • Centralised reporting across providers: Brings transaction, settlement and exception data into one operational view.

The goal is not simply to add more providers. It is to give customers a dependable payment experience while giving business teams greater control over what happens behind the scenes.

Digital Payment Services for Different Business Models

Every business accepts payments differently. The right digital payment solution should reflect how customers buy, how revenue is collected and how transactions connect with wider operational systems.

Business model What the payment solution needs to support
E-commerce businesses Fast checkout, local payment methods, fraud controls, refunds and reliable order confirmation.
SaaS companies Usage-based or recurring billing, plan changes, invoicing and revenue visibility.
Subscription businesses Credential management, automated renewals, failed-payment recovery and clear cancellations.
Marketplaces Seller onboarding, split payments, commissions, reserves, refunds and multi-party payouts.
Retail businesses Connected in-store, online and mobile payments with loyalty, inventory and returns integration.
Banks and financial institutions Secure payment processing, account services, regulatory controls, clearing and settlement.
Insurance companies Premium collections, renewals, refunds and claims payouts connected with policy systems.
Healthcare organisations Patient payments, billing, refunds and payment visibility across care and administrative systems.
Education and EdTech providers Tuition fees, instalments, subscriptions, scholarships and student refunds.
Travel and hospitality businesses Deposits, cards on file, multi-currency payments, cancellations and partner settlements.
Logistics and transportation companies Invoice collections, carrier payments, cross-border transactions and receivables matching.
Professional services firms Retainers, milestone payments, recurring fees and invoice-based collections.
Government and public services Accessible payment channels, strong auditability, secure collections and dependable reconciliation.

The technology may be similar, but the payment journey should never be treated as one-size-fits-all. A solution that reflects the realities of the business is easier for customers to use and easier for internal teams to manage.

Digital Payment Services for B2B Transactions

B2B payments involve more than transferring funds. They must also account for invoices, approval levels, payment terms, remittance details and reconciliation across finance systems.

Area How digital payment services help
B2B payment challenges Reduce delays caused by manual approvals, fragmented systems and missing payment information.
Invoice-based payments Connect each payment with the correct invoice, customer and outstanding balance.
Account-to-account payments Move funds directly between bank accounts, supporting efficient higher-value transactions.
Recurring business collections Automate collections for contracted services, memberships and scheduled payments.
Automated receivables Match incoming funds with open invoices and update balances with less manual effort.
Payment approval workflows Apply approval limits, role-based controls and audit trails before payments are released.
Bulk payments Process multiple approved payments efficiently while maintaining individual transaction records.
Vendor and supplier payments Connect approved obligations with payment execution and remittance information.
Payment reconciliation for finance teams Match invoices, payment records, bank statements, fees and adjustments.
ERP-connected B2B payments Keep payment activity and accounting records synchronised across the transaction lifecycle.

By connecting payments with invoices, approvals and financial records, businesses can reduce administrative effort, improve cash visibility and give finance teams greater control over every transaction.

What Does a Digital Payment Service Cost?

The real cost combines provider pricing with the internal effort, risk, and technology required to operate the service. Businesses should compare transaction, gateway, processing, currency conversion, settlement, chargeback, refund, monthly, and platform fees. They should also consider integration, migration, security, testing, reporting, and support costs.

Potentially overlooked costs include foreign-exchange markups, reserves, payout delays, data-access charges, non-refundable processing fees, token portability, PCI responsibilities, and the cost of leaving a provider. Higher volume may improve negotiated pricing, but it also magnifies small inefficiencies in declines, fraud, and reconciliation.

How to Choose a Digital Payment Service Provider?

The right provider should fit the business being built, not only the payment methods needed today.

Evaluate geographic and method coverage, approval performance, settlement timing, fraud controls, PCI support, availability, APIs, webhooks, reconciliation data, reporting, service responsiveness, pricing transparency, token portability, and exit options.

Test partial refunds, delayed events, disputes, uncertain transaction states, downtime, volume spikes, and reconciliation exceptions before committing. The best provider is one that performs reliably and gives teams enough data and control to resolve problems.

Custom Digital Payment Software vs Off-the-shelf Software?

The choice depends on whether payments are a standard support function or a differentiated business capability.

Consideration Off-the-shelf software Custom digital payment software
Best fit Standard journeys and rapid launch Complex workflows, multiple providers, or differentiated experiences
Time to market Usually faster Requires discovery, engineering, testing, and rollout
Flexibility Defined by the provider’s roadmap Designed around the business model and target architecture
Control Greater provider dependency Greater control, with responsibility for security and maintenance
Integration Works well with supported systems Can connect specialised, legacy, or industry-specific workflows

A hybrid model is often practical. Businesses can use regulated providers and proven rails for money movement while engineering the orchestration, experience, integration, and intelligence layers that differentiate them.

What are the Common Digital Payment Implementation Challenges?

Most problems appear at the boundaries between providers, channels, records, regulations, and operational ownership.

  • Multiple providers: APIs, data models, status codes, and settlement files must be normalised.
  • Failures and declines: Recovery requires reason-aware actions and clear customer communication.
  • Fraud and chargebacks: Controls must reduce loss without damaging approval rates or customer experience.
  • Compliance: PCI DSS, privacy, sanctions, authentication, licensing, and local rules must be mapped to the operating model.
  • Reconciliation: Identifiers, fees, refunds, and settlement timing often differ across systems.
  • Cross-border payments: Currency, correspondent paths, regulation, data, cost, and settlement speed vary by market. The BIS 2025 monitoring update confirms that improving cross-border payments remains a global priority.
  • Legacy integration: Older cores may rely on files, batches, and inflexible data structures.
  • Peak demand: Capacity, provider limits, queues, and downstream systems must be tested together.
  • Provider downtime: Resilience requires status verification, safe retry, failover, and customer communication.
  • Fragmented visibility: A common transaction identity and observability model are needed from initiation through settlement.

Digital Payment Services for Enterprises

Enterprise payments require a connected operating model across markets, brands, legal entities, channels, providers, and finance systems.

Instead of adding gateways one project at a time, enterprises can establish shared services for provider integration, token handling, routing, security, refunds, reconciliation, and reporting. This creates reusable governance while allowing products and regions to deliver locally relevant experiences.

Experion brings financial-services domain knowledge, product engineering, cloud modernisation, data engineering, APIs, experience design, and AI-assisted operations together to modernize this foundation. Its global payment work across 40+ banks and 80 countries demonstrates the value of designing for integration and visibility at scale.

Future of Online Payment Services
Digital Payment Services Future

Digital payments will become more embedded and automated, while expectations for identity, transparency, and control will continue to rise.

  • AI-powered fraud detection and operations will identify complex patterns, classify reconciliation exceptions, and prioritise cases, but will require governed data and human oversight.
  • Intelligent routing will use performance and transaction context to select suitable providers within approved business and risk rules.
  • Real-time, embedded, and account-to-account payments will make payments less visible as separate steps while increasing expectations for immediate status and continuous operations.
  • Open banking and network tokenization will support bank-connected journeys, reduce credential exposure, and improve payment continuity.
  • Autonomous and agentic payments may let software agents initiate approved actions, but limits, consent, traceability, and exception controls must come first.
  • Cross-border modernization and unified experiences will target better speed, cost, transparency, and continuity across channels.

Experion is well positioned to help enterprises translate these shifts into secure, scalable products by combining payment modernization with API-led integration, cloud engineering, data platforms, experience design, and AI-assisted reconciliation.

Turn Payment Complexity Into Business Confidence

The right digital payment strategy is not simply about processing transactions faster. It is about reducing friction for customers, giving finance teams greater control and enabling the business to enter new markets without adding operational complexity.
Bank Reconciliation Software

As businesses scale, finance teams handle more transactions than ever. Manual reconciliation, which once worked, is now a bottleneck to efficiency.

Modern automated bank reconciliation software helps finance teams close faster, improve accuracy, and stay audit-ready. It gives finance leaders real-time cash visibility, turning a once-tedious month-end task into a controlled, ongoing process.


Key Takeaways

  • Bank reconciliation software automatically matches bank statement transactions against internal ledger entries, replacing manual spreadsheet work.
  • Effective automated bank reconciliation software follows Connect → Match → Detect → Review → Reconcile → Report workflow, automating routine matches while keeping exceptions in human hands.
  • AI and Machine learning are now being used to improve match rates, learn from past decisions, and flag anomalies that rule-based systems often miss.
  • The must-have features include multi-bank support, rule-based and AI matching, ERP/accounting integrations, bank-level security, and a complete audit trail.
  • Bank reconciliation solutions usually range from built-in accounting features to dedicated applications, enterprise platforms, and property-management-specific tools. The best option depends on transaction volume, entity structure, and compliance needs.
  • Property managers and real estate firms benefit especially from automatic reconciliation across rent receipts, owner distributions, and trust/security deposit accounts.


What is Bank Reconciliation Software?

Bank Reconciliation

Bank account reconciliation software automatically compares transactions on your bank statements with entries in your internal accounting records. It then ascertains that the two sets of records match. When they don’t, it flags the differences so your team can investigate and resolve them.

Traditional reconciliation usually refers to downloading bank statements, exporting ledger data into a spreadsheet, and ticking off matching lines one at a time. Bank statement reconciliation software automates this process and compares statement data with the company’s accounting records. It can thereby flag items that need review.


What Makes a Bank Reconciliation Solution Effective?

Effective bank reconciliation solutions follow a clear, repeatable workflow:

Connect ,Match, Detect ,Review ,Reconcile ,Report

  1. Connect: Pull in bank accounts, credit cards, payment gateways, and the general ledger—via bank feeds, APIs, or plain file imports.
  2. Match: Automatically pair bank transactions with ledger entries using rules or a trained model.
  3. Detect: Surface unmatched items, duplicates, amount mismatches, and unusual activity.
  4. Review: Send exceptions to the right person with context, notes, and supporting documents.
  5. Reconcile: Post adjustments, approve matches, and lock the reconciled period.
  6. Report: Produce reconciliation summaries, variance reports, and audit-ready documentation.


How Automated Bank Reconciliation Software Works?

Data import (Bank feeds, CSV, API/Open banking)

The process starts with data. Most software for bank reconciliation supports several ways to import it:

  • Direct bank feeds: A secure, automated daily sync of transactions from connected banks.
  • CSV, OFX, QFX, or BAI2 files: Bank transaction files that you upload manually or import automatically when a direct bank connection isn’t available.
  • API and open banking connections: Real-time, permission-based access to account data through regulated open banking frameworks, such as PSD2 in Europe and similar standards elsewhere.
  • ERP and accounting system sync: It pulls ledger entries, invoices, and payments from your accounting platform.

The more automated and consistent the data import, the more reliable every step after it becomes.

Automated Transaction Matching Rules

Matching is central to automated bank reconciliation software. Common matching approaches include:

  • One-to-many and many-to-one matching: One bank transaction matches one ledger entry.
  • Fuzzy matching: It tolerates small differences in dates, descriptions, or reference formats.
  • Custom rules: For example, “Always categorize transactions from Vendor X as Utilities” or “Match amounts within a $0.50 tolerance for FX rounding.”
  • AI-assisted suggestions: The system learns from past user decisions and proposes likely matches over time.

Exception Handling & Flagging discrepancies

Some transactions won’t match automatically. Good banking reconciliation software handles these exceptions in a structured way:

  • It flags unmatched, partially matched, or duplicate transactions.
  • It assigns exceptions to specific team members, with due dates.
  • It lets users attach notes, receipts, and supporting documents.
  • It escalates unresolved items past a set age or value threshold.
  • It records who resolved each exception and how.

Reporting and Audit Trail

Once reconciliation is complete, the software produces:

  • Reconciliation summaries by account, entity, or period.
  • Aged reports of outstanding items
  • Variance and adjustment reports.
  • A complete, time-stamped audit trail of every action taken.

Auditors, controllers, and CFOs rely on this documentation to trust the numbers.


Still reconciling bank accounts in spreadsheets?
Talk to Experion’s fintech engineering team about building or integrating automated bank reconciliation into your finance stack


What are the Key Benefits of Bank Reconciliation Software?

Time savings vs. Manual Reconciliation

Manual reconciliation can take days every month, especially across several accounts. Automated matching handles high-volume, routine transactions. ,So accountants can focus on exceptions. As a result, for many teams, month-end reconciliation shrinks from days to hours, and continuous daily reconciliation becomes realistic.

Reduced Human Error

Transposed digits, missed entries, copy-paste mistakes, and formula errors are common in spreadsheets. Bank reconciliation accounting software applies the same rules consistently every time, which greatly reduces the risk of manual error.

Fraud and Discrepancy Detection

Because every transaction is compared against the books, unauthorized payments, duplicate vendor payments, altered checks, and unexpected withdrawals surface quickly. Detecting them within days instead of weeks limits financial exposure and supports stronger internal controls.

Real-time cash visibility

With daily bank feeds and continuous matching, finance leaders always know their actual cash position. This leads to better decisions on payables, investments, borrowing, and cash forecasting.

Audit-readiness and compliance

Clear audit trails, documented approvals, and consistent reconciliation records make internal and external audits smoother. The software also supports compliance with internal control requirements. This includes SOX for publicly listed companies in the US and industry-specific regulations.

Streamline credit card transaction management

Corporate cards can generate hundreds of small transactions every month. Bank rec software can import card statements, match charges to receipts and expense reports, and flag missing documentation. This makes card reconciliation as structured as bank reconciliation.

Benefits of automatic bank reconciliation in property management/real estate software

Automatic bank reconciliation in property software is especially valuable because real estate accounting involves many transaction types across many accounts. Property managers, landlords, and real estate firms have to reconcile:

  • Rent receipts: Hundreds or thousands of tenant payments often arrive through Automated Clearing Houses (ACH), cards, checks, and online portals.
  • Maintenance expenses: Vendor payments that are often tied to specific units or properties.
  • Owner distributions: Accurate payouts to property owners, based on reconciled income and expenses.
  • Security deposits: Often held in separate trust or escrow accounts, and subject to strict local regulations.
  • Operating accounts: Day-to-day property-level cash.

In many jurisdictions, mishandling trust accounts or security deposits can lead to regulatory penalties. Automatic reconciliation in property management software helps firms keep each property’s books accurate, separate trust funds correctly, and produce reliable monthly owner statements.


What are the Must-Have Features to Look For in a Bank Reconciliation Software?

Multi-bank/Multi-account support

The software should be able to connect to all of your banks and accounts, including checking, savings, credit cards, payment processors, and trust accounts, and reconcile them from one dashboard.

AI/Rule-based auto-matching

Identify configurable matching rules combined with intelligent suggestions that improve over time. The higher the auto-match rate, the less manual work remains.

Integration with Accounting/ERP systems

Seamless two-way integration with platforms such as QuickBooks, Xero, NetSuite, Sage, Microsoft Dynamics, or SAP removes duplicate data entry and keeps the ledger in sync.

Bank-level security & encryption

Financial data needs strong protection. Key safeguards include:

  • Encryption in transit (TLS) and at rest (AES-256).
  • Multi-factor authentication. (MFA)
  • Role-based access controls.
  • Independent security attestations, such as SOC 2 Type II or ISO 27001.

Scalability for multiple entities/currencies

Growing organizations need multi-entity, multi-currency support, including FX handling and intercompany reconciliation, so the software doesn’t need replacing after a year or two.

Reporting & Audit Trail

Customizable reports, exportable reconciliation packages, and immutable activity logs are essential for controllers and auditors.

Exception Management

Structured workflows for assigning, commenting on, escalating, and resolving unmatched items keep exceptions from quietly piling up.


Experion’s engineering teams can design reconciliation modules with these capabilities built in, from secure bank API integrations to configurable matching engines and audit-ready reporting, tailored to each client’s accounting stack.


The AI Advantage: How Machine Learning Can Transform Bank Reconciliations?

AI in Bank Reconciliation Software

Rule-based matching handles predictable, repetitive transactions well, but it struggles with the exceptions. This includes slightly reworded descriptions, split payments, or transactions that don’t fit any predefined pattern. This is where machine learning changes the picture.

AI-powered bank reconciliation software learns from every match a user confirms or corrects. Over time, it starts recognizing patterns that static rules can’t capture. Examples include:

  • A vendor whose name is formatted differently across statements.
  • A recurring payment whose amount varies slightly each month.

Instead of a finance team writing and maintaining hundreds of matching rules, the system adapts automatically and suggests matches with a confidence score.

Machine learning also strengthens fraud and anomaly detection. By learning what “normal” transaction behavior looks like for a given account, AI models can flag outliers, such as an unusual payee, an out-of-pattern amount, or a duplicate payment, well before a human reviewer would notice them manually. Combined with natural language processing to parse free-text bank descriptions, AI reduces the volume of manual exceptions and lets finance teams focus on genuinely ambiguous cases rather than routine matching.

The result is a reconciliation process that gets faster and more accurate the longer it runs, rather than staying static year after year.


Bank Reconciliation Software vs. General Accounting Software

Reconciliation capability comes in several forms. Understanding the differences helps you find the right fit:

  • A dedicated bank reconciliation application: A standalone tool focuses entirely on reconciliation. It offers advanced matching, exception workflows, and reporting, and can integrate with your existing accounting system.
  • A feature within accounting software: Most accounting platforms include basic bank feeds and matching. This works well for small businesses with simple needs, but it may lack advanced rules or deep audit controls.
  • A module within an ERP: Enterprise ERPs offer reconciliation modules tightly linked to the general ledger. They are powerful but often complex to configure.
  • A capability within property management software: Reconciliation built around properties, units, tenants, owners, and trust accounts.
  • A broader financial close or reconciliation platform: These handle bank reconciliation alongside balance sheet, intercompany, and account reconciliations as part of an end-to-end financial close process.

For many businesses, the best bank reconciliation tools in accounting software are enough to begin with. As transaction volumes, entities, and compliance requirements grow, dedicated or enterprise-grade solutions become more valuable.


What are the Different Types of Bank Reconciliation Solutions?

  • Built-in accounting software reconciliation: Included in most cloud accounting platforms. It is cost-effective and simple and best for small businesses.
  • Dedicated bank rec software: Purpose-built tools with stronger matching logic and exception workflows, suited to mid-sized companies and accounting firms.
  • Enterprise reconciliation platforms: High-volume, multi-entity, multi-currency solutions with advanced controls, used by large organizations and shared service centers.
  • Property management reconciliation tools: Built specifically for rent, deposits, owner distributions, and trust accounting.
  • Bank-side reconciliation software: Reconciliation software for banks and financial institutions, used to reconcile nostro/vostro accounts, ATM and card settlements, payment networks, and interbank transfers at very high volumes.


Who Should Use Bank Reconciliation Software?

  • Small businesses: Save hours each month and avoid costly bookkeeping errors.
  • Growing companies: Scale reconciliation as accounts, transactions, and team size grow.
  • Accounting firms: Reconcile many client accounts efficiently from one platform.
  • Property management firms: Manage rent, deposits, and trust accounts accurately across portfolios.
  • Enterprises: Handle multiple entities, currencies, and banking relationships with strong controls.
  • Banks and financial institutions: Reconcile internal accounts, settlements, and payment flows at scale using specialized bank reconciliation system software.


Bank Reconciliation App vs. Bank Reconciliation Software

The terms are often used interchangeably, but there is a practical difference.

Bank reconciliation software usually means a full web-based or desktop platform built for detailed reconciliation work.

On the other hand, a bank reconciliation app usually means a mobile application, or a mobile companion to that platform, built for quick access and lightweight actions.

When a Bank Reconciliation App May Be Useful?

  • Reviewing reconciliation status: Check which accounts are reconciled and which are still pending.
  • Approving exceptions: Managers can approve adjustments or matches from anywhere.
  • Monitoring accounts on the go: Receive alerts for large, unusual, or unmatched transactions.

When Full Bank Reconciliation Software May Be More Appropriate?

  • High transaction volumes: Thousands of monthly transactions need a full workspace.
  • Complex matching rules: Configuring rules and tolerances requires a desktop interface.
  • Multiple entities or accounts: Consolidated views are easier to manage on larger screens.
  • Detailed reporting: Building and exporting audit packages.
  • Accounting integrations: Managing ERP and ledger sync settings.
  • Audit and compliance requirements: Full audit trails and control documentation.

In practice, the strongest setups combine both: A full bank reconciliation application for the core work, and mobile access for oversight and approvals.


Bank Reconciliation Software Use Cases

Cover different business scenarios:

  • Small and mid-sized businesses: Automate reconciliation of operating accounts, credit cards, and payment processors such as Stripe or PayPal.
  • Enterprises with multiple bank accounts: Centralize reconciliation across dozens or hundreds of accounts and banking partners.
  • Multi-entity organizations: Reconcile subsidiaries separately while keeping a consolidated view and handling intercompany transfers.
  • Property management companies: Match rent receipts, vendor payments, owner distributions, and security deposit accounts property by property.
  • Retail and ecommerce businesses: Reconcile daily payment gateway payouts, which net out fees, refunds, and chargebacks, against individual orders.
  • Accounting and finance teams: Speed up month-end close and reduce reliance on spreadsheets.
  • Organizations with high transaction volumes: Use automation to process volumes that manual review simply can’t handle.


Need reconciliation built into your ERP, accounting platform, or property management system?
Experion designs and develops secure, scalable fintech solutions that fit your workflows.
Talk to Our Experts


How to Choose the Right Bank Reconciliation Software?

No single bank reconciliation software is best for everyone. The best account reconciliation software for your organization depends on your size, systems, and requirements. Evaluate options against these factors.

Business size & transaction volume

A business with a few hundred monthly transactions has very different needs from one processing tens of thousands. Match the solution’s automation depth and performance to your current and projected volumes.

Integration needs (accounting stack, banks)

Confirm native integrations with your accounting system or ERP, and check whether each bank offers a direct feed or API. Weak integrations bring back the manual work you are trying to remove.

Budget considerations

Weigh subscription costs against the hours saved, fewer errors, and faster close. Include implementation, training, and integration costs, not just license fees.

Industry-specific requirements

Property management, healthcare, ecommerce, nonprofits, and financial services each have unique reconciliation needs, such as trust accounting, payer remittances, gateway payouts, fund accounting, and settlement reconciliation.

Reporting and compliance requirements

If you face audits, SOX requirements, or industry regulations, prioritize immutable audit trails, approval workflows, and exportable documentation.

Consider Security and Access Controls

Review encryption standards, security certifications, MFA, role-based permissions, and data residency options. Make sure users can only see and act on the accounts they are responsible for.

Checklist/decision framework

Before shortlisting vendors, here is a checklist or decision framework:

  • Connects to all your banks, cards, and payment processors.
  • Integrates two-way with your accounting or ERP system.
  • Supports configurable rules and intelligent auto-matching.
  • Handles one-to-many and many-to-one matches.
  • Offers structured exception management workflows.
  • Supports multiple entities and currencies, if needed.
  • Provides an immutable audit trail.
  • Meets your security standards (encryption, MFA, SOC 2/ISO 27001).
  • Includes role-based access and approval controls.
  • Offers the reports your auditors and leadership need.
  • Fits your budget, including implementation costs.
  • Offers a free trial or demo using your own data.


Conclusion

Bank reconciliation is one of the most fundamental finance functions, but doing it manually can be time-consuming. The right bank reconciliation software helps finance teams close faster, improve accuracy, strengthen internal controls, and trust their cash balances. Depending on their needs, teams may choose a built-in accounting feature, dedicated reconciliation software, an enterprise platform, or a custom-built solution.

Whatever the approach, the objective remains the same: automate routine work, easily identify and resolve exceptions, and keep your finance team in control of every decision.


Ready to modernize your reconciliation process?
Partner with Experion to build secure, automated reconciliation capabilities into your financial software
Contact Us Today

Jobs-to-be-done (JTBD) Framework

Introduction

When we talk about a product or service, we often think about satisfying a user or customer through the quality of its performance. Manufacturers and solution providers invest significant effort in adding features and capabilities that they believe will enhance the product or service and, ultimately, create value for the customer. Features and offerings are designed to address Basic Needs, defined by the Kano model, with the underlying thought that no potential “Delighters” should be left behind before the product reaches the end user.

However, management theories have evolved to emphasize that customer interests matter more than the offering itself. Understanding the customer before designing the solution has become increasingly important. Discovery workshops, market research, customer interviews, journey mapping, persona development, competitive analysis, usability testing, and user interaction statistics have become common starting points for improving customer satisfaction.

Yet, even with these techniques in place, many products and services still fail to achieve higher levels of customer satisfaction.

At this point, management thinkers began to recognize that conventional models did not always reveal the full picture of customer needs. Understanding the customer requires looking beyond the most visible requirements and exploring the deeper motivations, circumstances, and outcomes that shape their decisions. It is much like searching for buried treasure: the first discovery may be valuable, but continued exploration can uncover insights that are even more meaningful.

This is where the Jobs-to-Be-Done Framework, commonly abbreviated as JTBD, becomes relevant. Popularized through the work of Clayton Christensen, Tony Ulwick, and other management thinkers, the JTBD framework has emerged as a useful approach to understanding customers more deeply and evaluating the needs and objectives they seek to address through a product or service.

Let us explore what this framework means, how it can help address the underlying reasons why even well-designed products and services may fail to deliver the expected value, and how its principles shape Experion’s approach to creating more outcome-focused solutions for its customers.


Jobs-to-be-Done Framework (JTBD) Defined


JTBD is a framework for evaluating and understanding the fundamental need that a customer is trying to address through a product or service. It can be viewed as going beyond the conventional finish line of understanding customer requirements and exploring the real objective behind those requirements.

Understanding the purpose that motivates a customer to buy a product or use a service provides deeper insight into the objective behind the requirement. This, in turn, helps the provider address the underlying need more effectively and design a solution around what the customer is ultimately trying to accomplish.


The Classic Example of a Restaurant Chain

The well-known example used to explain the JTBD Framework is the milkshake example, popularized through the work of Clayton Christensen. A few years ago, a fast-food restaurant chain was trying to improve the sales of its milkshakes. The company explored multiple solutions, including increasing the size of the milkshake, introducing additional flavors, and creating meal combinations that could make the shakes more appealing to children. However, these efforts did not produce the expected improvement in sales.

Clayton Christensen and his team were brought in to help address the business challenge. They visited the restaurant to observe how it operated and made an interesting discovery: a significant proportion of milkshakes were purchased by adults rather than children, and many of these purchases happened during the early hours of the day. Customers often bought only the milkshake and then drove away rather than dining at the restaurant.

The key observations made by Christensen and his team were interesting because they differed from the assumptions underlying the restaurant’s existing approach:

  • The restaurant targeted children as its primary consumers, but sales data suggested that adults consumed a significant proportion of its milkshakes.
  • Many milkshake buyers did not dine at the restaurant, indicating that the milkshake was serving a purpose beyond conventional dining or meal consumption.

The team then interviewed some of the adult consumers to understand why a milkshake purchased early in the morning was valuable to them. In other words, they were trying to explore the additional “job” that the milkshake was performing beyond the role of conventional food.

These consumers explained that they wanted something that would keep them satisfied until their next break and could also be consumed with one hand while driving with the other. The milkshake helped them save time, stay full, and conveniently commute to work at the same time.

This example clearly illustrates the JTBD Framework. The milkshake was performing an additional job that conventional alternatives such as bananas, donuts, and other breakfast options did not address in the same way. The example demonstrates that a product or service can create value when it performs a job that customers are trying to accomplish in a way that meaningfully addresses their circumstances and needs.


What Does JTBD Say?

The JTBD Framework explains that people choose products or services because they want to accomplish a particular job. Solution providers therefore need to reevaluate their understanding of customer requirements through this lens. Focusing only on the stated or primary requirements may not always result in the most effective solution for users.

Customizing offerings around the core objectives and requirements of a target segment can be more effective than trying to adopt an agnostic, one-size-fits-all approach. When a solution helps users accomplish a job, whether simple or complex, they recognize value in it. This can increase adoption of the solution and, consequently, contribute to growth in the customer base.

The example of the restaurant chain clearly illustrates that its initial attempts to understand its customers did not fully address the underlying need. Efforts to create a better or more appealing product did not result in the expected improvement in sales. This can be viewed as a customer-understanding problem leading to a solution-design problem.

When the restaurant began to understand and address the job that consumers were trying to get done, the opportunity became clearer. Bringing the JTBD perspective provided a deeper understanding of what customers were trying to accomplish with a milkshake, enabling the restaurant to shape its offerings around those needs and drive stronger customer adoption and sales growth.


Principles That Define JTBD

Understanding individuals or teams is inherently contextual and can evolve significantly depending on the situation and circumstances. However, several core principles underpin the JTBD Framework:

  • Customer-centricity: This is the core mindset surrounding the framework. Start by understanding the customer’s situation, needs, motivations, and desired progress rather than starting with the offering itself.
  • Jobs matter, not Products: Develop a deeper understanding of the job the customer is trying to accomplish through a solution rather than focusing primarily on which product feature might excite the customer.
  • Solution-agnostic: Any offering that can solve the problem and help accomplish the job can potentially compete for the customer’s choice—even if it comes from an entirely different product or service category.
  • Hire and Fire: Customers “hire” a product or service to accomplish a job they need to get done and can “fire” it when an alternative performs that job better or provides greater value.
  • Desired Measurable Outcomes: Define what “good” looks like from the customer’s perspective. This could include speed, effort, convenience, satisfaction, confidence, reliability, and other measurable outcomes.
  • Context-dependent, Product-independent: The job can depend heavily on the customer’s context and may vary as that context changes. However, the underlying job is independent of any specific product, service, offering, or its characteristics.


Experion Story – From JTBD Theory to Practice

The principles of the Jobs-to-Be-Done Framework provide a useful perspective on how technology companies can understand and respond to customer needs. At Experion, with an established operating model and experience in IT services and AI-enabled product engineering, we place strong emphasis on understanding customer requirements, the context in which they arise, and the underlying objectives before shaping a solution.

We do not view customer requirements simply as a list of features, technologies, or deliverables. Instead, we apply the underlying principles of JTBD to understand the broader problem the customer is trying to solve. This means looking beyond “What does the customer want us to build?” and asking more fundamental questions:

  • What is the customer trying to accomplish?
  • What situation are they dealing with?
  • What outcomes matter most?
  • What friction exists in achieving those outcomes?
  • What alternatives are they currently using?


Mapping Experion ARC to the JTBD Framework

Experion’s AI Studio and operating model, ARC, closely aligns with JTBD thinking by identifying the outcomes stakeholders seek, understanding the process constraints that hinder those outcomes, and systematically discovering, validating, and scaling AI opportunities that deliver measurable value against the intended job.

Moreover, ARC Rethink, the AI opportunity discovery and evaluation engine within the ARC model, leverages the core principles of the JTBD Framework by uncovering the business outcomes users are trying to achieve, mapping current processes around those jobs, identifying friction, and prioritizing AI interventions that can measurably improve how the job gets done.

Experion’s customer-centric perspective has helped us move from being primarily solution-led to becoming more outcome-led. It creates a stronger understanding of the customer’s context, enables teams to identify unmet needs, and opens opportunities to rethink how technology can create value. In practice, JTBD becomes less of a theoretical framework and more of a way of thinking—one that keeps the customer’s desired progress at the center of product, service, and solution decisions.


Conclusion

The Jobs-to-Be-Done Framework helps organizations move beyond stated requirements and understand the deeper progress customers are trying to achieve. By focusing on context, motivations, friction, alternatives, and measurable outcomes, JTBD enables teams to design products and services that are more relevant, differentiated, and valuable to the people using them.

For Experion, this perspective reinforces an outcome-led approach to product engineering and AI transformation. Through ARC and ARC Rethink, JTBD principles can be translated into a practical method for discovering opportunities, validating priorities, and shaping interventions around the jobs that matter most. The result is technology that does not merely deliver features but helps customers achieve meaningful and measurable progress.

Workforce Planning Software

Workforce plans used to be built around relatively stable assumptions: next year’s budget, expected attrition, and an approved hiring target. That model is under pressure. Demand changes faster, skills become obsolete sooner, and AI is altering both the work to be done and the mix of human and digital capacity needed to do it.

The question is no longer simply, “How many people do we need?” It is, “What work will matter, which skills will deliver it, where should that capacity come from, and what will each choice cost?”


Why Workforce Planning Matters Now?

Workforce planning converts business goals into practical decisions about headcount, skills, capacity, location, cost, and timing.

It helps an organization understand the workforce it has, anticipate the workforce it will need, and close the gap through hiring, reskilling, redeployment, contractors, automation, or redesigned work. That matters now because organizations are planning amid economic uncertainty, demographic change, technology shifts, and fast-changing skill requirements.

The World Economic Forum’s Future of Jobs Report 2025, based on more than 1,000 employers representing over 14 million workers, identifies technological change, economic uncertainty, demographic shifts, geoeconomic fragmentation, and the green transition as major forces reshaping work through 2030.

Software is what makes this discipline continuous and operational. A workforce planning system can combine HR, finance, operational, project, and labor-market data; test alternative assumptions; expose capacity and skill gaps; and measure actual results against the plan. Instead of reconciling static spreadsheets every quarter, leaders can revisit decisions when demand, attrition, budgets, or strategic priorities change.


Key Takeaways

These are the decisions and design principles that matter most when evaluating a workforce planning solution.

  • Planning must begin with business demand. Headcount is an output of the work, skills, service levels, projects, and growth targets the organization expects to deliver.
  • A shared data foundation is essential. HR, finance, operations, and recruiting need consistent definitions for roles, positions, skills, capacity, vacancies, and workforce cost.
  • Scenarios are more useful than a single forecast. Leaders should be able to compare growth, slowdown, automation, location, hiring, reskilling, and redeployment options before committing resources.
  • Skills are becoming as important as jobs. A headcount plan may show enough people overall while concealing shortages in the capabilities that future work requires.
  • AI should improve judgment, not obscure it. Predictive models and generative interfaces can accelerate analysis, but assumptions, recommendations, and consequential decisions require human review.
  • Integration determines whether plans stay current. A workforce planning tool delivers more value when actual hiring, payroll, project demand, attrition, and financial results flow back into the model.
  • The best workforce planning software fits the decision model. The right choice may be a configurable product, a custom workforce planning software platform, or a hybrid architecture that extends existing HCM and ERP investments.


What is Workforce Planning Software?

Workforce Planning

The value of workforce planning software becomes clearer when you look at the decisions it helps businesses make. Workforce planning software is a digital system for analyzing the current workforce, forecasting future labor and skill demand, identifying gaps, modeling alternative scenarios, and turning those findings into funded action plans. It brings workforce planning and analytics software capabilities together so leaders can connect people data with operational demand and financial constraints.

A mature workforce planning system typically supports three planning horizons:

Planning horizon Core question Typical decisions
Operational Do we have enough capacity for the coming days or weeks? Shifts, assignments, overtime, contractors, workload balancing
Tactical What people and skills will departments or projects need over the coming quarters? Hiring, vacancy timing, project staffing, reskilling, redeployment
Strategic What workforce will the business model require over the next two to five years? Location strategy, role redesign, automation, capability building, organizational shape

Who Uses Workforce Planning Software?

Workforce planning is cross-functional, as workforce decisions impact service delivery, growth, risk and cost at the same time.

CHROs and people teams use it to plan talent supply, skills, mobility and attrition. It is used by CFOs and finance teams to manage workforce budgets and compare scenarios. COOs and business leaders use it to align capacity with demand.

Talent-acquisition teams turn approved gaps into hiring plans, while learning teams translate skill gaps into development priorities. Project, resource, and operations managers use workforce capacity planning software to staff work and eliminate bottlenecks. Executive teams use consolidated scenarios to make trade-offs across the enterprise.

Workforce Planning Software vs. Workforce Management Software

The two categories overlap, but they solve different time horizons and management questions.

Area Workforce planning software Workforce management software
Primary purpose Decide the future workforce required to execute strategy Run and administer the workforce day to day
Typical horizon Months to several years Real time to weeks
Core questions What roles, skills, capacity, and cost will we need? Who is working, when, where, and under what rules?
Common capabilities Demand forecasting, headcount planning, skills gaps, scenarios, cost modeling Time and attendance, scheduling, leave, labor compliance, task execution
Main users Strategy, HR, finance, operations, business leaders Operations, managers, payroll, HR administrators
Relationship Sets future capacity and talent direction Supplies actuals and executes near-term deployment

Organizations often need both. Workforce management data provides actual hours, availability, productivity, overtime, and absence patterns. Workforce planning systems use that evidence to improve future assumptions.


Why do Businesses Need Workforce Planning Software Solution?

The need becomes clear when workforce decisions are delayed by fragmented data, competing assumptions, or plans that cannot adapt.

Core Problems Workforce Planning Software Solves

  1. Changing workforce demands. Demand can shift by product, channel, region, season, or customer segment. Software allows planners to update drivers and see how the workforce requirement changes.
  2. Skills shortages and talent gaps. A skills inventory compared with future work makes shortages visible early enough to build, buy, borrow, or automate capacity.
  3. Workforce cost pressures. Salary, benefits, overtime, contractors, hiring, and vacancy costs can be modeled together so savings do not create hidden delivery risks.
  4. Unplanned employee turnover. Attrition assumptions and risk signals help teams estimate replacement demand, protect critical roles, and prepare succession or recruiting actions.
  5. Inability to model scenarios. Growth, contraction, reorganizations, acquisitions, location changes, and automation can be tested side by side instead of debated through disconnected files.
  6. Difficulty forecasting future headcount. Driver-based projections tie human requirements back to company volumes, workload, productivity and service levels, rather than merely projecting historical headcounts.
  7. Misalignment between hiring plans and budget. A standard planning procedure ties together sought positions, start dates, compensation assumptions, approvals and financial impact.
  8. Spreadsheet-based workforce planning challenges. Version confusion, flawed formulas, manual consolidation, weak access control, and limited auditability make enterprise planning slow and fragile.
  9. Aligning workforce capacity with business growth. Capacity views show when current teams can absorb growth and when hiring, reskilling, automation, or external talent must begin.
  10. Disconnect between HR data and finance systems. Integrated planning provides a common view on positions, people, vacancies, expenses and predictions for both services while preserving system ownership.


How Does Workforce Planning Software Work?

The planning cycle converts workforce data into an agreed plan, then keeps that plan responsive to actual change.

  1. Assess the current workforce. Consolidate employee, role, position, location, tenure, cost, performance, availability, and skills data into a governed baseline.
  2. Analyze workforce supply and capacity.  Measure the available productive capacity including vacancies, leave, attrition, utilization, working habits and job restrictions.
  3. Forecast future workforce demand. Translate revenue plans, service volumes, projects, operating hours, productivity targets, and strategic initiatives into labor and skill requirements.
  4. Identify headcount and skills gaps. Compare forecast demand with internal supply by period, business unit, role, location, proficiency, and cost.
  5. Build workforce scenarios. Change assumptions such as growth, automation, attrition, hiring lead time, compensation, location, or productivity and compare the results.
  6. Develop hiring, reskilling, and redeployment plans. Select the right response for each gap, assign owners, sequence actions, and connect them to approved budgets.
  7. Monitor workforce plans and adjust forecasts. Feed actual hiring, exits, transfers, costs, demand, and delivery results back into the model so the plan remains useful.


Key Features of Workforce Planning Software

A modern workforce planning solution combines forecasting, capacity, skills, costs, and workforce analytics into one connected system. These capabilities help organizations to predict talent requirements, compare different scenarios, and make workforce decisions that stay aligned with business priorities.

Workforce Demand Forecasting

Forecasts future workforce needs by translating business demand, seasonal fluctuations, and project requirements into the roles, skills, and capacity required. It allows companies to plan ahead based on operational drivers, not just historical headcount.

Workforce Capacity Planning

Compares expected workload with employee availability, skills, utilization, vacancies, and productivity. This allows firms to maintain adequate capacity and reduce overtime, burnout, idle time and delivery delays.

Headcount Planning and Org Modeling

Connects workforce demand with planned positions, hiring timelines, budgets, and organizational structures. Leaders can assess the impact of growth, vacancies, reorganizations, and location changes before making decisions.

Skills and Competency Gap Analysis

Compares existing workforce capabilities with the skills and proficiency levels required for future work. It helps businesses identify critical gaps and prioritize hiring, reskilling, internal mobility, and succession planning.

Scenario Planning and What-If Analysis

Allows leaders to compare the workforce, cost, and operational impact of growth, hiring, restructuring, automation, or location changes. It also supports informed choices between options such as recruiting externally, reskilling employees, or redeploying existing talent.

Workforce Cost Planning

Brings salaries, benefits, hiring, contractors, overtime, training, and other labor costs into workforce forecasts. This helps HR, finance, and business leaders understand the financial impact of each workforce decision.

Integrations

Links workforce plans with HR, payroll, finance, recruitment, project, and operational systems. Reliable data exchange keeps forecasts current, reduces manual reconciliation, and provides a consistent view across the business.

Scheduling and Shift Optmization

Matches workforce demand with employee availability, skills, preferences, labor rules, and cost constraints. Experion demonstrated the value of connected data and scheduling through a cloud-native facilities-management platform that unified operations across 6,000+ sites, accelerated scheduling by 40%, lowered manual errors by 25%, and improved resource utilization and staff productivity by 15%.

Workforce Analytics and Dashboards

Offers role-based visibility into headcount, capacity, skills, costs, vacancies, attrition, trends, and forecast-versus-actual performance. Leaders can identify emerging risks and move quickly to take action based on insights.

Workforce Planning Reports

Generates executive summaries, departmental plans, workforce gap reports, scenario comparisons, and budget variance reports. Approval workflows, audit histories, and controlled distribution support consistent and accountable planning.


What are the Benefits of Workforce Planning Software

The value is not a more polished headcount report. It is earlier, better-coordinated action across strategy, finance, HR, and operations.

  • More accurate workforce forecasting. Driver-based forecasts make assumptions visible and improve as actual outcomes feed back into the model.
  • Better workforce capacity utilization. Managers can move work, rebalance teams, adjust schedules, or add capacity before bottlenecks affect customers.
  • Reduced workforce costs. Scenario comparisons expose avoidable overtime, premature hiring, prolonged vacancies, underused capacity, and an unsustainable contractor mix.
  • Faster hiring decisions. Approved gaps can feed into recruitment with clearer role, skill, timing, location, and budget requirements.
  • Improved skills planning. Leaders gain time to build critical capabilities internally rather than reacting after shortages delay strategic work.
  • Better resource allocation. Scarce people and specialist skills can be directed to the initiatives with the greatest business value.
  • Reduced workforce risks. Critical-role dependency, attrition exposure, succession gaps, compliance constraints, and capacity shortfalls become visible sooner.
  • Improved workforce agility. Planners can revise scenarios quickly when demand, costs, or priorities change.
  • Better alignment between HR and business strategy. Workforce decisions are framed in the same operational and financial terms that run the business.


How Does AI Workforce Planning Software Help Businesses?

Workforce Planning Software

AI workforce planning software combines complex workforce data into timely projections, risk warnings and actionable recommendations. It allows companies to proactively plan for skills and capacity needs, evaluate scenarios, and make faster, more informed workforce decisions.

  1. AI-based workforce forecasting. Machine-learning models can uncover nonlinear relationships among demand drivers, staffing levels, productivity, and seasonality, then update forecasts as new data arrives.
  2. Predictive workforce analytics. Models can expose emerging capacity, vacancy, absence, cost, or skill risks so leaders can investigate them before they become operational failures.
  3. AI-powered skills gap analysis. Natural-language processing can help normalize skill terms across profiles, roles, learning records, and project histories, while people validate proficiency and relevance.
  4. Predictive attrition insights. Responsible models can identify aggregate risk patterns and support retention planning. They should not be treated as certain predictions about individuals or used without appropriate legal, ethical, and HR review.
  5. AI-assisted scenario planning. AI can suggest plausible assumptions, find constrained options, and compare a larger scenario space, leaving leaders accountable for the final trade-offs.
  6. Generative AI for workforce data queries. A governed conversational interface can let authorized users ask questions in plain language, such as which teams face the largest skill gap next quarter, and receive answers grounded in approved data.
  7. Automated workforce recommendations. The system can propose hiring, redeployment, learning, contracting, or scheduling actions, with reasons, confidence, cost, and policy constraints made visible.
  8. AI-driven workforce optimization. Optimization can balance service levels, skills, availability, cost, and employee constraints across complex assignments or shifts.
  9. Human oversight and responsible AI. Material decisions should remain reviewable and contestable. Access controls, lineage, bias testing, monitoring, explanations, and clear decision ownership are core product requirements.

Current research reinforces why this matters. McKinsey Global Institute reported in late 2025 that demand for AI fluency in US job postings had risen nearly sevenfold in two years, while emphasizing that automation potential is not the same as job-loss prediction.

Strategic workforce planning software therefore needs to model task and skill change, not apply a simplistic “jobs replaced” assumption.


Major Workforce Planning Software Integrations

The platform becomes more accurate and actionable when it connects planning assumptions to authoritative enterprise data and execution workflows.

  • HRIS and HCM systems. Supply worker, position, organization, job, skills, performance, absence, and movement data.
  • Payroll systems. Provide actual compensation, overtime, allowances, and labor-cost evidence for forecast reconciliation.
  • ERP and financial systems. Connect workforce plans to budgets, cost centers, forecasts, projects, and actual financial performance.
  • CRM systems. Translate pipeline, customer segments, service commitments, and regional growth into demand signals where appropriate.
  • Project and resource management systems. Supply project demand, allocation, utilization, milestones, and role requirements.
  • Recruitment platforms. Convert approved demand into requisitions and return pipeline, time-to-fill, offer, and start-date data.
  • Business intelligence platforms. Extend governed analytics and distribute workforce insights in the reporting environment leaders already use.
  • Data warehouses. Provide curated history, master data, and scalable access to cross-functional workforce and business information.
  • APIs and custom integrations. Connect specialist, legacy, partner, and industry-specific systems that packaged connectors do not cover.


Experion combines product engineering, cloud and data platform expertise, enterprise integration, and advanced analytics to build connected workforce ecosystems. Our experience integrating HR, recruitment, financial, operational, and third-party platforms enables organizations to create a secure, scalable foundation for workforce planning and decision-making.


Types of Workforce Planning Software

Different planning problems require different depths of modeling, workflow, and industry context. Strategic workforce planning solutions should be selected according to the decisions they must improve, not the number of features in a product comparison.

Type Best suited to Typical strength Watch-out
Strategic workforce planning software Multi-year enterprise transformation Skills, scenarios, organization shape, strategic demand May be too high-level for daily capacity decisions
Headcount and position planning Finance-HR budget alignment Positions, vacancies, approvals, compensation, budget Can reduce planning to “number of seats”
Workforce capacity planning software Operations, services, projects, field work Workload, availability, utilization, scheduling Requires reliable operational demand data
Skills-based planning systems Transformation, internal mobility, capability building Skill inventory, proficiency, gaps, reskilling paths Skill data decays without ownership and validation
Workforce planning and analytics software Enterprises with distributed data Dashboards, trends, forecasting, variance analysis Insights may not lead to action without workflow
Industry-specific workforce planning solutions Healthcare, logistics, construction, retail, and regulated sectors Domain rules, credentials, service levels, seasonality Generic configuration may not cover real constraints
Workforce planning software for small business Growing small and mid-sized organizations Simpler headcount, budget, and hiring visibility Enterprise platforms can add needless cost and complexity
Custom workforce planning software Distinct operating models or integration needs Fit, differentiation, extensibility, control Requires product ownership and lifecycle investment


Workforce Planning Software Use Cases

The strongest use cases begin with a consequential business decision rather than a desire to digitize an existing spreadsheet.

Headcount and Hiring Planning

Turn revenue, workload, vacancy, attrition, and productivity assumptions into timed, costed, and approved hiring demand. Experion’s healthcare staffing platform shows how connected hiring workflows can improve execution after workforce demand is approved. For a global home-healthcare provider, Experion unified recruitment and onboarding with integrations across Workday, SkillSurvey, Sterling, DocuSign, Indeed, and Zoom.

The platform reduced hiring cycles by 40%, cut onboarding time by 30%, increased recruitment productivity by 50%, and reduced interview scheduling from two days to three minutes.

Workforce Capacity Planning

Compares expected workload with available people, skills, and productive hours to identify capacity gaps early. This helps organizations balance resources before shortages affect employees, service quality, or customer outcomes.

Skills-Based Workforce Planning

Maps current workforce capabilities against the skills and proficiency levels required for future work. It helps organizations prioritize reskilling, hiring, and internal mobility while making better use of existing talent.

Workforce Cost Optimization

Evaluates workforce mix, location, overtime, vacancies, reskilling, and automation against both cost and operational impact. This helps businesses improve efficiency without relying solely on broad headcount reductions.

Project and Resource Planning

Matches project demand with available roles and skills while highlighting resource conflicts and staffing gaps. It helps leaders allocate scarce expertise, plan by project phase, and keep workforce commitments aligned with delivery requirements.

Workforce Reskilling and Redeployment

Identifies employees whose skills and experience may align with emerging roles or changing business needs. It helps organizations compare reskilling and redeployment with external hiring while considering proficiency, career interests, and development time.

Organizational Restructuring

Models the impact of proposed changes to roles, reporting structures, locations, costs, and spans of control before implementation. It helps leaders identify capability gaps, management overload, duplicated roles, and transition risks while maintaining strict data governance.

Expansion and Growth Planning

Determines when, where, and how workforce capacity should grow to support new markets, products, facilities, or customers. Leaders can compare talent availability, hiring timelines, costs, regulatory requirements, and ramp-up needs before committing investment.

Workforce Planning for AI and Automation

Identifies which activities can be automated or augmented and the new skills, roles, and oversight required. This helps organizations redesign work responsibly, redeploy capacity, and connect AI adoption with measurable business value.


Key Points to Look for in a Workforce Planning Solution?

Evaluation should reflect the organization’s decisions, data maturity, risk profile, and operating model, not a generic feature checklist alone.

  1. Workforce planning requirements. Define the decisions, users, planning horizons, business units, geographies, and pain points the solution must support.
  2. Forecasting capabilities. Check whether the system supports driver-based, trend, ratio, seasonal, project, and configurable models with transparent assumptions.
  3. Scenario planning. Confirm users can clone, compare, version, approve, and explain scenarios without technical support for every change.
  4. Skills and talent planning. Evaluate taxonomy management, proficiency, evidence, skills inference, internal mobility, learning links, and employee participation.
  5. Analytics and reporting. Look for role-based dashboards, drill-down, variance analysis, alerts, exports, and a semantic layer with consistent metric definitions.
  6. AI capabilities. Ask what each model does, which data it uses, how it is evaluated, how recommendations are explained, and where human review occurs.
  7. Integration capabilities. Assess packaged connectors, APIs, batch and event patterns, data lineage, monitoring, error handling, and master-data design.
  8. Scalability. Test data volumes, concurrent users, scenario complexity, geographic coverage, and performance as planning expands.
  9. Security and compliance. Require least-privilege access, segregation of duties, encryption, audit history, retention controls, regional hosting options, and privacy-by-design.
  10. Customization. Determine whether planning models, workflows, roles, rules, dashboards, and user experiences can reflect the operating model without creating an upgrade trap.
  11. Implementation and support. Examine data migration, model validation, change management, training, release practices, service levels, and the provider’s product-engineering depth.
  12. Total cost of ownership. Include licenses, implementation, integration, data preparation, infrastructure, change, support, upgrades, model monitoring, and internal product ownership.


Common Workforce Planning Challenges

Most implementation problems come from unclear ownership, weak data foundations, or attempting to automate a planning process that has not been agreed.

  • Inaccurate workforce data. Missing dates, duplicate positions, inconsistent job codes, and stale skills produce confident-looking but unreliable forecasts.
  • Fragmented workforce information. Employee, contractor, project, learning, recruiting, finance, and operations data often live in separate systems with different identifiers.
  • Unpredictable workforce demand. Plans need ranges, drivers, and scenario triggers when demand cannot be forecast as a single number.
  • Skills shortages. Organizations may lack both external supply and a credible internal route to proficiency, requiring earlier choices and alternative operating models.
  • High employee turnover. Historical averages can conceal differences by role, tenure, manager, location, or labor market and should not become unquestioned assumptions.
  • Workforce cost uncertainty. Compensation changes, overtime, vacancies, contractors, and hiring timing can materially shift the forecast.
  • Legacy HR systems. Older platforms may require staged extraction, integration layers, master-data remediation, or modernization rather than direct real-time connection.
  • Spreadsheet dependency. Users may recreate offline files if the new system is slower, less flexible, or fails to explain how numbers were calculated.
  • Difficulty modeling workforce scenarios. Too many variables can make models opaque. Start with material drivers and add complexity only when it improves decisions.
  • Lack of real-time workforce visibility. Not every metric needs to be real time. Define the decision latency for each data set and update it accordingly.


How to Choose the Best Workplace Planning Software Development Provider?

Choose a provider that can translate workforce priorities across HR, finance, and operations into a secure, scalable product with clear planning models, intuitive workflows, enterprise integrations, and measurable outcomes. Evaluate how the provider handles ambiguity, validates assumptions, and adapts the solution to the organization’s data, processes, and decision context.

Experion combines strategy and consulting, product engineering, experience design, cloud, data and AI, quality engineering, and ongoing support. Its healthcare staffing and facilities-management work demonstrates capabilities in connected workflows, enterprise integrations, scheduling, data platforms, analytics, mobile experiences, and measurable operational improvement, creating a strong foundation for tailored workforce planning solutions.


Custom Workforce Planning Software vs. Off-the-Shelf Software

The build-or-buy decision should be based on differentiation, fit, integration complexity, time to value, and the organization’s willingness to own a product over time.

Decision factor Off-the-shelf software Custom workforce planning software
Time to initial deployment Usually faster for standard use cases Longer because discovery, design, engineering, and validation are required
Process fit Best when the organization can adopt standard planning models Best when decision logic or operating constraints are distinctive
Integrations Packaged connectors may speed common connections Can support complex legacy, domain, partner, and proprietary systems
Scenario models Configurable within vendor boundaries Can encode organization-specific demand, skills, capacity, cost, and risk models
User experience Consistent and proven, but shared across customers Can be tailored by role, workflow, terminology, and context
AI control Vendor determines much of the model and roadmap Greater control over models, data, evaluation, explanations, and guardrails
Extensibility Depends on APIs, configuration, and marketplace Can evolve as strategy and operating models change
Implementation risk Lower product-build risk; fit and adoption risks remain Higher delivery and ownership demands; closer fit can improve adoption
Cost profile Subscription plus configuration and integration Upfront product investment plus ongoing ownership and enhancement
Best choice when Requirements are common and speed outweighs differentiation Planning is strategically distinctive or existing systems need a unifying layer

A hybrid is often pragmatic: retain a core HCM or planning product, then engineer a domain-specific data, workflow, optimization, or experience layer around it.


How to Implement Workforce Planning Software?

A phased implementation reduces risk by proving the planning model and data before expanding scale, complexity, or AI.

  1. Define Workforce Planning Objectives

Identify the workforce decisions, business units, planning horizons, and use cases the solution must support. Set measurable outcomes, decision owners, and clear priorities for the first release.

  1. Assess Existing Workforce Data

Evaluate workforce data sources, quality, ownership, refresh rates, permissions, and regional constraints. Standardize key definitions such as headcount, positions, capacity, skills, and proficiency before building forecasts.

  1. Define Workforce Forecasting Models

Select forecasting models that users can understand, validate, and improve. Define demand drivers, attrition, productivity, hiring lead times, constraints, and confidence ranges, then test the models against historical data.

  1. Identify Required Integrations

Prioritize the HR, finance, payroll, recruitment, project, and operational systems required for reliable planning. Define data ownership, synchronization, security, error handling, and reconciliation for each integration.

  1. Configure or Develop the Solution

Build a focused first release that supports an end-to-end workforce planning cycle. Involve HR, finance, business, and data teams in iterative reviews while keeping assumptions, warnings, and data freshness visible.

  1. Validate Data and Forecasts

Reconcile source data, test scenarios and edge cases, and compare forecasts with known outcomes. For AI components, assess accuracy, bias, drift, explainability, failure behavior, and human-review controls.

  1. Deploy and Train Users

Pilot the solution with a defined business unit or use case before expanding it. Provide role-based training, governance guidance, and support aligned with existing budgeting, hiring, and management processes.

  1. Monitor and Optimize

Track forecast accuracy, adoption, data quality, model performance, and business outcomes after launch. Use forecast-versus-actual results and user feedback to improve the solution before scaling it further.


Future of Workforce Planning Software

The category is moving from periodic headcount administration toward a continuous intelligence layer for decisions about work, skills, technology, and cost.

  • AI-driven workforce forecasting. Models will combine more operational signals, quantify uncertainty, and update assumptions more frequently.
  • Skills-based workforce planning. Organizations will increasingly plan at the level of capabilities and tasks while retaining roles as a practical structure for accountability and careers.
  • Predictive workforce analytics. Earlier warning signals will help planners investigate risks before they become vacancies, cost overruns, or delivery failures.
  • Real-time workforce planning. Event-driven updates will matter in volatile operations, while governance will distinguish truly time-sensitive decisions from those suited to daily or monthly refreshes.
  • Generative AI workforce assistants. Conversational interfaces will make complex data more accessible, summarize scenarios, explain variances, and help users construct queries or models.
  • Continuous workforce planning. Rolling forecasts and trigger-based reviews will increasingly complement or replace a single annual planning event.
  • Workforce planning for automation and AI adoption. Plans will account for tasks performed by people, software agents, and machines, along with the skills, controls, and redesigned workflows needed to make that collaboration productive.

The direction is important, but responsible implementation is more important. The organizations that benefit will be those that combine technology with sound data, explicit operating choices, product ownership, workforce participation, and human accountability.


Conclusion

Workforce planning software creates value when it helps leaders act sooner and choose more intelligently, not when it merely digitizes an annual spreadsheet.

The strongest workforce planning solutions connect strategy to demand, demand to skills and capacity, and capacity to costed actions. They let HR, finance, and operations work from consistent evidence while preserving the ability to test assumptions. AI can broaden that capability, but it should make decisions more transparent and responsive, not less accountable.

Retail POS System

Running a retail store without a connected POS can become surprisingly complicated.

A sale happens at the counter, but inventory is updated somewhere else. Promotions are maintained manually. Returns depend on someone finding the original transaction. Managers wait for end-of-day reports. Online orders live in another system entirely. As the business adds stores, products, payment methods, or sales channels, those gaps start creating real operational work.

A modern retail POS system brings more of that activity together. It still handles the most visible part of retail, the transaction, but it can also connect sales, inventory, products, customer information, employees, promotions, payments, reporting, and increasingly e-commerce.

The checkout screen is only the part customers see. What matters to the retailer is everything that happens around it.


Key Takeaways

  • A retail POS system does much more than process payments.
  • Inventory, pricing, promotions, customers, and transactions can be managed from the same ecosystem.
  • Cloud and mobile POS models give retailers more flexibility, but connectivity and security need careful planning.
  • Omnichannel retail depends heavily on accurate inventory and system integration.
  • POS data can inform merchandising, replenishment, staffing, and store performance.
  • Custom POS development makes sense when standard platforms cannot support the retailer’s operating model.


What is a POS System in Retail?

Retail POS System

A point of sale system is the combination of software, and often hardware, used to complete a retail transaction and record what happened.

At the checkout, it identifies the items being purchased, retrieves prices, applies promotions or taxes, accepts payment, generates a receipt, and records the transaction. Behind the scenes, it may also update inventory, customer profiles, loyalty balances, accounting records, and store reports.

People searching what is a pos system in retail are often thinking of the checkout terminal. The modern answer is broader. The POS has become one of the main operational systems inside the store.

Search phrases such as what is retail pos systems usually point to the same idea: software and connected devices used to manage transactions and related retail activities across one or more stores.

A retail point of sales system may include terminals, barcode scanners, receipt printers, payment devices, cash drawers, weighing scales, and software connected with inventory, ERP, CRM, e-commerce, or loyalty platforms.

Difference Between a Modern Retail POS System and a Traditional Cash Register

A traditional cash register primarily records sales, accepts money, and provides a receipt.

A modern POS has much more context.

It knows which product was sold, what price was applied, whether a promotion changed that price, which store made the sale, which employee processed it, how the customer paid, and how the transaction affected available inventory.

That information can then move into other systems.

So while a cash register closes a transaction, modern retail pos systems can become part of the operating infrastructure of the business.


How a Retail POS System Works?

  1. Product selection/scanning: The cashier scans a barcode, searches the product catalogue, or selects an item from the screen.
  1. Pricing and discount calculation: The system retrieves the correct price and applies relevant promotions, discounts, tax rules, or customer benefits.
  1. Payment processing: The customer pays using an accepted method such as card, cash, wallet, gift card, or another supported option.
  1. Inventory update: The transaction can reduce stock on hand immediately or pass the update to an inventory platform.
  1. Receipt generation: A printed or digital receipt confirms the transaction.
  1. Transaction recording: The sale becomes part of store reporting, reconciliation, analytics, customer history, and other connected business processes.


What Does a Retail POS System Manage?

Sales transactions are the obvious starting point, but they are only one part of the picture.

A retail pos system software can maintain product catalogues, stock quantities, pricing, discounts, promotions, payment information, returns, exchanges, customer profiles, employee access, and store-level reporting.

Inventory is particularly important. A sale at the checkout changes what the business can promise to the next customer.

Returns and exchanges also need to reconnect with the original sale and, where appropriate, put inventory back into circulation.

Customer information may connect purchases with loyalty programs or personalized offers.

Employee permissions help control who can process refunds, change prices, approve discounts, or access sensitive reports.

In other words, retail pos software sits at the point where several everyday retail processes meet.


Why do Retail Businesses Need a Point of Sale System?

The simplest reason is speed.

A good pos system for retail store operations reduces the number of manual steps required to complete a sale. Prices do not need to be entered repeatedly, promotions can be applied automatically, and payments can flow through integrated devices.

Inventory visibility improves because sales and stock movement are connected.

Manual errors can fall because product information and pricing come from maintained data rather than handwritten lists or memory.

Sales information becomes easier to consolidate, especially when several stores operate under the same business.

Customers benefit too. Faster checkout, clear receipts, easier returns, and consistent promotions all contribute to a smoother experience.

For management, the bigger gain is visibility. The business can start answering questions about sales, inventory, products, stores, and employees from current data rather than waiting for manually assembled reports.

From Transaction Processing to Retail Operations

POS technology has gradually moved beyond billing.

What began as a system for recording sales now sits alongside product, inventory, customer, payment, employee, and reporting workflows.

That evolution explains why the phrase pos system and software now covers a much broader technology landscape than a terminal sitting beside a cash drawer.

For retailers, the POS can become the operational connection between what happens at the checkout and what the rest of the business needs to know.


What are the Key Features of a Retail POS System?

Fast checkout remains essential. A system that makes a straightforward purchase slow has missed its most basic job.

Barcode scanning speeds up product identification and reduces manual entry. This is also the practical answer to how barcode scanning integrates with retail pos system: the scanner reads the item’s barcode, the POS uses it to retrieve the product record, price, tax, and inventory information, and the transaction updates the relevant systems when the sale is completed.

Real-time inventory tracking provides a clearer view of available stock.

Multiple payment methods give customers flexibility.

Promotions and discounts should be applied consistently rather than depending on staff remembering every offer.

Returns and refunds need controlled workflows with appropriate permissions.

Customer profiles and loyalty management can connect transactions with preferences, rewards, or purchase history.

Employee permissions control sensitive functions.

Reporting provides visibility into sales and store performance.

Multi-store management allows head office to maintain a wider view across locations.

Offline capability can keep selected transactions moving during temporary connectivity problems.

Finally, tax and compliance configuration needs to reflect the markets in which the retailer operates.


How Retail POS Systems Improve the Customer Experience?

Retail customers tend to notice the POS most when something goes wrong.

A slow queue, rejected promotion, confusing return, or payment failure can make the technology suddenly very visible.

Faster checkout reduces waiting. Flexible payment methods let customers use familiar options. Digital receipts provide an alternative to paper.

Connected transaction history can make returns easier because staff do not have to reconstruct the sale manually.

Customer profiles can support relevant promotions or loyalty benefits when customers choose to participate.

Mobile and assisted checkout can move payment away from a fixed counter in stores where that improves the experience.

Perhaps most importantly, customers increasingly expect consistency. A price or promotion they saw online should not become a completely different conversation when they arrive in the store.


Retail POS for Omnichannel Commerce

In omnichannel retail, the store no longer operates as a separate world from the website or app. A customer may browse online, place an order from home, pick it up at a nearby store, and later return it at a different location. A promotion launched online may also need to work at the checkout counter. For the customer, all of this feels like one journey, even though several systems are working behind the scenes.

That is why the POS needs to connect with e-commerce, inventory, customer, order, and payment platforms. The aim is to keep information moving across channels so store teams and digital systems are working from the same picture.

Inventory is one of the most important parts of this setup. Staff need to know not only what is physically on the shelf, but also what has already been reserved, ordered online, or allocated elsewhere. An online retail pos system therefore works best when it can exchange information continuously with store systems instead of treating e-commerce and physical retail as separate operations.

Why Unified Inventory Matters for Omnichannel Retail?

In omnichannel retail, inventory is closely tied to the promise made to the customer. If a website shows an item as available for pickup, the customer expects it to be there when they arrive. When that information is wrong, what looks like an inventory issue internally quickly becomes a customer experience problem.

Unified inventory gives retailers a clearer view of stock across stores and digital channels. It reduces the risk of overselling and helps teams understand what is available, reserved, or already committed to another order.

That visibility also makes services such as store pickup and ship-from-store easier to manage because physical inventory can be used more intelligently across channels. For retailers operating in several locations, accurate stock information is what makes those fulfillment promises believable.


Retail POS Analytics: What Can You Learn From Your Sales Data?

A POS system records far more than the value of each sale. Over time, those transactions can tell retailers a great deal about what customers are buying, when they are buying it, and how individual products and stores are performing.

Sales data can show which products are moving quickly and which are sitting on shelves. It can also help teams compare average transaction value, units per transaction, inventory turnover, and product sell-through. Looking at these measures together gives a fuller picture than simply ranking products by sales volume.

The timing of transactions is useful too. Peak periods can inform staffing and replenishment decisions, while return and refund patterns may point to issues with sizing, product quality, pricing, or customer expectations. Store-level data can also highlight differences between locations that may be worth investigating.

The real value of POS analytics is not the report itself. It is what the retailer does with it. When sales data is easy to understand, it can support better decisions around assortment, stock, staffing, promotions, and overall store performance.

Using POS Data for Better Retail Decisions

POS data becomes valuable when it changes a decision.

A retailer may discover that a product performs strongly only in certain locations. Another item sells quickly but is repeatedly out of stock. A promotion may lift transaction volume without improving margin.

Those patterns can influence replenishment, merchandising, promotions, assortment, staffing, and demand planning.

The objective is not to produce more dashboards. It is to understand what the transactions are saying about the business.


POS Systems for Retail Stores

The requirements of pos systems for retail stores change considerably with the business.

A single boutique may need straightforward billing, payments, inventory, and customer history. A supermarket may depend on scales, complex promotions, loyalty, high transaction volume, product master data, and several checkout lanes.

A retailer with dozens of locations may need central pricing, store-specific configuration, remote support, real-time data synchronization, and consolidated reporting.

This is why phrases such as pos systems for retail, store pos systems, or pos systems retail stores describe a category rather than one standard product.


Experion’s documented retail work includes store POS integration with real-time store and cloud synchronization, e-commerce connectivity, digital receipts, loyalty, gift cards, electronic shelf labels, and store devices.


Types of Retail POS Systems

  1. Traditional On-Premise POS: Software and data are primarily maintained on infrastructure located within the store or the retailer’s own environment.
  1. Cloud-Based POS: Applications and central data are hosted in cloud environments, making updates and multi-location access easier in many cases.
  1. Mobile POS (mPOS) for On-the-Go Selling: Phones, handheld devices, or tablets can process transactions away from a conventional checkout counter.
  1. Tablet-Based POS Setups: Tablets can provide a flexible checkout interface for smaller stores, pop-ups, assisted selling, or specialized retail environments.

Cloud-Based vs. On-Premise Retail POS

Area Cloud-Based POS On-Premise POS
Hosting Cloud environment Store/company infrastructure
Initial setup Often lighter Usually heavier
Remote access Easier Requires internal setup
Updates Can be centrally managed Often internally managed
Multi-store visibility Generally simpler Depends on architecture
Offline needs Requires careful design Local operation can be stronger
Infrastructure responsibility Shared/provider-led Retailer-led
Scalability Often easier Requires internal capacity planning

Neither model is universally better. Retailers need to look at store connectivity, existing infrastructure, operational resilience, security, and integration requirements.

Which POS Deployment Model is Right for Your Retail Business?

Small and growing retailers may value low setup effort and centralized administration.

Multi-location retailers usually need shared product, inventory, pricing, and reporting capabilities.

Large chains may run hybrid architectures because stores need to keep trading even when external connectivity is disrupted.

Businesses with older infrastructure may prefer phased modernization rather than replacing every store component at once.

The right architecture depends on how the stores operate when everything is working—and when it is not.


Retail POS Integrations You Should Consider

E-commerce integration connects digital and store transactions.

ERP and accounting systems connect sales with finance and wider business operations.

Payment gateways handle transaction processing.

CRM systems maintain broader customer information.

Inventory and warehouse systems coordinate stock outside the immediate store.

Loyalty and marketing platforms connect purchases with rewards and campaigns.

Business intelligence systems combine POS information with wider operational data.

A retail point of sale software platform becomes considerably more useful when these systems exchange information reliably.

Why POS Integration Matters?

Without integration, employees become the integration layer.

Someone exports one file, imports another, corrects mismatches, and updates the same information in multiple places.

Connected systems reduce duplicate data entry and help keep prices, products, customers, orders, and stock synchronized.

The goal is not integration for its own sake. It is removing unnecessary breaks between retail processes.


How Much Does a Retail POS Solution Cost?

There is no responsible universal figure for a retail pos solution.

A small cloud subscription with a tablet and card reader is fundamentally different from an enterprise system supporting hundreds of stores, complex promotions, e-commerce, loyalty, ERP, and specialized hardware.

Costs may include software licenses, terminals, scanners, payment devices, printers, implementation, integrations, migration, training, support, networking, and ongoing maintenance.

Understanding the Total Cost of Ownership

Initial investment is only one part.

Recurring software fees, payment-processing charges, support, hardware replacement, integration maintenance, cloud infrastructure, and future customization all affect total cost.

As the business expands, multi-store functionality, reporting, user administration, and integration volumes can change the cost profile.

Comparing retail pos solutions therefore requires looking beyond the advertised monthly subscription.


How to Choose the Right Retail POS System?

POS

Start with business requirements.

Then consider the size of each store and the number of locations. Inventory complexity matters too: a fashion retailer, supermarket, and electronics store do not manage stock in the same way.

Check payment options and local payment requirements.

Review integrations rather than assuming every connector works at the depth you need.

Assess usability with actual store employees.

Look at reporting and whether it answers the questions managers regularly ask.

Security deserves careful review because the POS touches transactions, payments, users, and potentially customer information.

Compare total cost, not only license price.

Consider scalability and vendor support.

For small retailers searching for the best retail pos system for small businesses, simplicity may be more valuable than enterprise-level configuration. Similarly, pos systems for small business should not require a full IT department to operate.

For a larger pos system for retail business, integration and centralized control may matter much more.


What are the Common Challenges with Retail POS Software Implementation?

Data migration can expose inconsistent product codes, prices, customer records, and tax information.

Legacy integrations may be poorly documented.

Employees need training without disrupting store operations.

Hardware deployment adds a physical component that ordinary software rollouts do not have.

Cloud-connected systems need plans for internet outages.

Implementation itself can disrupt trading if cutover is badly timed.

Product, pricing, and promotion data also need careful governance. A technically successful POS cannot produce correct results from incorrect master data.

How to Avoid Common POS Implementation Problems?

Pilot before a large rollout.

Use real transaction scenarios rather than demonstration data.

Test returns, refunds, discounts, payment failures, offline operation, receipt generation, and end-of-day processes, not only straightforward purchases.

Clean product and customer information before migration.

Involve store employees early enough to identify practical workflow problems.

And always prepare a rollback or continuity plan for launch.


Retail POS Security and Data Protection

Payment information needs strong protection and appropriate handling based on the payment environment.

Customer information should be collected only where there is a clear purpose.

Role-based access can limit refunds, overrides, reports, or administrative functions.

Encryption protects sensitive data in transit and at rest where appropriate.

Integrations should use secure APIs and authentication.

Backups and recovery protect the retailer from both technical failure and operational disruption.

Software updates matter because an old POS can become a long-lived security weakness simply because replacing it feels inconvenient.

Security should cover the entire pos system and software environment, including endpoints, networks, integrations, users, and connected devices.


When Should You Replace Your Existing Retail POS System?

Frequent downtime is an obvious signal. Slow checkout is another. Poor inventory visibility becomes more serious once customers can see products online. Limited reporting leaves managers making decisions from partial information. Lack of e-commerce integration creates manual work between digital and physical channels.

Multi-location management becomes difficult when each store behaves like an independent system. Old hardware and rising maintenance costs can eventually make keeping the current platform more expensive than modernization.

The strongest signal, however, is when the POS prevents the business from doing something it now considers necessary.


Custom Retail POS System vs. Off-the-Shelf POS

Area Custom POS Off-the-Shelf POS
Workflow fit Designed around the business Based on standard product workflows
Implementation Longer Usually faster
Customization High Configuration-dependent
Integration Can be deeply tailored Depends on available APIs/connectors
Upfront effort Higher Lower
Product control Greater Vendor roadmap
Maintenance Organization/partner managed Vendor-led
Scalability Designed to requirement Depends on product architecture

A packaged retail pos solution can be entirely appropriate when the retailer’s needs are conventional.

Custom development should have a clear reason.

When Should a Retailer Consider Custom POS Development?

Custom POS development makes sense when a retailer’s operations have outgrown the flexibility of standard platforms. This is often the case when the business has complex pricing rules, unusual promotion structures, specialized inventory requirements, or several internal systems that need to exchange data in ways an off-the-shelf product cannot easily support.

It can also be useful for retailers managing multiple brands, different store formats, or customer journeys that depend on proprietary workflows. In such cases, a custom POS gives the business greater control over how transactions, inventory, promotions, customer data, and store operations come together. The decision should still be driven by a clear operational need, not by the assumption that custom software is always the better choice.


Emerging Technologies in Retail POS Systems

Retail POS technology is moving beyond billing and transaction processing. Newer systems are beginning to support areas such as AI-powered sales insights, demand forecasting, predictive inventory management, computer vision, smart checkout, and self-checkout.

Mobile POS is also becoming more relevant because it allows employees to assist customers and complete transactions away from a fixed counter. At the same time, personalized recommendations and AI-assisted engagement are helping retailers use purchase context and customer data more intelligently.

The value of these technologies depends on the problem they solve. A retailer may benefit from better demand forecasting because stockouts are frequent, or from mobile POS because customers often need assistance on the shop floor. Technology should improve the store operation rather than simply make the POS platform look more advanced.

How AI is Changing Retail POS?

AI in Retail POS

AI is making the large volume of data generated by the POS easier to interpret. Instead of looking only at historical sales reports, retailers can identify patterns across products, stores, seasons, customer behaviour, and transaction activity.

Demand models can help estimate future product requirements, while purchasing patterns can show how different products perform together or vary across locations. Recommendation engines can suggest relevant products, and anomaly detection can flag unusual transactions for further review. AI can also support inventory decisions by identifying where replenishment may be needed or where stock is building up faster than expected.

This does not remove the need for merchandisers or store managers. Their understanding of customers, stores, and local demand still matters. AI simply gives them another layer of insight to support those decisions.


How to Implement a Retail POS System

Implementing a POS system should begin with understanding how the retail business actually operates. Before selecting hardware or software, the retailer needs to define requirements across checkout, inventory, pricing, promotions, payments, customer data, reporting, and store operations. The right architecture can then be chosen based on the number of stores, connectivity, resilience requirements, and the wider technology environment.

Once the approach is clear, product, pricing, inventory, and customer data need to be prepared carefully. Integrations with e-commerce, ERP, payment gateways, loyalty platforms, inventory systems, and other applications should also be mapped early, because these connections often determine how smoothly the POS fits into the rest of the business.

Configuration should then reflect the retailer’s actual rules for taxes, discounts, promotions, permissions, and store-level processes. Testing should cover more than straightforward sales. Returns, refunds, failed payments, offline scenarios, discounts, and unusual transaction conditions all need to be checked before launch.

Employee training should focus on the tasks staff perform every day rather than every feature available in the system. After go-live, the retailer should monitor transaction performance, data accuracy, store feedback, and support issues, then improve the setup based on real usage. This process applies whether the requirement is a single pos system for retail store, a multi-location environment, or broader point of sale systems for retail business operations.


How Experion Can Help in Implementing Retail POS System?

Experion can support retail technology programs through product engineering, integration, mobile applications, store-system modernization, UX, data, and quality engineering.

In one documented ANZ retail software engagement, Experion worked across a broader retail ecosystem that included store back-office functions, mobile store operations, POS connectivity, e-commerce integration, loyalty, digital receipts, gift cards, electronic shelf labels, and retail devices.

The engagement also included POS terminals with real-time data synchronization between store and cloud environments, alongside devices such as electronic shelf labels, scales, printers, and handheld store applications.

That experience is relevant when a retailer needs to connect POS with the systems and devices around it. The approach should still begin with the retailer’s own workflows, existing estate, and modernization priorities rather than assuming every store requires the same architecture.


Conclusion: Picking a POS System That Grows With Your Business

A POS is easy to think about as the place where the transaction ends.

Operationally, it is often where several things begin.

The sale changes inventory. It creates financial information. It may update a loyalty profile. It can trigger replenishment. It becomes part of store reporting. In an omnichannel business, it may also change what customers see as available online.

That is why choosing a retail POS system should not begin and end with checkout features.

The retailer needs to think about inventory, integrations, payments, stores, reporting, resilience, customer experience, and how the platform will evolve as the business grows.

For some businesses, a straightforward packaged product will be enough. Others may need a more integrated or customized retail point of sale software environment.

Ecommerce CRM Software

Online retail generates an enormous volume of customer signals. Every product view, cart addition, checkout, return, and support ticket says something about a buyer. Most ecommerce businesses collect all of it and use very little, because the data sits in isolated systems.

Ecommerce CRM software fixes that. It brings customer identity, transaction history, behavioral data, and service interactions into a single profile, then uses that profile to drive segmentation, automation, and measurement.

This blog covers what an ecommerce CRM system is, how CRM integration with ecommerce platforms works, which features are important, how to evaluate options for crm in e commerce, and how to run an implementation people adopt in practice.


Key Takeaways

  • An ecommerce CRM unifies customer, order, behavioral, and support data into one profile. A traditional CRM built for B2B pipelines does not do this natively.
  • CRM and e-commerce integration is difficult. Field mapping, sync frequency, identity matching, and error handling decide whether the system is trusted or not.
  • The highest-return automations are usually abandoned cart recovery, post-purchase engagement, replenishment reminders, and win-back campaigns.
  • Retention economics justify most ecommerce CRM investments. Repeat purchase rate, customer lifetime value, and churn prove the case.
  • Choosing the best ecommerce CRM software is a matter of the perfect-fit and not simply comparing options.
  • Poor data quality and low user adoption sink more implementations than technical limitations do.


What is Ecommerce CRM Software?

CRM Software

Ecommerce CRM software is a customer relationship management system designed around online selling. It stores customer records like any CRM, but its data model, workflows, and reporting are built for transactional, high-volume, self-service commerce rather than long consultative sales cycles.

A traditional CRM is organized around accounts, contacts, and opportunities. Salespeople enter most of the data manually, and its value comes from pipeline visibility across a small number of high-value relationships.

A CRM for ecommerce is organized around customers, orders, products, and events. Almost all data arrives automatically through integrations, and it handles hundreds of thousands of records belonging mostly to people who will never speak to a salesperson. Its value comes from segmentation, lifecycle automation, and retention analytics.

In a traditional CRM, a rep observes and writes down information. In an ecommerce CRM system, it is a primary data source- Product views, cart events and search queries become events that can be directly used in segmentation.

How Does Ecommerce CRM Software Work?

Ecommerce CRM software works in the following way:

  • Customer interaction: Someone arrives from a search result, ad, or email, then browses, buys, asks a question, or leaves.
  • Data capture: Each interaction produces a record. The store logs sessions and orders, the marketing tool logs clicks, the helpdesk logs tickets. Without integration, these stay isolated.
  • Unified customer profile: The integration layer pushes records into the CRM ecommerce software and resolves them to one customer. Identity resolution matters here: the same person may appear as a guest checkout, a registered account, a ticket requester, and a newsletter subscriber.
  • Segmentation: Rules and models group customers by shared attributes and behavior, recalculating as behavior changes.
  • Engagement: Segments trigger campaigns. Cart abandoners get reminders. High-value customers get early access. Dormant customers get win-back offers.
  • Purchase: Conversions flow back into the CRM, feeding attribution and future targeting.
  • Retention: Post-purchase data drives the next cycle: replenishment timing, cross-sell recommendations, loyalty progression, and churn scoring.

Each stage depends on the one before it. Segmentation built on incomplete profiles produces irrelevant campaigns, and those damage the trust retention depends on. A best crm software for ecommerce can overcome all these challenges.


Why do Ecommerce Businesses Need CRM and Ecommerce Integration?

Most ecommerce teams don’t lack an access to data. They face challenge in creating a unified view between sales, marketing and operational data.

Customer Data is Spread Across Multiple Systems

  • Ecommerce platform– Accounts, orders, carts, catalog, on-site behavior.
  • Marketing tools– Email, SMS, and ad platforms, each with its own contact list.
  • Customer support– Helpdesk, live chat, and returns portal, holding tickets and sentiment.
  • Payment and order systems– Gateway records, ERP or OMS data, fulfillment status, refunds.
  • Social channels– Comments, direct messages, and social commerce orders.
  • Sales systems- For B2B commerce, quotes, contracts, terms, and rep-owned relationships.

Each holds a partial view. Marketing knows who clicked but not who returned the product. Support knows who complained but not what they spent. Decisions get made on fragments, and teams spend hours reconciling exports. A suitable crm for ecommerce business aptly addresses these issues.

Customer Interactions Become Difficult to Track

Customers move between channels without announcing it. They might read an email on their phone, research on a laptop, asks a question through chat or even make a purchase on a marketplace. Each transition breaks context when systems are separate.

The result is an agent who cannot see the customer has already emailed twice, a discount sent to someone waiting on a refund, and a rep calling a lead that just churned. Individually small, collectively corrosive, because the customer experiences it as an organization that does not pay attention. CRM integration with ecommerce makes every interaction append to the same timeline.

Personalization Becomes Harder at Scale

Personalization is simple with a hundred customers and impossible by hand with a hundred thousand. Segments change constantly: a first-time buyer becomes a repeat customer on Tuesday and a lapsed one three months later, so exported lists are stale immediately. Meaningful segments also multiply fast, as category affinity, purchase frequency, price sensitivity, and lifecycle stage combine into hundreds of variants. A crm for e commerce business handles this by making segments dynamic and letting workflows respond to events as they happen.

Customer Retention Requires More Than Transactions

Acquisition costs have risen in most categories, which puts weight on what happens after the first order.  The best crm for ecommerce understands the importance of customer retention.

  • Repeat purchases require knowing what someone bought and when they reorder.
  • Loyalty requires cumulative value tracked across channels.
  • Re-engagement requires spotting the point where silence becomes unusual for that customer.
  • Upselling requires knowing what they already own, and cross-selling requires product affinity data.


Ready to connect your store, marketing stack, and support desk?
Talk to Experion about an ecommerce CRM integration roadmap built around your existing systems


Key Features of CRM Software for Ecommerce

Feature lists look similar across vendors. What matters is how deeply each capability is integrated into commerce data.

Unified Customer Profiles

  • Contact information including all known identifiers and addresses
  • Purchase history at line-item level, not just order totals
  • Communication history across email, SMS, chat, phone, and social
  • Preferences covering categories, channels, frequency, and consent
  • Customer lifecycle stage such as prospect, first-time buyer, active, at-risk, or lapsed

A profile is only useful if it is trusted. Identity resolution, deduplication, and clear rules about which system owns which field decide whether people believe what they see.

Customer Segmentation

  • First-time buyers, who need onboarding and a reason to return.
  • Repeat customers, who respond to loyalty mechanics and early access.
  • High-value customers, who justify concierge service and exclusive offers.
  • Inactive customers, who need win-back sequences before being written off.
  • Cart abandoners, who need timely, low-friction reminders.
  • Product-category buyers, who receive relevant cross-sell and restock messaging.

The strongest implementations pair rule-based segments with predictive ones such as churn risk or predicted lifetime value.

Sales Pipeline Management

Direct-to-consumer stores use this lightly. On the other hand, B2B ecommerce, wholesale, and distribution leverage it on a greater basis.

  • Lead tracking for quote requests and trade applications
  • Opportunity management for bulk orders, contracts, and renewals
  • Follow-ups triggered by quote age, cart value, or account inactivity
  • Sales forecasting blending pipeline with recurring self-service revenue

Marketing Automation

  • Email campaigns for promotions, launches, and newsletters
  • Customer journeys that branch on behavior rather than running linearly
  • Re-engagement campaigns triggered by inactivity thresholds
  • Abandoned-cart workflows with sensible delays and frequency caps
  • Post-purchase communication covering confirmation, shipping, usage guidance, and reviews

Check whether automation reads live commerce data at send time. A recommendation block pulling stock-aware data beats one built on a stale export.

Order and Purchase History

Order data supplies context that improves every conversation. An agent seeing the order, shipment, and return history resolves in one exchange instead of five. Depth matters: order totals tell you how much someone spent, while line-item detail tells you what they bought, which drives replenishment timing and relevant cross-sells.

Customer Service Management

  • Customer inquiries with channel of origin
  • Complaints with severity and resolution status
  • Returns including reason codes, among the most useful product signals a retailer collects
  • Support history visible to every team, so marketing does not promote to someone mid-dispute
  • Service tickets with SLA tracking and escalation paths

Analytics and Reporting

  • Customer lifetime value, ideally by acquisition cohort and channel
  • Repeat purchase rate over defined windows
  • Customer acquisition cost (CAC), compared against lifetime value
  • Conversion rate by segment and journey
  • Churn, defined by a threshold suited to your purchase cycle
  • Average order value, tracked alongside discount depth

Group analysis differentiates adequate reporting from useful reporting. It can indicate customer behavior, which in turn, determines where the budget goes.

Workflow Automation

With e-commerce relationship management, the following workflows can be automated.

  • New customer onboarding sequences and account setup tasks.
  • Post-purchase follow-up, including satisfaction checks and review requests.
  • Renewal reminders for subscriptions and service contracts.
  • Reorder notifications timed to product consumption cycles.
  • Win-back campaigns triggered by inactivity relative to a customer’s own pattern.


Benefits of Ecommerce CRM Solutions for Online Businesses

Benefits CRM Software

Creates a 360-Degree View of Customers

Combining identity, purchase, behavioral, and service data produces context no single system holds. A customer with nine orders and one quickly resolved return is a different person from one with nine orders and four unresolved complaints, even though revenue looks identical in a sales report.

Enables Personalized Customer Experiences

  • Product recommendations based on real purchase and browse history, not generic bestsellers
  • Targeted promotions calibrated to price sensitivity, so you stop discounting to people who would pay full price
  • Personalized emails reflecting owned products, category affinity, and lifecycle stage
  • Relevant offers timed to replenishment windows or observed intent

Improves Customer Retention

The CRM identifies customers drifting toward inactivity before they are gone. Signals include lengthening gaps between orders, declining engagement, smaller baskets, and unresolved service issues.

Supports Cross-Selling and Upselling

Purchase history plus behavior reveals which suggestions are plausible.

  • For example, a consumer who bought a camera body and has viewed lens pages since is a strong candidate for a lens offer.
  • Someone who just bought the premium tier should not receive an upgrade prompt.

Both depend on the CRM knowing what a customer already owns.

Improves Sales and Marketing Alignment

With customer data, campaigns, leads, and sales activity in one system, handoffs stop leaking. Marketing sees which campaigns produced customers who actually purchased, sales sees the content a lead engaged with, and both work from shared definitions of a qualified lead and an active customer.

Reduces Manual Work Through Automation

Tagging new customers, routing tickets by category and value, triggering post-delivery follow-ups, flagging high-value accounts, and generating recurring reports can all run unattended. The time saved is real, but consistency is the bigger gain.

Provides Better Customer Insights

Centralized data answers questions fragmented data cannot. Which channel produces the highest two-year value? Which first purchase predicts a five-order customer? Which return reasons correlate with churn? These drive inventory, budget, and product decisions.


Experion is well positioned to design ecommerce CRM systems around these outcomes, combining platform selection, custom integration engineering, and data migration into a single delivery track.


CRM for Online Store vs. Traditional CRM

Dimension CRM for Online Store Traditional CRM
Primary objective Retention and lifetime value Pipeline visibility and deal closure
Core records Customer, order, product, event Account, contact, opportunity
Sales motion Self-service, high volume, low touch Rep-led, low volume, high touch
Data entry Automated through integrations Largely manual by sales users
Data volume Tens of thousands to millions Hundreds to thousands of accounts
Key data type Transactional and behavioral Relationship and conversational
Segmentation Dynamic, behavior-driven Static lists, territories, tiers
Automation focus Lifecycle journeys, triggered messaging Task reminders, stage-based alerts
Core metrics CLV, repeat rate, churn, AOV Win rate, cycle length, forecast accuracy
Integration needs Deep, real-time to storefront and OMS Email, calendar, marketing automation
Typical users Marketing, service, ecommerce ops Sales reps and managers


CRM Integration with Ecommerce: How They Work Together?

What Data Can Be Shared Between CRM and Ecommerce?

  • Customer records: Profiles, addresses, account status, and consent flags.
  • Orders: Headers and line items, status changes, fulfillment events, refunds, returns.
  • Products: Catalog data, categories, pricing, inventory status, and personalization attributes.
  • Cart activity: Additions, removals, and abandonment events with contents and timestamps.
  • Transactions: Payment outcomes, methods, chargebacks, and subscription billing events.
  • Customer behavior: Sessions, page and product views, searches, and wishlist actions.
  • Marketing interactions: Sends, opens, clicks, unsubscribes, and attribution data.

Not everything should flow both ways. Orders usually move one way into the crm, while preference changes need to flow back so the storefront reflects them.

How Ecommerce CRM Development and Integration Works?

A typical architecture:

Ecommerce platform → integration/API layer → CRM → marketing, sales, and support workflows.

The platform emits events and exposes APIs. The integration layer subscribes, transforms payloads into the CRM schema, resolves identity, and handles retries. Downstream workflows consume the unified record and write interaction data back.

CRM Integration with Ecommerce Platforms

  • Native integrations: Prebuilt connectors. Fastest and cheapest, but limited to the fields the vendor chose to support.
  • APIs: Direct development against both platforms. Full control over mapping and logic, at the cost of maintaining code.
  • Middleware: Integration platforms providing connectors, transformation, and monitoring out of the box, with recurring licensing cost.
  • Webhooks: Event-driven pushes that keep data current without polling. Essential where latency matters.
  • Custom integrations: Purpose-built services for non-standard platforms, complex B2B pricing, legacy ERP, or data residency requirements.

Most implementations combine these: a native connector for basics, webhooks for time-sensitive events, and custom code for the logic that makes the business distinctive. If you’re searching for the best CRM for ecommerce business growth, prioritize platforms that integrate seamlessly with your online store and payment systems.


What Can You Automate When Using Ecommerce with CRM?

New Customer Follow-Up

Trigger a welcome sequence on first order that confirms the purchase, sets delivery expectations, and offers help. Tag the customer, set the lifecycle stage, and schedule a second-purchase nudge.

Abandoned Cart Recovery

Usually the highest-yield automation. Two or three messages starting within hours and spread over several days, with cart contents pulled live so out-of-stock items are not promoted.

Post-Purchase Engagement

Delivery confirmation, usage guidance, a satisfaction check, and a review request timed for after the customer has used the product. Suppress the review request when a support ticket is open.

Repeat Purchase Reminders

For consumables, calculate reorder timing from that customer’s own history rather than a category average, and send a one-click reorder prompt shortly before they run out.

Customer Win-Back Campaigns

Define inactivity relative to each customer’s cadence. Stage the sequence: soft re-introduction, category update, then a stronger incentive. Move non-responders to a low-frequency list to protect deliverability.

Cross-Selling and Upselling

Trigger recommendations from purchase and browse data, filtered against what the customer owns and current stock. Timing beats volume: one well-timed suggestion outperforms a weekly recommendation email.

Customer Support Escalation

Route tickets by category, sentiment, order value, and tier. Escalate automatically as SLA thresholds approach, when a high-value customer opens a second ticket on one order, or when a return is flagged defective.

Loyalty and VIP Customer Journeys

Track cumulative value and trigger tier changes automatically. Notify customers when they progress, unlock benefits without requiring a request, and flag top-tier accounts for human outreach.


Not sure which workflows to automate first?
Experion can run a CRM automation assessment that maps your customer journey and ranks automations by expected return


How to Choose the Best Ecommerce CRM Software?

Evaluate Ecommerce Integration Capabilities

Ask which objects and fields the native connector covers, whether it supports real-time events or only batch syncs, and what happens when a sync fails. Request API rate limit documentation.

Check Customer Data Management

Inspect the data model. Can it store line-item order detail natively, or does that need custom objects? How does it deduplicate and merge? Can it link guest checkouts to registered accounts, add computed attributes without a developer, and export everything if you leave?

Evaluate Automation

Look at trigger types, branching logic, frequency capping, suppression rules, and whether workflows act on live commerce data. Test whether a non-technical marketer can build a journey, because a system needing engineering for every change will not be used.

Consider Analytics and Reporting

Check for cohort analysis, lifetime value calculation, retention curves, and segment-level performance. Confirm you can build custom reports without vendor services and export raw data.

Assess Scalability

Model three years of growth in records, events, and message volume. Ask how pricing changes at that scale, since contact-based pricing becomes punishing as lists grow.

Review Security and Data Governance

Verify certifications, encryption in transit and at rest, role-based access control, audit logging, data residency options, and support for GDPR, CCPA, and similar regimes.

Consider Total Cost of Ownership

Licensing is the visible cost. Budget also for integration development, data migration, configuration, training, administration, middleware subscriptions, and support.

Best CRM Software for Distributors with Built-In Ecommerce

Distributors need capabilities consumer tools rarely offer: account hierarchies linking buying locations to a parent organization, contract and customer-specific pricing, quote-to-order workflows, credit terms and limits, approval routing, standing orders, and ERP integration. The self-service portal and the field sales team must read the same record, or the two channels will contradict each other in front of the customer.


Common Challenges with Ecommerce CRM Implementation

Poor Data Quality

Duplicates, inconsistent formatting, outdated addresses, and missing consent flags migrate straight into the new system and destroy trust immediately. Profile the data first, clean it, and set validation rules at entry so the problem does not return.

Integration Complexity

Underestimating integration is the most common planning error. Legacy systems, custom pricing logic, and multi-region setups all add effort. Build it early, test against production-scale data, and treat monitoring and reconciliation as deliverables.

Data Silos

A CRM becomes one more silo when teams keep working in their own tools, usually because it is harder to use than what it replaced or because only some systems were connected. Define which system is authoritative for each data type. The right CRM software ecommerce teams use should connect customer, order, marketing, and support data in one place.

Low User Adoption

If the system is slow, cluttered, or disconnected from daily work, people revert to spreadsheets. Involve future users during configuration, remove fields nobody needs, train by role with real scenarios, and measure adoption in the first quarter.

Over-Automation

Too many automated messages annoy customers, damage deliverability, and drive unsubscribes that cost more than the campaigns earned. Apply global frequency caps, suppress customers with open service issues, and retire sequences that stop performing.

Lack of a Clear Ecommerce CRM Strategy

Implementations that start with software selection instead of business objectives produce expensive, underused systems. Define measurable outcomes first. An ecommerce CRM strategy naming two or three specific goals beats one aiming to improve everything.


Key E-commerce CRM Metrics to Track

Metric What It Tells You
Customer Lifetime Value Long-term customer value
Customer Retention Rate Ability to retain customers
Repeat Purchase Rate Repeat buying behavior
Average Order Value Revenue per transaction
Customer Acquisition Cost Cost of acquiring customers
Churn Rate Customer loss
Conversion Rate Effectiveness of sales journeys
Customer Engagement Rate Interaction with campaigns
Cart Abandonment Rate Lost purchase opportunities


How to Implement an Ecommerce CRM System?

Step 1: Define Business Objectives

Name the outcomes and attach numbers: improve retention, increase repeat purchases, improve sales visibility, automate marketing, centralize customer data. “Increase repeat purchase rate from 22% to 30% within twelve months” guides configuration decisions.

Step 2: Map Customer Data Sources

Inventory every system holding customer information, recording what data it owns, its volume, quality, API capabilities, and administrator. This map defines integration scope and usually surfaces two or three systems.

Step 3: Select the CRM Platform

Score candidates against the criteria above, weighted by your priorities. Run a proof of concept (POC) with your own data rather than the vendor’s demo set, involve daily users, and check the maturity of the connector for your platform version.

Step 4: Plan Ecommerce CRM Integration

Specify before building:

  • Data fields: Every field, its source, destination, and transformation rules.
  • Sync frequency: Real-time or batch, decided per object based on how the data is used.
  • Integration method: Native connector, API, middleware, webhook, or custom code per connection.
  • Data ownership: The system of record for each field and the rule applied on conflict.
  • Error handling: Retry logic, dead-letter queues, alert thresholds, and scheduled reconciliation.

Step 5: Clean and Migrate Customer Data

Profile existing data, then deduplicate using defined matching rules, normalize addresses, phone numbers, and names, standardize country and currency codes, and archive what you do not need. Validate consent carefully, since migrating contacts without documented consent creates regulatory exposure.

Step 6: Configure Workflows and Automation

Start with a few high-value use cases rather than building everything at once. Abandoned cart recovery, welcome sequences, and post-purchase follow-up deliver the fastest measurable return.

Step 7: Train Teams

Train by role with realistic scenarios. Sales needs pipeline and account workflows, marketing needs segmentation and journey building, customer service needs the unified profile and ticket handling, operations needs order data and reporting. Name an internal owner and schedule a refresher after the first month, once real questions have emerged.

Step 8: Measure Performance

Set a baseline before launch so improvement can be demonstrated. Review KPIs monthly, retire automations that underperform, and revisit segment definitions as the customer base changes. Treat the e-customer relationship management as a system that is continuously tuned, not a project that finishes.


Want to explore what’s next in ecommerce?
Discover how AI, digital commerce, and connected technologies can help your business create smarter, more seamless ecommerce experiences
Talk to Experion Technologies about your ecommerce transformation journey


Future Trends: AI and Ecommerce CRM

Future Ecommerce CRM Software

  • Predictive analytics for customer behavior: Models trained on transaction and behavioral history are moving from reporting what happened to estimating what will happen: who is likely to churn, what a new customer will be worth and when someone will reorder.
  • AI-driven personalization: Recommendation and content selection increasingly happen at send time rather than being fixed when a campaign is built. Generative models produce message variants per segment and summarize a customer’s history into a brief an agent reads in seconds.
  • Conversational commerce and chat-based CRM: Assistants embedded in storefronts and messaging channels handle order status, returns, and product questions while writing every exchange back to the profile. The same interface is appearing internally, letting staff query customer data in plain language.


Conclusion- Choosing an Ecommerce CRM that Fits Your Business

No single platform is the best ecommerce CRM software for every business. The right choice depends on your ecommerce platform, order volume, catalog complexity, team, and the problems you are solving.

A high-volume direct-to-consumer brand should weight automation and scalability. A distributor running B2B ecommerce should weight account structures, pricing logic, and ERP integration. A growing store on a mainstream platform should weight integration depth and ease of use, because implementation capacity is the real constraint.

Whichever platform you choose, the outcome is decided less by the software than by integration quality, the data going into it, and whether your teams adopt it.

Sales Management Software

Why Sales Teams Need Better Management?

Sales teams do not usually struggle because nothing is happening. Quite the opposite.

A rep might speak to five prospects before lunch, move one opportunity forward, postpone another, receive a referral, send two proposals, and make a note to follow up with somebody next Thursday. Multiply that across ten or fifty people and it becomes surprisingly difficult to answer a basic question: what is actually happening in the pipeline today?

Spreadsheets can work for a while. So can inbox folders, personal reminders, and weekly pipeline meetings. The problem begins when those systems start depending on individual memory.

One rep updates the spreadsheet on Friday. Another keeps detailed notes in email. A manager maintains a separate forecast. Customer information lives in different places, and nobody notices a missed follow-up until the prospect has already gone quiet.

Sales management software brings those activities into one working environment. Leads, opportunities, conversations, targets, meetings, forecasts, and sales activity become easier to follow without asking every salesperson to reconstruct the story from memory.


Key Takeaways

  • Sales management software creates one view of leads, deals, activities, and performance.
  • Automation is most useful when it removes routine administration.
  • CRM and sales management overlap, but they solve slightly different problems.
  • Pipeline visibility is only useful when salespeople keep the underlying information current.
  • Integrations prevent sales teams from repeatedly entering the same information.
  • AI is beginning to interpret sales data, not merely report it.
  • The right system depends on the sales process, not the length of the feature list.


What is Sales Management Software?

Sales Management

For anyone searching what is sales management software, it is software used to organize and manage the people, activities, opportunities, targets, and information involved in selling.

A sales management system might capture a lead from a website, assign it to a representative, record meetings and emails, move the opportunity through stages, remind the rep about a follow-up, and eventually include the deal in a forecast.

That makes it broader than a simple contact database.

The term sales software is often used for almost anything associated with selling: prospecting tools, call software, quoting systems, email platforms, analytics products, or CRM. Sales management software is concerned more specifically with running the sales process and understanding how the team is performing.

Sales Management Software vs. CRM vs. Sales Automation Software

These categories overlap enough that they are often marketed as if they were interchangeable. They are not quite the same.

Software Where it is usually strongest
Sales management software Pipeline, opportunities, activities, targets, forecasts, and team visibility
CRM software Customer and account relationships across a broader lifecycle
Sales automation software Repetitive tasks, triggers, reminders, routing, and workflow automation
Sales order management software Orders, pricing, fulfillment, order status, and post-sale processing
Sales enablement software Sales content, playbooks, learning, and seller resources
Sales performance management software Quotas, territories, incentives, performance, and compensation

A business may use more than one.

For example, sales order management software can take over once the customer has committed to buying. A sales performance management software platform might separately handle quotas, incentives, and rep performance.

Sales automation software, meanwhile, is usually less about managing the complete sales operation and more about removing repetitive steps inside it.

Three Pillars of Modern Sales Management

Most modern sales environments need three things to work well.

The first is visibility. Managers and reps should know where opportunities stand without waiting for a weekly meeting.

The second is consistency. Similar opportunities should not be handled through entirely different processes simply because two people have different habits.

The third is judgment supported by data. Software should help people understand what deserves attention, without pretending that a dashboard knows the customer better than the salesperson does.


How Does Sales Management Software Work?

There is no universal sales process, but most systems follow a recognizable journey from first contact to outcome.

Step 1: Lead Capture

Leads can arrive through website forms, email campaigns, events, social media, referrals, paid campaigns, and third-party sources.

A sales lead management software workflow brings those leads together instead of leaving some in a marketing platform and others in individual inboxes.

Step 2: Lead Qualification

Not every enquiry deserves the same level of attention.

Qualification can consider customer fit, buying intent, engagement, budget, need, timing, or any other criteria relevant to the business.

Good qualification should save sales time. It should not become an elaborate scoring exercise that everybody ignores.

Step 3: Lead Assignment

Once qualified, the lead needs an owner.

Assignment might depend on geography, industry, account size, product, availability, or existing relationships.

Organizations working with geographic sales teams may also use sales territory management software to manage boundaries, account ownership, capacity, and regional performance.

Step 4: Sales Engagement

Calls, meetings, emails, follow-ups, notes, and tasks create the history of the relationship.

Recording them gives the salesperson useful context later and makes the account understandable if another colleague needs to become involved.

Step 5: Opportunity Management

Once genuine buying potential exists, the opportunity moves through the sales pipeline.

Stages should reflect how the business actually sells. If every opportunity remains permanently stuck at “70% probability,” the problem is not the dashboard.

Step 6: Proposal and Negotiation

The system can record proposals, pricing discussions, decision-makers, commercial questions, and next steps.

This becomes particularly useful in B2B sales, where several people may influence the decision.

Step 7: Deal Closure

Closed deals are recorded as won or lost.

Loss reasons matter. Over time they can reveal whether opportunities are being lost because of price, timing, competition, product fit, or poor qualification.

Step 8: Reporting and Forecasting

Managers can then look at pipeline value, conversion rates, sales velocity, rep performance, stage movement, and forecasted revenue.

Forecasting becomes more useful when it reflects actual opportunity behavior rather than simply the optimism of the account owner.


What are the Key Features of Sales Management Software?

Lead and contact management creates a shared record of the people and organizations the sales team is engaging with.

Pipeline and deal tracking shows where opportunities sit and whether they are progressing.

Opportunity management brings together value, expected close date, stakeholders, products, activities, and probability.

Activity tracking records calls, emails, meetings, and tasks. Follow-up automation helps sellers avoid losing track of routine next steps.

Forecasting gives managers a view of potential revenue. Sales analytics makes it easier to understand conversion, velocity, pipeline movement, and performance over time.

Quota and target management adds another layer for organizations managing individual, team, regional, or product goals.

Email and calendar integration reduce the amount of information salespeople have to enter manually.

Workflow automation can handle assignments, approvals, reminders, notifications, and selected administrative steps.

Mobile accessibility matters when sellers spend significant time with customers rather than at desks.

Dashboards should be configurable because a rep and a head of sales rarely need the same information.

Role-based permissions are equally important. Not every salesperson necessarily needs access to every commercial discussion, customer account, or regional pipeline.

More advanced sales management tools now add lead scoring, meeting summaries, deal-risk indicators, and AI-generated recommendations.


Why Businesses Need Software for Sales Management?

Using software for sales management becomes valuable when the sales operation is too complex to understand through informal updates alone.

The point is not simply to digitize a spreadsheet. It is to create a working sales process where information moves with the opportunity.

What are the Benefits of Using a Sales Management Software?

Sales Management Software

Salespeople can spend less time preparing manual reports or searching for information.

Managers gain better pipeline visibility.

Automated reminders reduce missed follow-ups, while common processes make it easier to identify opportunities that are sitting still.

Forecasting can become more consistent because decisions are based on current pipeline information rather than occasional updates.

Customer experience can improve too. When account history is available, prospects are less likely to repeat information every time another colleague enters the conversation.

Centralized data also makes longer-term analysis possible. Teams can see which lead sources convert, which stages create delays, how long opportunities remain open, and where revenue tends to stall.


Sales Management Software vs. Traditional Sales Management

Area Traditional Approach Sales Management Software
Lead tracking Spreadsheets/manual records Centralized system
Follow-ups Manual reminders Automated reminders
Pipeline visibility Limited Real-time
Reporting Manual Automated
Forecasting Often subjective Data-driven
Team monitoring Time-consuming Dashboard-based
Customer data Scattered Centralized
Workflow Manual Automated
Decision-making Historical/manual Real-time insights

Traditional methods are not necessarily bad. They simply become harder to maintain when volume and complexity increase.

A spreadsheet is perfectly capable of holding 200 opportunities. It is much less capable of reminding 20 salespeople what to do next, recording every conversation, enforcing access controls, and connecting the result with marketing and finance.


Types of Sales Management Software

  1. CRM-Based Sales Management Software combines opportunity management with a broader customer relationship record.
  2. Sales Force Automation Software focuses on repetitive sales processes such as lead routing, task creation, reminders, and activity capture.
  3. Sales Pipeline Management Software focuses on opportunities and how they move towards closure.
  4. Sales Performance Management Software concentrates on targets, quotas, incentives, and seller performance.
  5. Sales Analytics and Forecasting Software provides deeper interpretation of pipeline and revenue data.
  6. Enterprise Sales Management Platforms support larger organizations with multiple teams, territories, products, and complex permissions.
  7. Industry-Specific Sales Management Software adapts workflows to particular sectors or buying processes.

Some people also search for sales managing software when looking for these platforms. Whatever term is used, the practical requirement should drive the decision.


Who Can Benefit From Sales Management Software?

Small Businesses

Small companies often start with spreadsheets because they are simple and inexpensive.

Sales management software for small business becomes more useful when leads increase and the team can no longer rely on one person remembering every conversation.

The same principle applies when choosing sales software for small business: ease of use may matter far more than enterprise features.

Mid-Sized Businesses

Mid-sized organizations typically need clearer reporting, more structured workflows, team management, automation, and better forecasting.

They also need a system that can grow without becoming difficult to administer.

Large Enterprises

Large businesses deal with complexity of another order: multiple sales teams, regions, products, languages, account structures, and customer databases.

Integration, advanced permissions, analytics, territory management, and governance become more important.

A sales database management software approach can also help maintain consistency when customer information is spread across a large organization.

B2B Sales Organizations

B2B sales often takes time.

A deal may involve users, procurement, finance, legal teams, technical specialists, and senior decision-makers. The buying process can pause for weeks and start again with another stakeholder.

Software helps retain that context.

Field Sales Teams

Field representatives need mobile access to contacts, meetings, opportunities, tasks, and account history.

Real-time updates are particularly helpful when people are travelling between customers and cannot wait until the end of the day to update the system.


Experion’s documented mobility capabilities include Sales Force Automation and Mobile Sales & Service, alongside mobile application, UX, and platform engineering capabilities.


Common Sales Challenges That Sales Management Software Solutions Can Solve

Some problems are obvious: a lead was forgotten or a salesperson missed a follow-up.

Others are less visible.

A manager may believe the pipeline is strong because the total value looks impressive, even though many opportunities have not moved for months.

Forecasts may change dramatically because sellers use different definitions of what “likely to close” means.

Representatives may spend Friday afternoons preparing reports instead of selling.

Customer information may sit across personal notes, shared drives, and email threads.

Sales management software solutions can bring these activities into one process. They cannot solve weak sales strategy, but they make operational gaps easier to see.


How Sales Management Platform Supports the Sales Funnel?

During Awareness, leads may enter from campaigns, search, events, and other sources.

At Interest, engagement data can show what the prospect has explored.

During Consideration, a sales management platform gives the salesperson a place to manage stakeholders, requirements, meetings, and opportunity information.

At Decision, proposals, negotiations, approvals, and commercial questions become more important.

At Conversion, the sales record may connect with orders, onboarding, finance, or delivery.

During Retention, customer history can inform renewals, cross-sell conversations, and future account planning.

The buyer will not always move neatly from one stage to the next. Good software should tolerate that reality.


How to Choose the Best Sales Management Software?

Start by ignoring the software for a moment.

Map how your team actually sells. Where do leads come from? Who qualifies them? How are opportunities assigned? Which approvals slow deals down? What does management genuinely need from forecasting?

Then look for software that supports that process.

Usability matters enormously. A powerful system filled with stale information is less useful than a simpler system people maintain properly.

Evaluate automation, integrations, analytics, mobile access, customization, security, and scalability.

Searches for the best sales management software or best online sales management software can help create a shortlist. They cannot decide which platform fits your organization.


Why Demand for Custom Sales Management Software Increasing?

Off-the-shelf sales platforms cover most common workflows very well.

The case for custom sales management software appears when the sales process itself is unusual.

Perhaps pricing needs several internal approvals. Territories follow a proprietary structure. Opportunities involve specialist technical teams. Lead assignment depends on several internal systems. Or sales workflows are deeply connected to a product or marketplace that generic software cannot easily accommodate.

Custom development gives the organization more control.

It also means owning more responsibility for maintenance, security, upgrades, and future changes.

What Custom Sales Management Software Cost?

There is no sensible universal answer.

A small internal tool and a global enterprise platform can both be called custom sales management software while having completely different cost structures.

Cost depends on the number of users, workflows, integrations, analytics, mobile requirements, AI, security, migration, infrastructure, and ongoing support.

Discovery should come before pricing.


Cloud vs. On-Premises Sales Management Software

Area Cloud On-Premises
Hosting Cloud/provider environment Organization’s infrastructure
Setup Usually quicker Usually heavier
Remote access Easier Requires internal setup
Updates Often provider-managed Organization-managed
Infrastructure control Shared Greater internal control
Scaling Generally easier Requires capacity planning
Maintenance burden Lower internally Higher internally

Online sales management software is common because modern sales teams often work across offices, homes, and customer locations.

On-premises systems still make sense for some organizations where internal infrastructure, integration, or regulatory requirements justify them.


How to Implement Sales Management Software Successfully?

Phase 1: Requirement Gathering

Talk to the people who actually use the process.

Managers will describe reporting needs. Salespeople will tell you where the day-to-day friction really sits.

Phase 2: Process Mapping

Document lead capture, qualification, assignment, pipeline movement, approvals, forecasting, and handoffs.

Phase 3: Software Selection

Evaluate the software against those workflows rather than relying entirely on vendor demonstrations.

Phase 4: Data Migration

Do not move years of duplicate and outdated data simply because it exists.

Clean it first.

Phase 5: Integration

Connect CRM, ERP, marketing, communications, support, and other systems that genuinely need to exchange information.

Phase 6: Customization

Configure stages, dashboards, fields, permissions, and workflows without making the system unnecessarily complicated.

Phase 7: Testing

Test real scenarios, including deals that do not follow the perfect path.

Phase 8: Training

Training should show people how the system helps with their job, not simply where every button is located.

Phase 9: Deployment

Give users a clear support route when problems appear.

Phase 10: Optimization

Once the system is live, review where people still use spreadsheets or manual workarounds. Those usually reveal what needs attention next.


How AI is Changing Sales Management?

For years, sales systems mostly told people what had already happened.

AI is beginning to shift that.

Predictive lead scoring can estimate which leads resemble previous successful opportunities.

Forecasting models can consider more than the salesperson’s stated probability.

Automated activity capture reduces administration.

Conversation analysis can extract themes from sales calls, while meeting summaries can record decisions and next actions.

AI can identify deals that appear to be losing momentum.

It can recommend a next action, draft an email, flag possible churn, or suggest cross-sell opportunities.

The distinction is useful:

Traditional software: “Here is your sales data.”

AI-powered software: “Here is what may deserve your attention.”

The word may matters. AI can recognize patterns. It does not know everything happening inside the customer’s organization.


Sales Management Software Integrations

Sales information becomes more valuable when it connects with the rest of the business.

CRM provides account and relationship context.

ERP connects sales with products, pricing, inventory, finance, and fulfillment.

Marketing automation provides campaign and lead-engagement information.

Customer-support systems reveal service history.

Communication tools connect calls, email, and meetings with the account.

Business-intelligence tools support deeper analytics.

Payment and e-commerce platforms can connect selling with actual transactions.

Good business sales software should make these relationships easier to manage without creating another layer of duplicate information.


Security and Compliance Considerations in a Sales Management Software

Sales systems often contain commercially sensitive information: customer contacts, proposals, prices, negotiation notes, contracts, and forecasts.

That information needs sensible protection.

Encryption helps protect stored and transmitted data.

Role-based permissions limit access.

Authentication should be appropriate to the sensitivity of the information.

Audit trails provide a history of important actions and changes.

Backups and disaster recovery protect continuity.

APIs and connected systems require security because integrations can introduce additional access routes.

Privacy controls matter when personal information is stored.

Regulatory requirements vary by country and industry, so organizations should evaluate the rules that actually apply rather than treating compliance as one generic checklist.


Future Trends in Sales Management Software

Sales Management Software

  • AI-First Sales Platforms will make AI part of everyday workflows.
  • Predictive Sales Intelligence will improve risk and opportunity analysis.
  • Autonomous Sales Workflows may handle selected administrative activities.
  • Lead and Deal Scoring will use broader behavioral signals.
  • Guided Selling will help sellers navigate complicated offerings.
  • CPQ Integration will connect configuration, pricing, and quoting more closely with the pipeline.
  • Autonomous Sales Agents may support research and low-risk administrative tasks.
  • Conversational AI will let users query sales information more naturally.
  • Real-Time Sales Analytics will reduce dependence on periodic reporting.
  • Hyper-Personalized Customer Engagement will use account context more intelligently.
  • Buyer-Led Digital Sales Rooms (DSRs) can give buyers and sellers a shared digital environment.
  • Revenue Intelligence will connect activity data more closely to commercial outcomes.
  • No-Code/Low-Code Customization will allow business teams to adjust processes more easily.
  • Mobile-First Sales Operations will continue to matter for distributed teams.
  • Deeper CRM + ERP Integration will connect selling with fulfillment and finance.
  • AI-Powered Forecasting will become more contextual.
  • Automated Sales Coaching may use calls, activities, and performance patterns to support managers.


When Should a Business Invest in Sales Management Software?

The answer is usually visible in the workarounds.

Sales teams are growing. Leads are increasing. Spreadsheets are becoming harder to maintain.

Follow-ups are being missed.

Managers need several conversations before they understand the pipeline.

Forecasts change dramatically every week.

Reporting takes hours.

Customer information is spread across several places.

Representatives spend too much time entering or locating data.

Different business systems now need to exchange sales information.

When those problems begin consuming meaningful time or affecting revenue opportunities, a sales management system becomes easier to justify.


Conclusion: Turn Sales Data Into Sales Growth

Sales teams already generate enormous amounts of information.

Every enquiry, meeting, call, proposal, objection, lost deal, and signed contract says something about how the organization sells.

The challenge is that much of that information disappears into individual habits.

A useful sales management software environment gives the business enough structure to retain that knowledge without turning selling into data entry.

Salespeople can see what needs attention. Managers can understand the pipeline without interrogating every rep. Leadership gets a more defensible view of likely revenue.

That is where the value lies, not in having more sales data, but in being able to use it while the opportunity still matters.

Cloud Advisory Services

Most enterprises are no longer deciding whether to move to the cloud. They are grappling with rising costs, stalled migrations, legacy applications, security gaps, and outdated roadmaps. These are not simply technology problems; they are decisions made during planning, portfolio analysis, architecture, and operating model design.

Cloud advisory services help organizations make those decisions deliberately, using evidence instead of assumptions. This blog explains what cloud advisory services include, when you need them, how cloud transformation works, what engagements cost, and how to choose the right advisory partner.


Key Takeaways

  • Cloud advisory services guide decisions regarding cloud adoption. It encompasses overall strategy, readiness, migration, architecture, security, cost, and modernization.
  • Most cloud engagements vary in scope and cost. Timelines range from short, focused assessments to ongoing monthly retainers for continuous advisory support.
  • A cloud advisory consultant connects technical decisions to business outcomes. This involves cost, risk, speed, and scale. They can treat cloud advisory services as more than a technical exercise.
  • Cloud advisory and cloud consulting overlap but aren’t the same: advisory shapes the decision, consulting executes it.
  • Most companies don’t need every type of engagement at once – matching the engagement to the actual problem (cost, risk, migration, ongoing governance) avoids paying for scope that isn’t required.


What is Cloud Advisory Services?

Cloud Advisory Services

Cloud advisory services are structured consulting engagements that help an organization decide what to do with the cloud — before, during, and after implementation. They cover assessing the current environment, defining a target state, selecting workload-specific migration and modernization strategies, modeling costs and business cases, designing governance and operating models, and sequencing it into a roadmap that finance and leadership can approve.

The distinction that matters most is between advisory and delivery. Delivery work moves systems, writes code, and configures platforms. Advisory work determines which systems to move, in what order, using which approach, at what cost, and with what risks accepted. Delivery answers “how.” Advisory answers “what, why, when, and whether.”


Why do Businesses Need Cloud Advisory Services?

Shifting to the cloud is not just an IT decision but a business decision. It has long term financial and operational consequences. Without the right guidance, organizations often overspend, under-migrate, or build cloud environments that don’t align with their business goals. This is where cloud advisory services become essential. It helps companies make informed, structured decisions before, during, and after cloud adoption.

Cloud decisions can become expensive without a strategy

Over-provisioned instances, the wrong pricing tier, services that don’t scale the way anyone expected- are all expensive mistakes. Cloud advisory consultants notice that pattern early, tying architecture and purchasing choices to what’s being used rather than what was assumed at kickoff.

Legacy applications need more than lift-and-shift

Legacy systems drag years of dependencies and technical debt, and none of that goes away just because the hosting changed. Cloud migration advisory services do the hard work of sorting out what can shift as-is, what needs refactoring, and what needs rebuilding from scratch.

Business and IT priorities can become disconnected

Cloud projects often get handed to technical teams and left there, with no one checking whether the architecture still meets what the business actually needs—faster time-to-market, better customer experience, lower costs. The result can be technically sound and strategically pointless

Cloud environments introduce new governance challenges

Access controls that made sense on one platform don’t automatically carry over to another, and multi-cloud setups tend to expose that quickly. Gaps show up in unexpected places. A cloud advisory service brings a governance framework that’s built to scale with the environment.


Our team pairs advisory with hands-on cloud engineering — architecture, migration, and integration — so recommendations don’t stay theoretical


What do Cloud Advisory Services Include?

Cloud Strategy Advisory

This planning layer turns a vague decision into a roadmap with clear priorities.

  • Define cloud objectives – Pin down what the business actually wants from the cloud (cost, speed, scale) before making any technical decisions.
  • Select appropriate cloud models – Decide between public, private, or hybrid based on workload needs and compliance constraints.
  • Align cloud investments with business priorities – Make sure every dollar spent maps back to a goal the business actually cares about.
  • Develop short- and long-term roadmaps – Turn the strategy into a phased plan with real timelines, not a vague direction.

Cloud Readiness and Assessment

This phase analyzes every application, system, and dependency to determine what’s ready to move and what isn’t.

  • Application portfolio assessment – Catalog every application to understand what exists and what condition it’s in.
  • Infrastructure assessment – Evaluate current servers, networks, and systems to see what’s actually migration-ready.
  • Dependency mapping – Trace how applications and systems rely on each other so nothing breaks when one piece moves.
  • Technical debt assessment – Identify outdated code, architecture, or shortcuts that will cause problems post-migration.
  • Organizational readiness – Gauge whether teams have the skills and processes to operate in a cloud environment.
  • Risk identification – Flag potential failure points: technical, financial, or operational before they become expensive.

Cloud Migration Advisory Services

This is where the actual shift happens. Workloads get classified, sequenced, and shifted using a strategy suited to each one, rather than a single approach forced onto everything.

  • Migration discovery – Inventory workloads and systems to scope exactly what needs to move.
  • Workload classification – Group applications by complexity, priority, and migration approach.
  • 6R/7R migration strategies – Modern SaaS platforms utilize multiple Rs simultaneously. This includes the 7R migration strategy (Rehost, Replatform, Repurchase, Refactor, Retain, Retire, Relocate)
  • Dependency analysis – Confirm which systems must move together to avoid breaking integrations.
  • Migration sequencing – Order the moves so low-risk workloads go first and critical systems aren’t rushed.
  • Business continuity – Plan around the migration so operations don’t grind to a halt mid-move.
  • Risk management – Build contingencies for when something goes wrong during the move.
  • Migration roadmap — Consolidate all of the above into a single execution timeline.

Cloud Architecture Advisory

Cloud Architecture Advisory covers how systems are structured, connected, and built to withstand real-world load and failure.

  • Target-state architecture – Design what the environment should look like once migration and modernization are complete.
  • Cloud-native architecture – Build systems specifically to take advantage of cloud elasticity and services, not just host them there.
  • Hybrid and multi-cloud architecture – Design environments that span on-prem and multiple cloud providers without creating chaos.
  • Scalability – Ensure the architecture can grow with demand without a redesign.
  • Resilience – Build in redundancy so failures don’t take down the whole system.
  • Integration – Make sure new cloud systems talk properly to existing tools and data sources.
  • Data architecture – Design how data is stored, moved, and accessed across the environment.

Cloud Computing Advisory Services

This is the infrastructure layer itself. The actual building blocks that make up the cloud environment. Choosing the right combination here directly affects both performance and cost.

  • Compute – Choose the right processing power and instance types for each workload.
  • Storage – Select storage tiers based on cost, speed, and access frequency needs.
  • Networking – Design connectivity, load balancing, and traffic routing across the cloud environment.
  • Databases – Pick and configure the right database services for performance and scale.
  • Containers – Use containerization to package applications for portability and consistency.
  • Serverless – Identify workloads that don’t need dedicated infrastructure and can run on-demand instead.
  • Data platforms – Set up systems for processing and analyzing data at scale.
  • Cloud-native services – Evaluate which provider-specific tools are actually worth adopting versus adding unnecessary complexity.

Cloud Security and Compliance Advisory

Cloud environments introduce risks that don’t exist on-premise, and regulatory requirements don’t relax just because infrastructure shifted. This is about building security in from the start, not patching it in afterward.

  • Identity and access management – Control who can access what, and under which conditions.
  • Security architecture – Design the environment so security is built in, not bolted on afterward.
  • Compliance requirements – Map cloud practices to industry regulations like HIPAA, GDPR, or PCI-DSS.
  • Data protection – Encrypt and safeguard data both at rest and in transit.
  • Threat considerations – Anticipate likely attack vectors specific to the cloud environment.
  • Governance frameworks – Set policies that keep security and access consistent as the environment scales.

Cloud Cost Optimization Advisory

Cloud spend tends to drift upward. This is ongoing work to keep usage, pricing, and forecasts under control.

  • Cloud spend assessment – Analyze current billing to see exactly where money is going.
  • Resource utilization – Check whether provisioned resources are actually being used efficiently.
  • Rightsizing – Adjust instance sizes and configurations to match real workload demand.
  • Reserved/committed capacity – Lock in discounted pricing for predictable, long-term workloads.
  • FinOps – Build ongoing financial accountability practices between finance and engineering teams.
  • Cost governance – Set policies and guardrails to prevent unchecked spending going forward.
  • Forecasting- Project future cloud costs based on growth and usage trends.

Cloud Modernization Advisory

Migration gets systems into the cloud. Modernization makes them worth being there, rather than just relocating the same old problems.

  • Application modernization – Update legacy applications to work efficiently in a cloud-native environment.
  • Refactoring – Rewrite portions of code to improve performance without changing core functionality.
  • Replatforming – Make minimal changes to shift an application onto a more efficient cloud platform.
  • Containerization – Package applications into containers for consistency and easier deployment.
  • Microservices – Break monolithic applications into smaller, independently deployable services.
  • API modernization – Update APIs to support better integration and scalability.
  • Data modernization – Migrate and restructure data systems to support modern analytics and applications.

The Role of an Advisory Platform in Cloud Advisory Services

An advisory platform in cloud advisory services acts as a centralized digital hub. It makes sense of data by tracking cloud spend, benchmarking workloads against industry standards, and giving both the advisor and the client a live view of where things stand.


This is also where Experion’s advisory work hands off cleanly into cloud engineering — the same team that shaped the strategy stays on to build and run it, so nothing gets lost in translation.


Cloud Advisory vs. Cloud Consulting Services: What’s the Difference?

What are Cloud Consulting and Advisory Services?

People often use the two terms interchangeably.

  • Cloud consulting tends to focus on execution: implementing specific tools, configuring environments, and solving a defined technical problem.
  • Cloud advisory sits a step earlier. It is less about “how do we build this” and more about “should we be building this, and what happens if we do.”

A consultant fixes what’s already been decided. An advisor helps decide in the first place. In practice, most engagements blend both.


When Should You Engage a Cloud Advisory Consultant?

Leveraging a cloud advisor becomes especially important in the following scenarios: when cloud costs climb exponentially, when a migration goes over budget or stalls, when you need a well-planned cloud strategy, or when a compliance audit reveals gaps in your current process.

How Cloud Advisory Services Work

1. Discover

Every engagement begins here. This involves understanding business objectives, building a complete application inventory, identifying dependencies, and assessing the current infrastructure.

2. Assess

Once the discovery work is done, it’s time to evaluate what’s actually feasible and what’s risky. Assess cloud readiness and application suitability. Flag risks and estimate costs. Evaluate current security posture and technical debt.


Looking for a partner who stays past the roadmap?
Start a conversation with our cloud advisory team


3. Strategize

With the assessment in hand, the focus shifts to deciding what the future environment should actually look like. In this phase, you finalize the end-state cloud environment, select a cloud approach, and prioritize workloads.

4. Plan

Strategy becomes execution ready at this stage. The migration is broken down into manageable phases instead of one large event. Applications that need to get refactored or rebuilt are planned. Finally, budget, resourcing, and tooling needed to execute the plan are clarified.

5. Execute and Optimize

The plan gets carried out at this stage. Implementation is supported, outcomes are tracked, performance & cost are optimized, and the cloud environment is continually refined.


What are the Key Benefits of Cloud Advisory Services?

Cloud Advisory Services

Make better cloud investment decisions

Instead of buying capacity based on guesswork or vendor pitches, decisions get grounded in actual workload data and business priorities. That alone often cuts a lot of wasted spend before it happens.

Reduce migration and modernization risks

Migrations fail—or drag on for years—when teams miss dependencies and misclassify workloads. A structured upfront assessment catches most of that before it becomes downtime or a scrapped project.

Improve cloud cost visibility

Most companies don’t actually know where their cloud spend is going until someone forces the question. Advisory work builds that visibility from the start, so cost surprises become rarer.

Accelerate cloud transformation

A clear plan and proven framework mean less time debating direction and more time executing. Transformation that would’ve taken years of trial and error gets compressed into something closer to a plan.

Modernize legacy applications strategically

Not every legacy app needs the same treatment. Some need a full rebuild; some just need to move as-is. Advisory work sorts that out early, so modernization effort goes where it actually matters.

Strengthen cloud security and governance

Security gaps in multi-cloud environments are often hard to detect. Advisory brings a consistent governance framework that closes those gaps instead of leaving them to be discovered later.

Build a scalable long-term cloud roadmap

A cloud environment built for today’s needs alone will need a redesign the moment the business grows. Advisory work plans for that growth from the outset, so scaling doesn’t mean starting over.


How to Implement Cloud Transformation?

Implementation succeeds when you treat it as a sequence of capability-building steps, not a single large project. Each step should leave the organization better equipped to execute the next.

  • Start by securing an executive sponsor with authority over both budget and business priorities. Cloud transformation forces tradeoffs — between speed and standardization, between modernizing an application and shipping the features its business owner wants this quarter — that technology leadership cannot resolve alone.
  • Establish the landing zone and governance model next, so every workload that follows inherits consistent identity, network, logging, and policy defaults. Retrofitting foundations across a populated estate costs several times what building them first would have. The landing zone is where standards become automatic rather than aspirational.
  • Build a platform team to own those shared foundations, and explicitly define what they own versus what application teams own. Ambiguity here produces either bottlenecks, where the platform team becomes an approval queue, or drift, where teams route around them.
  • Then run a pilot wave. Choose low-risk but representative workloads, and use them to prove the full path end to end—including cutover, monitoring, support handover, rollback procedure, and cost tracking. The purpose of a pilot is to find process gaps, so treat the problems it surfaces as the expected output rather than as evidence that something went wrong.
  • From there, scale in waves, applying the lessons from each one. Wave planning should group workloads by dependency rather than by convenience, so that tightly coupled systems move together and the number of temporary cross-environment integrations stays small.
  • Invest in automation early, because manual migration effort does not scale and manual configuration produces drift. Infrastructure as code, automated pipeline provisioning, and policy-as-code controls pay back within a handful of waves.
  • Run migration and modernization as parallel tracks so applications needing bigger change are not blocked behind a data center exit deadline. Forcing modernization into a migration timeline produces rushed refactors; forcing migration to wait for modernization produces missed deadlines and extended dual-running costs.
  • Throughout, measure business outcomes alongside technical progress, and keep a change management track running for the teams whose work is changing. Workloads migrated is a useful operational metric and a poor success metric.


Cloud Advisory Use Cases

Planning a cloud migration

The most common engagement: discovery, dependency mapping, per-workload strategy selection, wave planning, and a cost model that leadership can approve. The deliverable is a plan detailed enough for a delivery team to begin work and a CFO to commit budget against it. Organizations that skip this stage typically discover their dependency map during cutover weekends.

Modernizing legacy applications

Portfolio analysis to determine which applications justify refactoring, which should be replatformed, and which should be replaced with commercial software. The hard part isn’t the technical assessment; it’s the honest conversation about which systems have a future.

Optimizing an existing cloud environment

Rightsizing, commitment strategy, architecture changes that reduce data transfer or storage costs, and a FinOps practice to hold the gains. The first two deliver quick savings; the third prevents the savings from eroding. Optimization engagements that end without an operating cadence tend to repeat eighteen months later with the same findings.

Building a hybrid or multi-cloud strategy

Deciding which workloads belong where, designing connectivity and identity across environments, and setting realistic expectations about portability. Multi-cloud is often pursued for legitimate reasons — negotiating leverage, resilience, regulatory comfort—but it carries a real operational tax.

Establishing FinOps and cloud cost governance

Allocation, tagging standards, budgets, anomaly alerts, and the cadence between engineering, finance, and product that makes cost a shared responsibility. The technical components are straightforward. The organizational component — getting engineers to treat cost as a design constraint and finance to accept variable spend — is where the engagement succeeds or fails.

Preparing for cloud-native development

Platform foundations: container orchestration, CI/CD, observability, secrets management, and the developer experience that determines whether teams adopt them. Platforms that are technically complete but unpleasant to use get bypassed.

Improving cloud security and compliance

Gap assessment against frameworks and regulations, remediation prioritization, control design, and continuous compliance monitoring. Prioritization matters more than completeness. A list of four hundred findings without severity and effort weighting produces paralysis rather than remediation.

Consolidating fragmented cloud environments

Common after acquisitions or decentralized growth. Inventory across accounts and providers, rationalization of duplicated platforms, and a phased consolidation plan. Consolidation is politically difficult because every duplicated platform has an owner who built it.


How Much do Cloud Advisory Services Cost?

Pricing varies based on the engagement’s scope, size, complexity, and duration. Rather than quoting a single figure, it is more useful to understand how different types of cloud advisory engagements are typically structured.

Advisory engagement Typical scope Typical duration Common pricing model
Focused assessment Limited application portfolio, cloud cost optimization, or security gap analysis A few weeks Fixed-scope
Enterprise cloud strategy Cloud strategy, estate assessment, modernization priorities, and target-state planning 2–4 months Fixed-scope or time-and-materials
Migration roadmap Assessment and prioritization of hundreds of applications, migration waves, dependencies, and timelines 2–4 months Fixed-scope or time-and-materials
Ongoing advisory Continuous architecture, cost, security, governance, and cloud strategy guidance Ongoing Monthly retainer


How to Choose Cloud Strategy and Modernization Advisory Partners?

Selection matters more than in most categories, because the output is judgment, and judgment is hard to evaluate from a proposal.

Look for experience across strategy and execution

Advisors who have only ever written strategies produce plans that do not survive contact with delivery. Confirm real depth across:

  • Strategy — business case development, operating model design, and portfolio prioritization.
  • Architecture — target-state design at comparable scale and complexity.
  • Migration — completed migrations, including the difficult workloads.
  • Modernization — refactoring and replatforming they have delivered, not just recommended.
  • Optimization — measurable cost and performance improvements on live estates.

Evaluate their assessment methodology

  • How do they assess applications? Look for a defined framework with weighted criteria, not ad hoc judgment.
  • How do they identify dependencies? Automated discovery and flow analysis beat interviews alone.
  • How do they calculate migration complexity? A consistent scoring model applied across the portfolio.
  • How do they estimate costs? Modeling should use your utilization data and account for dual-running, egress, licensing, and support.

Ask to see a redacted deliverable from a previous engagement. The quality of a sample roadmap tells you more than any capability deck.

Look for business-focused recommendations

Technical recommendations that never connect to business consequences will not survive a budget review. Every significant recommendation should be tied to:

  • Cost — The effect on run rate and total cost of ownership.
  • Revenue — Capabilities that enable new products, channels, or markets.
  • Risk — Reduction in security, compliance, continuity, or obsolescence exposure.
  • Agility — The organization’s ability to change direction quickly.
  • Performance — Measurable improvements in latency, throughput, or availability.
  • Time to market — How much faster teams can ship after the change.


 Looking for a partner who stays past the roadmap?
Experion works with enterprises from assessment through migration, modernization, and ongoing optimization. Start a conversation with our cloud advisory team


Check Cloud and Industry expertise

Provider certifications indicate baseline capability but are widely held. Industry experience is a stronger differentiator because regulatory obligations, data sensitivity, integration patterns, and seasonality differ substantially across healthcare, financial services, logistics, and retail. A partner who has migrated systems under the same constraints will anticipate problems a generalist discovers late.

Look for continuous advisory capabilities

Avoid an engagement that produces a roadmap and disappears. Cloud environments change continuously: pricing models shift, new managed services replace patterns you standardized on last year, and the estate itself grows. A roadmap that is not revisited becomes inaccurate within a year and ignored within two.


Build a Smarter Cloud Strategy with Experion

Experion has extensive experience working across the full lifecycle- from early cloud strategy and architecture design through migration, integration, and ongoing CloudOps. That includes cloud analytics work to turn raw infrastructure data into decisions worth acting on, and managed services support once the environment is live, so optimization doesn’t stop the day the migration wraps.


Conclusion

Cloud advisory services exist because cloud outcomes are determined long before deployment. The decisions that set your cost curve, security posture, migration risk, and ability to modernize are made during planning, and they are expensive to reverse afterward.

A well-run cloud advisory service gives you an honest picture of your current estate, a target state matched to your objectives, a sequenced roadmap with realistic costs and named risks, a governance model that scales, and continuous guidance as conditions change. It replaces assumptions with evidence at the point where evidence is affordable to gather.

Whether you are planning a first major migration, bringing an unpredictable bill under control, deciding which legacy applications deserve investment, or consolidating an estate that outgrew its governance, the value comes from the same place: making the right decisions before committing significant budget, and documenting the reasoning well enough to revisit when things change.

DevOps Consulting Services

“The DevOps consulting service market is projected to grow, with estimates pointing to an increase of USD 26.28 billion by 2032.”

Modern enterprises need fast, reliable software delivery. However, legacy infrastructure and growing security requirements make DevOps transformation highly challenging. DevOps works by combining development and operations together across the software lifecycle. It effortlessly covers practices such as automation, CI/CD, infrastructure management, monitoring, and continuous improvement.

DevOps consulting services enable organizations to streamline operations through automation, CI/CD, and standardized processes.


Key Takeaways

  • A strategic DevOps approach combines strategy, tooling, automation, and hands-on implementation to accelerate software delivery.
  • Alignment of people, processes, and technology goes beyond configuring pipelines. It involves aligning engineering culture, processes, and technology so speed and stability work together.
  • Cloud expertise brings specialized expertise across AWS, Azure, and multi-cloud environments to support complex infrastructure requirements.
  • Integrated security embeds security into development and deployment pipelines through DevSecOps practices.
  • Continuous optimization often extends beyond initial implementation with ongoing monitoring, improvement, and optimization of DevOps processes and infrastructure.
  • An outcome-driven partnership should involve the right DevOps consulting partner. Evaluate this based on technical depth, relevant industry experience, and measurable outcomes.


What are DevOps Consulting Services?

DevOps Consulting


DevOps consulting services, sometimes called DevOps consulting services and solutions or simply DevOps services and consulting, are engagements where an external team helps you design, build, and run the practices, pipelines, and infrastructure needed to ship software continuously and reliably. DevOps as a Service (DaaS) takes this a step further by providing ongoing access to DevOps expertise, tools, automation, and operational support as a managed service. Most engagements run through the same three phases.

  • Assessment: This stage assesses DevOps maturity, identifies gaps, and defines a realistic roadmap based on the org’s actual constraints.
  • Implementation—CI/CD, infrastructure as code, containerization, automated deployment.
  • Maintenance: Monitoring, adjusting security and performance, reliability, and cloud costs indefinitely. DevOps advisory services provide strategic guidance alongside implementation. It includes maturity assessments, tool selection, governance, roadmaps, etc. A company brings in advisory consultants to build the internal case and align everyone before they sign off on the larger implementation budget.


Why Businesses Need a DevOps Consulting Company?

Companies rarely hire a DevOps consulting company because DevOps sounds appealing in the abstract. They call one because a specific, painful symptom has become impossible to ignore.

Common Pain Points

Hours-long deploys turn into days—complex approval chains, undocumented configs, and scripts. Siloed teams make it worse: every handoff between dev, QA, security, and ops adds delay and creates someone new to blame. And the manual processes—hand-run scripts, undocumented changes—are difficult to troubleshoot and scale effectively.

The Value DevOps Service Providers Deliver

Good providers replace manual, error-prone work with pipelines you can actually audit, so dev and ops stop telling different stories about the same outage. Infrastructure gets codified.

ROI and the Business Case

The pitch leans on four numbers—deployment frequency, lead time, change failure rate, and mean time to recovery. Most decent orgs already track them.

A team that cuts lead time from weeks to days isn’t just faster on one project.


Turn DevOps bottlenecks into a faster, more reliable delivery pipeline.
Talk to Experion


Core Offerings of Top DevOps Consulting Firms

The best DevOps consultancy services build their offerings around the full delivery lifecycle, not a single tool or technology. In complex, multi-system environments, that often means bringing in DevOps experts to address specific bottlenecks, slow pipelines, or legacy release processes, on top of the broader engagement.

DevOps Strategy Consulting & Roadmapping

Before any tool changes, DevOps strategy consulting determines where an organization stands today: release cadence, toolchain maturity, and team structure. From there, it builds a phased roadmap toward the target state, sequenced by business priority and risk.

DevOps Implementation & CI/CD Pipeline Setup

This is where strategy turns into working software. Continuous integration pipelines automatically build and test every code change. Continuous delivery pipelines push validated changes toward production with little to no manual intervention.

Infrastructure as Code (IaC) & Automation

Treating infrastructure as versioned code, using tools like Terraform, Pulumi, or CloudFormation, lets teams provision and modify environments predictably and roll back changes safely. It also eliminates the configuration drift behind most “it worked in staging” failures.

Monitoring, Security & Compliance (DevSecOps)

Building security scanning, secrets management, and compliance checks directly into the pipeline, instead of bolting them on right before release, is what DevSecOps actually means. At this point, it’s table stakes, not a premium add-on.

Managed DevOps as a Service Companies vs. Project-Based Engagements

There are two basic delivery models. DevOps-as-a-service companies run pipelines, infrastructure, and monitoring on an ongoing, subscription basis, essentially acting as an extension of your platform team. Project-based engagements work differently: a defined scope—say, a CI/CD overhaul or a cloud migration—then operations are handed back to you.

Containerization and Kubernetes

Most modern application delivery runs on containers now. Consulting teams package applications into containers to ensure consistency across environments. They set up Kubernetes to handle scaling, self-healing, and rolling updates. And they design microservices architectures where independent services can be built, deployed, and scaled on their own.

Monitoring and Observability

Reliable operations depend on seeing what’s happening. That means real-time application and infrastructure monitoring, plus logging, metrics, and tracing to reconstruct what happened during an incident and why. Mature DevOps consulting companies usually layer service-level objectives and error budgets on top of raw metrics too.


Cloud-Specific DevOps Consulting Services

Cloud platforms shape how DevOps practices get implemented, so most engagements are anchored to a specific provider or a multi-cloud strategy.

Cloud DevOps Consulting Services

Cloud DevOps consulting covers the practices and tooling needed to run CI/CD, infrastructure automation, and monitoring natively on cloud infrastructure. It also covers multi-cloud strategy for organizations that want to avoid vendor lock-in or manage data residency requirements across regions.

AWS DevOps Consulting

AWS DevOps consulting typically covers pipeline design with native services like CodePipeline and CodeBuild, infrastructure as code with CloudFormation or Terraform, and cost optimization that right-sizes compute and storage as workloads scale.

Azure DevOps Consulting Services

Azure DevOps consulting usually centers on Azure Pipelines for CI/CD, ARM templates or Bicep for infrastructure provisioning, and hybrid cloud setups for organizations running a mix of on-premises and cloud workloads.

Multi-Cloud and Hybrid DevOps

For organizations running workloads across multiple providers, the work usually centers on standardizing pipelines and tooling so teams aren’t maintaining separate practices for each cloud. In practice, that means writing infrastructure as code that can target multiple providers.


DevOps and Other Modern Operations Practices

  • MLOps: MLOps relates to Machine Learning, and this practice applies DevOps principles to Machine learning. It covers development, deployment, monitoring, and ongoing management of ML models.
  • GitOps: GitOps uses Git as the central source of truth to define how applications and infrastructure should be configured. This enables version-controlled deployments.
  • ModelOps: Manages models across their lifecycle. It is particularly leveraged in enterprise environments where multiple models need to be deployed or monitored.
  • BizOps: Connects business strategy with operational execution. BizOps uses data, processes, and cross-functional collaboration to improve decision-making.


DevOps vs. IT Ops

They are not competing functions. Instead, ITOps focuses on maintaining systems and security, while DevOps brings development and operations together to speed up software delivery. DevOps’ end outcome is reliable software releases. On the other hand, ITOps focuses on secure, available IT environments.


How to Choose the Right DevOps Consulting Company?

Not every DevOps consulting company fits every organization’s needs. A structured evaluation helps separate genuine expertise from a generic services pitch.

Evaluate Technical Expertise

Look for demonstrated depth across cloud platforms, automation tooling, CI/CD pipeline design, containers, infrastructure as code, and security. Not just familiarity with one or two of these areas.

Look for Relevant Industry Experience

Experience in enterprise environments, regulated industries, legacy modernization, and cloud-native development shows a partner has dealt with the constraints you’re facing. Not just greenfield projects.

Assess Their Implementation Approach

A sound implementation approach moves deliberately through strategy, implementation, and optimization, with real documentation and knowledge transfer along the way. It also includes a change management plan that accounts for how the engagement affects your staff.

Review Case Studies and Outcomes

Ask for concrete before-and-after data: deployment frequency, lead time, reliability metrics, cost optimization achieved, and infrastructure efficiency gains. Vague claims of “faster releases” without numbers are a warning sign.

Consider Geographic and Delivery Requirements

Delivery model matters as much as technical skill. Onshore, offshore, or blended teams. Time-zone coverage for support and incident response. How often you’ll actually talk to the people doing the work. If you’re evaluating DevOps consulting services in the USA, it’s worth checking how a partner’s global delivery centers work alongside US-based teams for coverage and cost.


Managing DevOps across thousands of repositories and distributed engineering teams?
Learn how Experion helped a global automotive manufacturer improve software efficiency and accelerate release cycles


Validate Security and Compliance Credentials

Confirm DevSecOps is actually built into the pipeline, not treated as a separate audit step. That includes secrets management and compliance automation for standards like SOC 2, ISO 27001, GDPR, and HIPAA, where relevant. Audit-ready pipelines with proper access controls should be the baseline.


With experience across complex enterprise environments, Experion can help teams address the practical challenges of DevOps adoption—from legacy systems and fragmented toolchains to security, scalability, and governance.


Enterprise DevOps Consulting: What Sets It Apart

Large organizations face limitations that small companies don’t. As a result, Enterprise DevOps consulting services look different from a typical engagement. Enterprises typically run dozens of interdependent applications and infrastructure accumulated over many years. Hence, enterprise DevOps consulting needs to scale across teams, geographies, and legacy systems at once. Governance, compliance, and change management scale up too- approval workflows, audit trails, and security policies that hold across hundreds of engineers instead of a single team.

DevOps for Legacy Application Modernization

Modernizing legacy applications usually starts with deciding which parts of a monolith can be safely broken into microservices and which should stay intact for now. From there, it’s about replacing manual, high-risk release procedures with automated pipelines. Then moving workloads off legacy infrastructure onto platforms that actually support continuous delivery.

DevOps Governance and Compliance

Enterprise-scale governance comes down to a few things: who can change what and where, a paper trail for every deployment, security checks baked into the pipeline instead of bolted on after, and whatever compliance rules the industry throws at you.

Getting that right — role-based approvals that pass an audit without turning every deploy back into a three-week sign-off chain — is honestly where a decent consultancy earns its keep. Anyone can automate a pipeline. Keeping it automated once legal and compliance get involved is the hard part.


DevOps Consulting Services and Solutions for Different Business Needs

The right engagement model depends on organizational size and maturity. That’s why a one-size-fits-all package rarely works across a consulting firm’s full client base.

Startups and Growing Businesses

Startups usually need fast-to-implement pipelines and cloud infrastructure that scales without a big upfront platform investment. The priority is getting automated builds, tests, and deployments in place early. You can add the full governance and compliance layer later.

Mid-Market Organizations

Mid-market companies often need to formalize processes that grow organically, replacing ad hoc scripts and manual deployments with standardized pipelines. This is often the stage where one engineer’s personal deployment scripts have quietly become a single point of failure. It is also where the case for consultancy is easiest to make, because leadership can already see the risk.

Large Enterprises

Enterprises need the governance, scale, and cross-team coordination described above, delivered by a partner capable of running multi-year transformation programs. These engagements typically unfold in waves: a pilot with one business unit, refinement based on lessons learned, then a broader rollout. Rarely a single big-bang cutover across the organization.

Organizations Modernizing Legacy Applications

These organizations need a phased approach that keeps critical systems running while incrementally introducing automation and modern architecture. The goal is rarely a full rewrite. It’s usually about finding the seams where you can wrap, containerize, or gradually decompose legacy systems without disrupting the business processes that depend on them.

Cloud-First Organizations

Cloud-native companies typically need advanced automation, cost optimization, and multi-cloud or hybrid strategy rather than foundational DevOps setup. These organizations often already have strong engineering practices, so the highest-value work tends to be FinOps discipline, advanced observability, and platform engineering that lets internal teams self-serve infrastructure safely.

Highly Regulated Businesses

Financial services, healthcare, and other regulated industries need DevSecOps and compliance automation built into the pipeline from day one. The consulting engagement often must satisfy internal security teams, external auditors, and regulators at once. This puts a premium on documentation and traceability alongside the technical implementation itself.


DevOps Consulting Services & Solutions in the USA

DevOps Consulting Services


Demand for DevOps consulting services USA has grown alongside enterprise cloud adoption. It’s concentrated in financial services, healthcare, retail, and technology, sectors that depend on reliable releases to stay competitive.

Organizations evaluating a US-based DevOps consulting firm usually weigh cost against time-zone alignment and compliance familiarity. US-based teams tend to know domestic regulatory standards, HIPAA, SOC 2, and state-level privacy laws closely. Blended models that pair US-based leads with global delivery teams can bring real cost savings without losing oversight.

Currently, a few trends are shaping demand:

  • The shift toward platform engineering
  • Internal developer platforms that let teams self-serve infrastructure.
  • Growing adoption of FinOps to control cloud spend.
  • Regulatory pressure that’s turning DevSecOps into a baseline requirement.


The DevOps Consulting Engagement Process

A structured engagement process is what separates a DevOps consulting company that delivers lasting change from one that simply installs tools.

Step 1 — Discovery & Assessment

The engagement starts with an audit: current tooling, team structure, release process, and where things actually break down. That gives a baseline. It usually means interviews across dev, ops, and security—not because it’s thoroughness for thoroughness’s sake, but because the roadmap is useless if it doesn’t reflect how the organization really works, not how the org chart says it works.

Step 2 — Define DevOps Goals and KPIs

That assessment yields a short list of concrete targets: deployment frequency, lead time, reliability. Setting these before any implementation starts gives the consulting team and the internal stakeholders the same yardstick, so six months in, nobody’s arguing about whether the engagement worked.

Step 3 — Strategy & Roadmap Design

The roadmap gets phased by business priority and risk — quick wins first, architectural overhauls later. Front-loading changes that reduce risk or unblock other teams matters more than it sounds; it’s how you keep buy-in instead of everyone waiting for a distant milestone to prove the thing is working.

Step 4 — DevOps Implementation & Tooling Setup

Core tooling gets picked and configured — version control workflows, CI/CD platforms, infrastructure as code, container orchestration if it’s relevant. The real constraint here isn’t what’s best in the abstract; it’s what the internal team can actually keep running once the consultants are gone.

Step 5 — Implement CI/CD and Automation

Build and test pipelines, automating the run from commit through build, test, and deploy. This almost always starts with one representative application rather than the whole portfolio at once — prove the pattern works, then roll it out.

Step 6 — Integrate Security and Monitoring

Layer security scanning, secrets management, and observability into the pipeline so problems surface before release or right after, not three weeks later. Alerting thresholds and dashboards get tuned carefully in this phase too—get it wrong and teams start ignoring every notification.

Step 7 — Continuous Optimization & Support

Once pipelines are live, the work shifts to tuning: performance, cost, adapting as the organization changes. This is also when knowledge transfer actually gets finished — documentation, pairing, runbooks — so the organization isn’t stuck needing the consulting partner forever.


Find the gaps slowing down your software delivery.
Get in touch with us for a devops consultation


Benefits of Partnering with a DevOps Consulting Services and Solutions Company

Organizations that commit to a full-time engagement with DevOps consulting services see multiple gains in the following areas:

  • Faster time-to-market: Manual bottlenecks disappear from the release process.
  • Reduced operational costs: Better automation and resource use reduce operational costs.
  • Improved reliability and scalability: Infrastructure becomes consistent and reproducible.
  • Stronger security posture: DevSecOps is built into the pipeline instead of being added on.
  • Lower Operational Costs: These savings compound over time, too, as right-sized infrastructure and automated scaling keep cutting waste long after the initial engagement ends.
  • More Efficient Cloud Operations: Continuous monitoring, infrastructure optimization, and automated scaling improve cloud performance while controlling resource usage.


Common Myths About DevOps Consulting

The common myths around DevOps include the following:

  • “DevOps is just tools“: Tools are important, but adding new tooling onto old workflows rarely delivers much if team structure, ownership, and process don’t change with it. A CI/CD platform layered over siloed teams with unclear ownership will automate the dysfunction just as efficiently as it automates a healthy process. Tooling amplifies whatever already exists.
  • “Only large enterprises need a DevOps solutions provider” Startups and mid-market companies often benefit even more from a DevOps solutions provider, precisely because they don’t have a dedicated platform engineering team to build these practices in-house. Waiting until you’re “big enough” to justify an internal platform team usually just means years of accumulated manual process and technical debt to unwind later, at a much higher cost than doing it right from the start.
  • “In-house teams don’t need a DevOps consultant”: Even strong internal teams benefit from an outside perspective on emerging practices, tooling choices, and the blind spots that are hard to see due to day-to-day operations. Internal teams are also invested in defending decisions they already made. DevOps consulting companies have no such attachment and can recommend the right path when needed.


Conclusion: Partner with the Right DevOps Consulting Services and Solutions Company

The end outcome of DevOps consulting is an overall DevOps transformation, and picking the right tools was never the whole story. What matters is a proper strategy, disciplined automation, built-in security, cloud expertise that fits your environment, and a plan for continuous optimization. The organizations that get the most out of DevOps consulting treat it as a long-term shift in how their operational strategy works.

At Experion, that’s how we’ve structured our approach: deep cloud and platform engineering expertise paired with the delivery discipline to carry a DevOps transformation from strategy through implementation and into ongoing optimization, so the gains keep compounding instead of fading after go-live.

Trade Finance Software

Trade finance continues to involve significant friction. A single transaction can require coordination among exporters, importers, banks, logistics providers, insurers, customs authorities, payment networks, and regulators, yet the information that ties them together is often strewn over documents, emails, portals and disconnected systems.

The ICC Digital Standards Initiative notes that global trade can involve more than 40 official and commercial documents, contributing to repeated data entry, slow verification, and greater risk of error. Modern trade finance software reduces that complexity by connecting transactions, documents, workflows, risk controls, financing and payments in a more streamlined digital environment.

Experion brings together product engineering, payments modernization, SWIFT integration, AI-led reconciliation, KYC and risk workflows, cloud modernization, and open banking capabilities to help banks, fintechs, and enterprises improve visibility, reduce operational friction, and scale trade finance more effectively.


Key Takeaways

  • Trade finance modernization is, first and foremost, an information flow and integration problem, not just a digitization problem.
  • Automation creates the most value when documents, compliance, risk, payments, and exception management are connected.
  • AI may lessen the need for manual review, but governance, explainability and monitoring by humans are still required for high-risk judgments.
  • API-first modernization lets institutions improve legacy environments in stages, rather than rip and replace.
  • The right success measures are processing time, straight-through processing, exception rates, cost per transaction, and customer experience.


What is Trade Finance Software?

Trade Finance Software

Trade finance software is the digital layer that helps banks, financial institutions, and enterprises manage the movement of money, documents, risk, and approvals across trade transactions.

At its best, it’s more than just digitizing letters of credit, guaranties, collections or financing procedures. It ties together the numerous elements of a trade transaction into a single coordinated process so that teams can understand what has transpired, what is pending, where risk rests and what action needs to be taken next.

That matters because trade finance is never a single-system process. A transaction may involve commercial documents, customer and counterparty data, compliance checks, credit decisions, payment instructions, settlement, reconciliation, and reporting, spread across a multitude of apps and organizations.

A modern trade finance platform pulls together these moving parts through workflow automation, document intelligence, APIs, risk controls, and real-time visibility. By linking information and processes across the trade lifecycle, organizations can reduce operational gaps, improve transaction visibility, and manage complex trade activity more efficiently at scale.

Core Processes

Typical capabilities include:

  1. Letters of Credit : Manage issuance, document checks, amendments, and settlement.
  2. Bank Guarantees : Handle guarantee requests, approvals, issuance, renewals, and claims.
  3. Documentary Collections : Control the flow of trade paperwork between buyers, sellers and banks.
  4. Import and Export Finance : Help with financing needs related to buying and selling goods across borders.
  5. Supply Chain Finance : Help buyers and suppliers improve cash flow through structured financing.
  6. Invoice Financing : Enable businesses to access funds against approved invoices.
  7. Trade Loans : Provide short-term funding for trade-related working-capital needs.
  8. Receivables and Payables : Monitor incoming and outgoing payments and improve cash-flow visibility.

Difference Between Traditional and Manual Trade Finance Processes and Digital Platforms

Traditional trade finance often distributes information across emails, documents, spreadsheets, banking applications, and specialized systems.

But a digital platform creates a shared workflow. Information entered once can move downstream, validations can happen automatically, exceptions become visible, and users can act without repeatedly searching for the latest document or transaction status.

How Trade Finance Software Works?

A typical trade finance workflow passes through a series of connected steps:

  • Transaction initiation – The buyer, seller, or bank starts the trade finance request.
  • Document collection – Required documents such as invoices, purchase orders, bills of lading, and certificates are collected.
  • Validation – Ensure all documentation and transaction details are complete and accurate.
  • Risk assessment – The bank or financial institution assesses credit, counterparty, country, and transaction related risks.
  • Compliance checks – KYC, AML, sanctions, and other regulatory checks are completed.
  • Approval – Once the transaction meets the required conditions, it proceeds through the necessary approval process.
  • Financing – Funding is provided based on the agreed trade finance arrangement.
  • Settlement – Payments are processed between the relevant parties.
  • Reconciliation – Transactions, payments, and records are matched to identify and resolve any differences.
  • Reporting – The completed transaction is captured for operational, financial, risk, and regulatory reporting.

The goal is not necessarily to remove people from that chain. It is to remove the repetitious tasks so that people can work on exceptions, risk and decisions that really demand human judgment.


Why Businesses Need Trade Finance Software and What Problems Does it Solve?

The challenge is not that trade finance lacks processes. It is that too many of them still depend on disconnected systems, repeated checks, and manual handoffs. As trade grows more complex, those gaps become harder to manage and more expensive to ignore.

Trade finance software helps businesses reduce that friction by improving visibility, strengthening control, and making transactions easier to manage across the trade lifecycle. Here are some of the key challenges it helps address:

Increasing Complexity of Global Trade

Cross-border trade involves multiple jurisdictions, currencies, regulations, counterparties, transport networks, and financial institutions. A delay at any handoff can affect working capital and delivery commitments.

Growing Volume of Trade Documentation

Commercial invoices, bills of lading, certificates of origin, insurance documents, packing lists, guarantees, and financing documents may all need validation.

ICC estimates that wider adoption of electronic bills of lading alone could save approximately $6.5 billion in documentation costs.

Pressure to Reduce Manual Processes

Re-keying information from documents into multiple applications is slow and creates avoidable error. Good trade finance automation software captures information once and reuses validated data across the workflow.

Need for Better Risk and Compliance Management

Trade is particularly challenging because risk can sit across counterparties, goods, jurisdictions, payments, and documents.

FATF continues to identify trade-based money laundering as a significant risk and emphasizes stronger sharing of financial and trade data.

Demand for Real-Time Visibility

Customers increasingly expect to know whether a document has been received, whether an exception is holding up approval, and when financing or settlement will occur.

That visibility should not require five emails and three phone calls


Core Features of Trade Finance Software

A strong trade finance platform offers the tools needed to execute transactions more efficiently end-to-end, including document processing, risk, payments and reporting. Some of the basic capabilities that make this feasible are:

  • Trade Transaction Management – Creates a single view of transactions, parties, documents, milestones, and exceptions.
  • Letter of Credit Management – Supports issuance, amendment, document examination, discrepancies, and settlement workflows.
  • Bank Guarantee Management – Digitizes guarantee requests, issuance, amendments, expiry tracking, and claims.
  • Document Digitization/OCR – Extracts structured information from invoices, bills of lading, certificates, and other documents.
  • Workflow Automation – Routes work according to transaction type, value, risk, geography, and exception.
  • KYC/AML Sanctions Screening  – Connects customer, counterparty, sanctions, and AML controls to transaction workflows.
  • Risk Management – Combines credit, counterparty, transaction, country, and operational risk signals.
  • Supply Chain Finance Modul – Supports buyer-led financing, supplier onboarding, invoice approval, and early-payment programs.
  • API & SWIFT Connectivity – Links connecting trading venues with banks, payment networks, corporates, fintechs, and external systems.
  • Payment and Settlement Management – Links approved transactions with payment instructions, tracking, settlement, and reconciliation.
  • Multi-Currency & Multi-Entity Support – Supports organizations trading across geographies, currencies, and legal entities.
  • Analytics & Reporting Dashboard – Provides visibility on volumes, exposure, delays, revenue and exceptions by turning transaction data into actionable information.
  • Notifications and Alerts – Proactively identifies and intimates document gaps, compliance exceptions, approaching expiries, and delayed approvals.


How Trade Finance Software Benefits Financial Institutions?

When the right capabilities work together, trade finance software can add value far beyond process automation. Here are some of the key benefits financial institutions can reap:

  • Faster Transaction Processing – Automation reduces time spent checking, routing, and re-keying information.
  • Reduced Operational Costs – Straight-through workflows lower manual handling per transaction.
  • Improved Risk Management – Connected data makes exceptions and unusual patterns easier to identify.
  • Stronger Compliance – Controls become part of the workflow rather than a separate downstream task.
  • Better Customer Experience – Customers gain clearer status information and fewer manual interactions.
  • Improved Profitability – Faster processing and lower cost-to-serve can make more transactions economically viable.

This is significant in a market where funding remains tight. ADB’s latest major global survey put the trade finance gap at $2.5 trillion, representing unmet financing demand from importers and exporters.


How Trade Finance Software Benefits Importers and Exporters?

For corporates, the benefits are practical: faster financing, improved cash-flow visibility, fewer document errors, easier bank collaboration, faster payments, less administrative compliance work, and stronger supplier relationships.

A credible corporate trade finance platform should answer three questions quickly: Where is my transaction? What is holding it up? What do I need to do next?


How Trade Finance Platform Supports the Full Transaction Lifecycle?

The greatest value comes when the platform connects the entire lifecycle rather than digitizing one isolated step.

For example, information extracted from a commercial invoice can support document validation, compliance screening, financing decisions, payment initiation, reconciliation, and reporting without the need to re-key the data.


Types of Trade Finance Software Solutions

  1. Trade Finance Software for Banks – Designed around products such as letters of credit, guarantees, collections, financing, compliance, and settlement.
  2. Corporate Trade Finance Software – Helps treasury and finance teams manage bank relationships, trade instruments, cash positions, and transaction visibility.
  3. Trade Finance Management Platforms – Provide broader workflow, data, document, and integration capabilities.
  4. Supply Chain Finance Platforms – Connect buyers, suppliers, financiers, approved invoices, and working-capital programs.
  5. Trade Finance Software as a Service – Cloud-delivered platforms can reduce infrastructure overhead and accelerate deployment where regulatory requirements permit.


Trade Finance Software vs. Traditional Trade Finance Processes

Area Traditional Process Trade Finance Software
Documentation Manual Digital
Data entry Repetitive Automated
Approvals Email/paper Workflow-based
Compliance Manual checks Automated screening
Visibility Limited Real-time
Reporting Manual Automated
Risk monitoring Reactive Continuous
Collaboration Fragmented Centralized
Scalability Difficult Easier

How AI Is Transforming Trade Finance?

Trade Finance Software

AI becomes valuable when it tackles work that actually slows transactions.

  • Intelligent Document Processing – AI can extract, classify, compare, and validate information across large document sets.
  • AI-Powered Risk Assessment – Models can surface patterns across customer, transaction, payment, and historical data.
  • Fraud Detection – Anomaly detection can highlight unusual transaction relationships or document inconsistencies.
  • AI-Powered Compliance – AI can support screening, alert prioritization, case summaries, and compliance research.
  • Generative AI for Trade Finance – GenAI can summarize cases, explain discrepancies, search policies, and assist operations teams.
  • AI Agents for Trade Finance Automation – Agents could eventually coordinate multi-step activities such as document collection, validation, status checking, and exception routing.

But autonomy must follow risk. A low-risk document lookup is very different from releasing payment or overriding a sanctions alert.


Experion already applies AI within financial workflows including document extraction, validation, reconciliation, KYC, compliance checks, risk decisioning, and exception handling. Those capabilities create a practical foundation for developing AI-assisted trade finance workflows rather than treating AI as an additional interface layered on top.


Role of Automation in Trade Finance

Automation can take much of the repetitive work out of trade finance by moving routine activities through predefined workflows with less manual intervention. It can help capture data from documents, route approvals, run compliance checks, trigger payments, reconcile transactions, generate reports, and flag exceptions for review. The real value is not simply doing tasks faster. It is reducing delays between steps, improving consistency, and allowing operations teams to focus their attention on the transactions that genuinely need judgment or intervention.

Straight-Through Processing

Straight-through processing allows eligible transactions to progress automatically when predefined conditions are met.

The important word is eligible. High-risk or ambiguous transactions should move to people with the context needed to make the decision.


Cloud-Based Trade Finance Software

Benefits of Cloud Deployment

Cloud-based trade finance software can scale more easily as transaction volumes, users, and geographic operations grow, without requiring the same level of on-premise infrastructure expansion. It also gives authorized teams secure access across locations, supports faster deployment of updates and new features, and improves resilience through distributed infrastructure, backup, and recovery capabilities. For banks and enterprises modernizing legacy environments, cloud deployment can also reduce the effort involved in maintaining physical infrastructure while making it easier to integrate new digital services over time.

Cloud Security Considerations

The benefits of cloud deployment depend on how securely the environment is designed and governed. Sensitive trade, customer, and payment data should be protected through encryption, strong identity and access controls, continuous monitoring, and clearly defined data-storage and residency policies. Backup, disaster recovery, auditability, and regulatory requirements should also be built into the architecture from the outset so that scalability and accessibility do not come at the expense of security, compliance, or operational resilience.


Integrations Required for Trade Finance Software

Trade finance rarely exists in isolation. A modern platform needs to connect with the systems that already manage customers, payments, risk, documents, and financial operations.

  1. Core Banking Systems : Connect trade finance transactions with customer accounts, limits, balances, and core banking workflows.
  2. ERP Systems : Link purchase orders, invoices, receivables, payables, and treasury data with trade finance processes.
  3. Payment Systems : Enable approved transactions to move seamlessly into payment initiation, settlement, and reconciliation.
  4. KYC and AML Platforms : Bring customer verification and anti-money-laundering checks directly into transaction workflows.
  5. Sanctions Screening Systems : Screen customers, counterparties, and transactions against relevant sanctions and watchlists.
  6. Credit Risk Platforms : Provide access to credit limits, exposure data, and risk assessments before financing decisions are made.
  7. Document Management Systems : Store, retrieve, track, and manage the trade documents required across the transaction lifecycle.
  8. APIs and Open Banking Ecosystems : Enable secure data exchange with banks, fintechs, corporate systems, and external financial services.

SWIFT remains central to global financial connectivity, with more than 11,000 financial institutions connected to its network. Its broader push toward standardized, interoperable financial messaging reinforces why modern trade platforms need strong integration architecture rather than closed technology stacks.

Experion has relevant experience here, including payment ecosystems spanning processing, settlement, reconciliation, SWIFT integration, cross-border payments, and integrations across more than 40 banks and 80 countries.


Data Security and Compliance in Trade Finance Software

  • Data Encryption : Protect sensitive information at rest and in transit.
  • Role-Based Access Control : Limit actions and data according to responsibility.
  • Audit Trails : Record who did what, when, and why.
  • Identity and Access Management : Apply strong authentication and controlled privileges.
  • Regulatory Compliance : Translate regulatory obligations into workflows and controls.
  • Data Privacy : Manage jurisdiction-specific requirements around storage and use.
  • Fraud and Cybersecurity Controls : Monitor transactions, users, integrations, and infrastructure for suspicious activity.


How to Choose the Right Trade Finance Solution Provider?

Do not start with the longest feature list. Ask whether a provider understands your workflows, can integrate with existing systems, has experience with secure financial platforms, understands compliance and data architecture, and can explain how the system will evolve.

The best trade finance solution providers should be able to connect engineering choices to operational outcomes.


How Much Does Trade Finance Software Cost?

There is no one-size-fits-all cost for trade finance software. Pricing depends on the platform’s scale, complexity, integrations, customization, deployment model, security requirements, and the capabilities an organization chooses to implement.

Factors Affecting Cost

The cost of trade finance software is shaped by the scale and complexity of the environment it needs to support. Factors such as the number of users, transaction volumes, modules, degree of customization, and the number of integrations all influence implementation effort. Deployment choices, including cloud, on-premise, or hybrid models, can further affect infrastructure and security requirements, while advanced AI capabilities may add complexity around data, governance, and model integration. Geographic coverage also matters, especially when the platform must support multiple currencies, jurisdictions, regulations, and data-residency requirements. Beyond implementation, organizations should also account for ongoing maintenance, upgrades, monitoring, support, and compliance changes when evaluating the total cost of ownership.

Custom Trade Finance Solution vs. Off-the-shelf Software

Factor Build Buy
Customization High Moderate–High
Initial investment Higher Lower
Implementation Longer Faster
Control High Vendor dependent
Maintenance Internal Vendor supported
Scalability Organization dependent Usually built-in

When Should a Business Consider Custom Trade Finance Software?

A custom solution makes sense when standard platforms cannot fully support the way a business actually operates. This is generally the case when workflows are highly specialized, integrations are difficult, transaction volumes are big, risk models are proprietary or the company needs more control over the user experience and how the platform evolves over time.


How to Implement a Trade Finance Platform

The most successful implementations are those that first understand the current operating paradigm, then layer in new technologies. A phased approach helps organizations modernize with minimal disruption while keeping business priorities, compliance, data, and user adoption aligned from the start.

Step 1 – Assess Existing Processes

Map current workflows, systems, pain points, manual handoffs, and bottlenecks to identify where technology can create the most value.

Step 2 – Define Business and Technical Requirements

Translate operational needs into clear requirements around functionality, integrations, security, compliance, scalability, and user experience.

Step 3 – Select the Technology Approach

Decide what should be retained, modernized, integrated, configured, or built based on business priorities and long-term goals.

Step 4 – Design the Architecture

Create a secure, scalable architecture that can support workflows, APIs, data, analytics, and future enhancements without unnecessary complexity.

Step 5 – Integrate Existing Systems

Connect the platform with core banking, ERP, payments, KYC, risk, document, and other critical systems to create a more continuous transaction flow.

Step 6 – Migrate and Validate Data

Move required data carefully, cleanse inconsistencies, and validate accuracy so the new platform starts with reliable information.

Step 7 – Configure Workflows

Set up approvals, business rules, alerts, exception handling, and automated processes based on how transactions actually move through the organization.

Step 8 – Test Security and Compliance

Validate access controls, audit trails, data protection, regulatory requirements, and transaction controls before launch.

Step 9 – Train Employees

Prepare users for new workflows, tools, and responsibilities so adoption does not become a barrier to value.

Step 10 – Launch and Monitor

Roll out the platform, track performance against agreed KPIs, and continuously refine workflows based on user feedback and operational data.


Trade Finance Software Architecture

A trade finance platform consists of multiple technology layers that work together to take a transaction from a user request through processing, validation, integration, and reporting. Separating these responsibilities into layers makes the platform easier to scale, integrate with existing systems, secure, and modernize over time.

The simplified architecture is as follows:

User Interface
Where customers and bank teams initiate transactions, upload documents, review status, and take action.
↓
Trade Finance Application Layer
Where core trade products such as letters of credit, guarantees, collections, and financing are managed.
↓
Workflow & Business Rules Engine
Where approvals, validations, routing rules, exceptions, and transaction-specific requirements are applied.
↓
AI / Analytics Layer
Where document intelligence, risk analysis, anomaly detection, forecasting, and decision support can be embedded.
↓
Integration / API Layer
The connectivity layer that allows the trade platform to exchange information securely with other systems.
↓
Core Banking / ERP / Payment / Compliance Systems
The existing enterprise and banking systems that provide customer, account, payment, risk, compliance, and financial data.
↓
Data & Cloud Infrastructure
The underlying foundation that stores and processes data and provides the computing capacity, resilience, and scalability required by the platform.

Front-End Layer

This is the part users interact with. It provides role-based experiences for corporate customers, relationship managers, trade operations teams, approvers, and other users, allowing them to initiate requests, submit documents, track transactions, and respond to exceptions.

Application Layer

The application layer contains the core trade finance functionality. It manages products and transactions such as letters of credit, guarantees, documentary collections, trade loans, and other financing arrangements across their lifecycle.

Workflow Engine

The workflow engine determines what happens next in each transaction. It applies business rules, routes requests for approval, triggers checks, manages exceptions, sends alerts, and ensures that transactions follow the appropriate process.

AI and Analytics Layer

This layer adds intelligence to the platform. AI can support document extraction and validation, identify anomalies, assist with risk assessment, prioritize exceptions, and surface insights from transaction data. Analytics can provide visibility into volumes, turnaround times, exposures, bottlenecks, and performance.

API/Integration Layer

Trade finance depends on information held in many other systems. APIs and integration services connect the platform with core banking, ERP, payment networks, SWIFT, KYC and AML tools, sanctions screening, credit systems, and external partners, reducing the need for repeated manual data exchange.

Data Layer

The data layer unifies transaction, customer, document, payment, risk, and operational information. A well-designed data foundation also helps generate a consistent view of each transaction and supports reliable reporting, analytics, automation, and AI.

Security Layer

Security should not operate as a standalone component. It must cover the full architecture from the user interface to APIs and data. Identity and access management, encryption, audit trails, monitoring, data privacy, cybersecurity controls, and governance help ensure that sensitive trade and financial information stays protected throughout the transaction lifecycle.


Common Challenges in Implementing Trade Finance Software

  • Legacy System Integration : Avoid turning modernization into an unnecessary core replacement.
  • Data Migration : Poor-quality historical data can undermine even a strong new platform.
  • Regulatory Complexity : Requirements vary across jurisdictions and transaction types.
  • Employee Adoption : Design around actual users, not idealized workflows.
  • Cybersecurity Risks : More connectivity means a larger attack surface.
  • Process Standardization : Automating a broken process only makes the broken process faster.
  • Managing Multiple Stakeholders : Banks, corporates, regulators, operations teams, and technology teams often see the same transaction differently.
  • Maintaining Data Quality : Automation depends on trustworthy information.


Key KPIs to Measure Trade Finance Software Success

Some of the key KPIs include transaction processing time, cost per transaction, straight-through processing rate, document processing time, error rate, compliance exception rate, fraud detection rate, approval turnaround time, reconciliation time, customer satisfaction, trade finance revenue, and operational productivity.

Together, these KPIs indicate the platform’s genuine impact: whether it is speeding up transactions, minimizing manual effort and cost, improving accuracy and compliance, strengthening risk control, enhancing customer experience, and helping the business handle larger volumes more efficiently.


Future Trends in Trade Finance

Trade finance is moving toward more connected, data-driven, and automated operating models that reduce friction while improving speed, visibility, and control across transactions.

  • AI-Powered Trade Operations: AI will increasingly support decision-making, exception handling, risk assessment, and operational workflows.
  • Intelligent Document Processing: Advanced document intelligence will help extract, validate, and compare information faster across complex trade documentation.
  • Generative AI and AI Agents: GenAI and AI agents can assist with case summaries, document review, workflow coordination, and knowledge-intensive tasks.
  • Open Banking and API-Based Finance: APIs will make it easier to connect banks, fintechs, enterprises, and financial services within more seamless trade journeys.
  • Digital Trade Documents: Electronic trade documents will reduce dependence on paper and make information easier to exchange, verify, and process.
  • Real-Time Trade Data: More timely data will help organizations improve transaction visibility, decision-making, and risk monitoring.
  • Embedded Trade Finance: Financing can increasingly be integrated directly into procurement, commerce, and supply-chain workflows.
  • Cloud-Native Platforms: Cloud-native architectures can make trade finance platforms easier to scale, integrate, update, and evolve.
  • Predictive Risk Analytics: Predictive models can help identify emerging credit, transaction, and counterparty risks earlier.
  • Greater Automation and Straight-Through Processing: More routine transactions will move through predefined workflows with minimal manual intervention, helping reduce cost and turnaround time.


Best Trade Finance Software Use Cases

The value of trade finance software becomes clearest when it solves a specific operational problem. Across the following use cases, the opportunity is to remove delays, reduce manual intervention, strengthen control, and give businesses and financial institutions a clearer view of every transaction.

Letter of Credit Processing

Scenario: The bank works with letters of credit, which involve several documentation and parties.
Problem: Manual document reviews and discrepancies handling can delay approvals.
Software intervention: Digital workflows can centralize documents, automate validations, route exceptions, and track approvals.
Outcome: Faster turnaround, fewer errors, and increased visibility throughout the LC lifecycle.

Automated Trade Document Processing

Scenario: Operations teams have to go through vast numbers of invoices, bills of lading, certificates and other trade papers.
Problem: Manual comparison takes too much time and repetitive data entry raises the chance of error.
Software intervention: OCR and intelligent document processing that automatically extracts, classifies and validates information.
Result: Teams may review documents faster, with improved accuracy and have more time to focus on exceptions.

Supply Chain Finance

Scenario: Suppliers may need to wait weeks or months for buyers to settle approved invoices.
Problem: Long payment cycles can place pressure on supplier working capital.
Software intervention: A supply chain finance platform can connect approved invoices with financing options and automate the supporting workflows.
Outcome: Earlier access to cash for suppliers while buyers retain agreed payment terms.

Trade Compliance

Scenario: A cross-border transaction may require multiple KYC, AML, sanctions, and regulatory checks.
Problem: Fragmented screening can create delays and make exceptions difficult to manage consistently.
Software intervention: Integrated compliance workflows can automate checks, consolidate alerts, and route higher-risk cases for review.
Outcome: Faster screening, stronger control, and a clearer audit trail.

Risk Monitoring

Scenario: Credit, counterparty, country, and transaction risks can change while trade activity is underway.
Problem: Periodic or disconnected reviews may identify emerging risks too late.
Software intervention: Connected data and analytics can continuously monitor relevant risk signals and flag unusual activity.
Outcome: Earlier intervention and better-informed risk decisions.

Digital Guarantees

Scenario: Bank guarantees often pass through requests, approvals, issuance, amendments, renewals, and expiry management.
Problem: Manual tracking can lead to delays or missed actions.
Software intervention: Digital guarantee workflows can centralize the lifecycle and automate approvals, notifications, and expiry tracking.
Outcome: Greater control, faster processing, and fewer administrative gaps.

Cross-Border Payments

Scenario: A trade transaction may be approved for payment but still move through separate payment, settlement, and reconciliation processes.
Problem: Disconnected systems can reduce visibility and create additional manual work.
Software intervention: Integrating trade workflows with payment rails, SWIFT connectivity, settlement, and reconciliation can create a more continuous flow.
Outcome: Faster payments, improved transaction visibility, and more efficient reconciliation.

Trade Finance Software for Banks

For banks, trade finance software is increasingly imperative because trade businesses are becoming harder to manage through fragmented legacy processes. Banks are expected to support faster decisions, more complex regulatory requirements, and increasingly digital corporate customers, all while protecting margins in an operations-heavy business.

A modern trade finance platform helps banks make that model more sustainable. It can reduce the cost and complexity of servicing trade transactions, improve the bank’s ability to respond quickly to customers, and create a stronger foundation for launching new digital trade products. Just as importantly, it allows banks to grow trade volumes without allowing operational effort to grow at the same pace, making technology a direct enabler of both customer retention and profitable growth.


Conclusion: Building a Smarter, More Connected Trade Finance Ecosystem

The future of trade finance will not be defined by adding another layer of software. It will be defined by how effectively banks and enterprises can simplify complexity across documents, decisions, risk, payments, and customer interactions.

That is where Experion can add meaningful value. By combining financial services domain understanding with product engineering, payments modernization, SWIFT integration, AI, cloud, API-led architecture, reconciliation, and risk capabilities, Experion can help organizations modernize trade finance around the way their business actually operates.

The opportunity is to build platforms that are not only more digital, but more responsive, easier to scale, and better equipped to adapt as customer expectations, regulations, and trade models evolve.